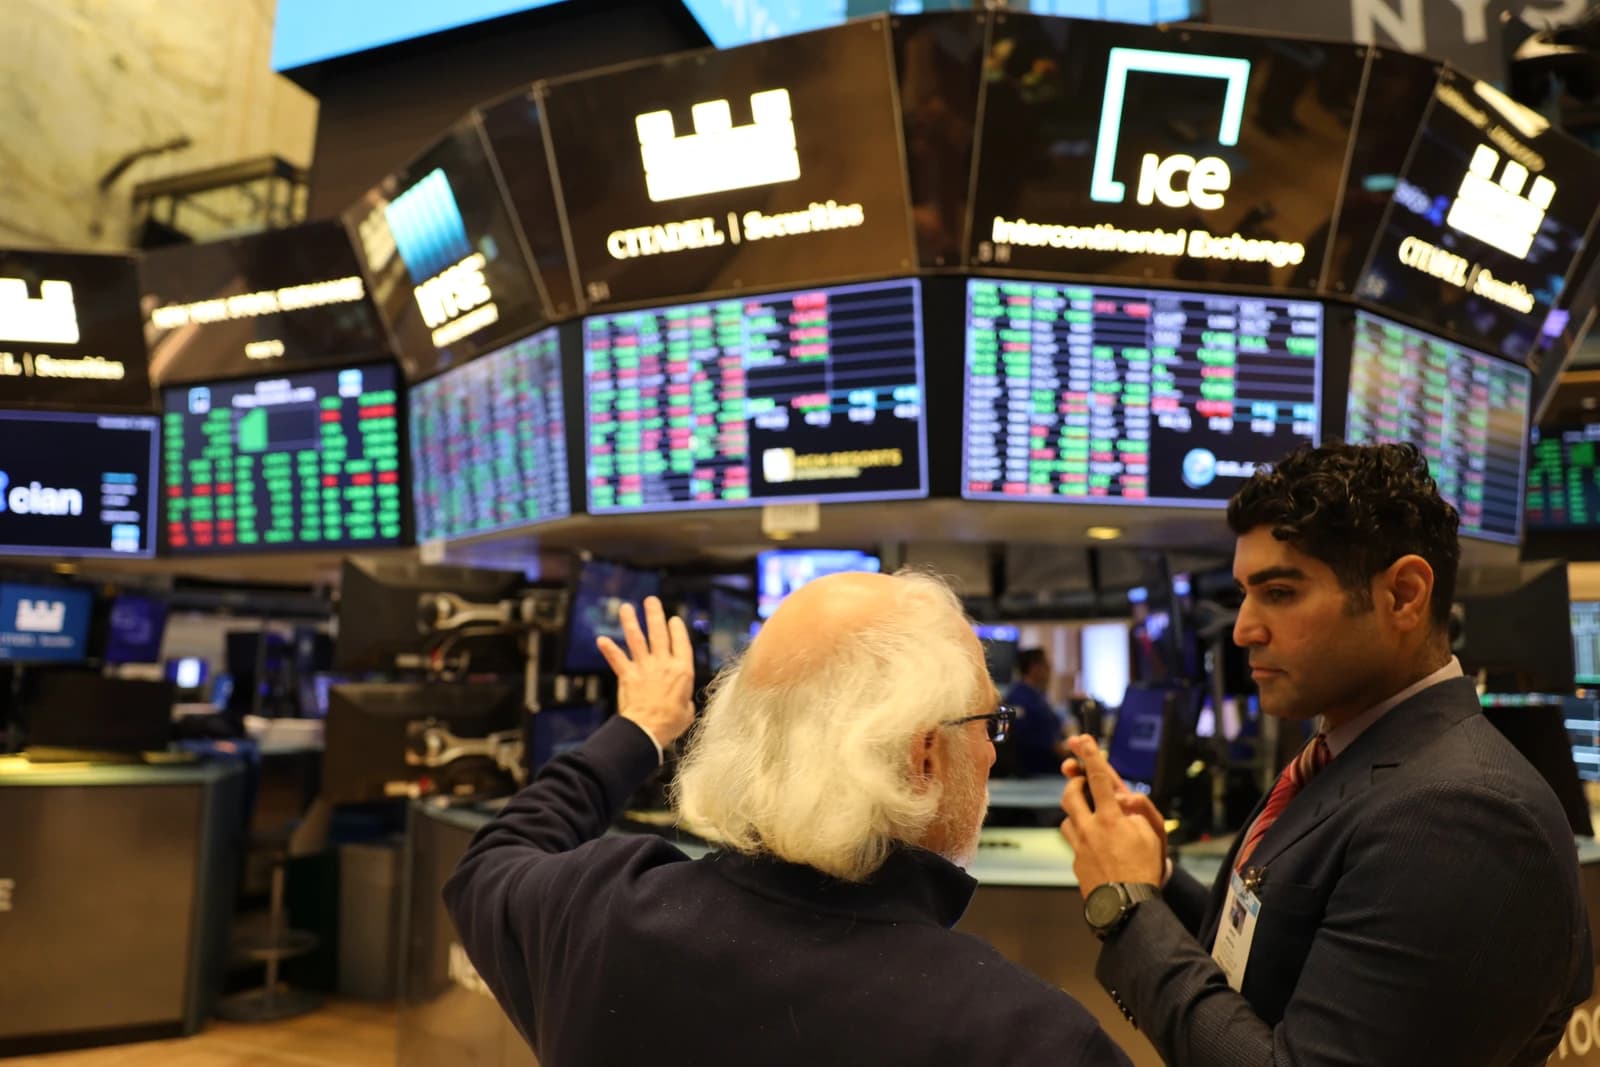
European equities closed slightly lower as investors sat on their hands ahead of the U.S. midterms, with Portugal’s PSI dragged down by a sharp selloff in Corticeira Amorim and a weaker BCP.
European stocks slip as Portugal PSI falls on earnings
That may look like a modest decline, but the market message is bigger: traders are positioning for a possible shift in Washington’s policy balance that could ripple through fiscal spending, regulation and risk appetite well beyond election day. When U.S. politics is in flux, Europe rarely trades on its own fundamentals for long. The result is a session defined by caution, thinner conviction and selective stock-specific punishment.
Sentiment Indicators
The PSI slipped 0.31% to 9,223.89 points, with losses spread across most sectors. Corticeira Amorim was the index’s worst performer, tumbling 9.57% to 6.33 euros after reporting weaker revenue and net profit over the first nine months of the year. BCP fell 2.74% to 1.0480 euros, while Semapa lost 2.42% to 19.36 euros. On the upside, EDP Renováveis led gains with a 3.82% rise to 13.05 euros, followed by NOS and CTT.
The broader European tone was similarly soft. The EuroStoxx 50 shed 0.51% and the Stoxx 600 lost 0.58%, while London’s FTSE 100 underperformed with a 1.14% drop. Germany’s DAX slipped 0.45%, France’s CAC 40 fell 0.34% and Spain’s IBEX 35 lost 0.79%. Italy’s FTSE MIB was nearly flat.
For investors, this is exactly the kind of market where stock selection matters more than index direction. Corticeira’s decline shows how quickly weak earnings can overwhelm a defensive reputation, while BCP’s move reflects the sensitivity of financials to both political uncertainty and the direction of rates. With the 10-year U.S. Treasury yield around 4.95% and European sovereign yields also higher, the cost of capital is not easing enough to support broad multiple expansion.
Oil prices also fell on reports of renewed diplomatic contacts in the Middle East, briefly easing some of the geopolitical premium embedded in energy markets. Brent dropped 1.37% to $103.33 a barrel and WTI fell 0.61% to $95.87. That matters because it gives risk assets a little breathing room, but it does not remove the underlying fragility in global sentiment.
The real investable takeaway is that markets remain trapped between policy uncertainty and earnings dispersion. If the U.S. midterms alter the balance of power in Washington, the next leg for equities will likely come not from a broad macro bet, but from the second-order winners: utilities, renewables, quality exporters and balance-sheet strength. The losers will be the companies that need stable demand, easy funding or perfect execution. Right now, that is where the opportunity is hiding.
| Entity | Gains | Losses |
|---|---|---|
| EDP Renováveis | ▲Safe-haven demand | ▼Broader index weakness |
| Corticeira Amorim | ▲— | ▼Earnings miss selloff |
| BCP | ▲Rates volatility | ▼Risk-off sentiment |
| European stocks | ▲— | ▼U.S. political uncertainty |