London shares slipped at the open on Friday as a sharp selloff in US technology stocks rattled global risk sentiment just as fresh UK data pointed to weakening consumers, adding pressure on an economy already struggling for momentum.
FTSE 100 slips as UK consumers weaken
The FTSE 100 was down 0.2% at 10,708.60 in early trade, with the move reflecting a broader reassessment of risk after Wall Street’s tech-heavy Nasdaq fell sharply on worries that the artificial intelligence boom is being financed at too high a cost and with too uncertain a payoff. That matters for London not because the index is especially exposed to US megacap technology, but because a global pullback in risk assets tends to hit cyclical sectors, dampen appetite for growth shares and tighten financial conditions across markets.
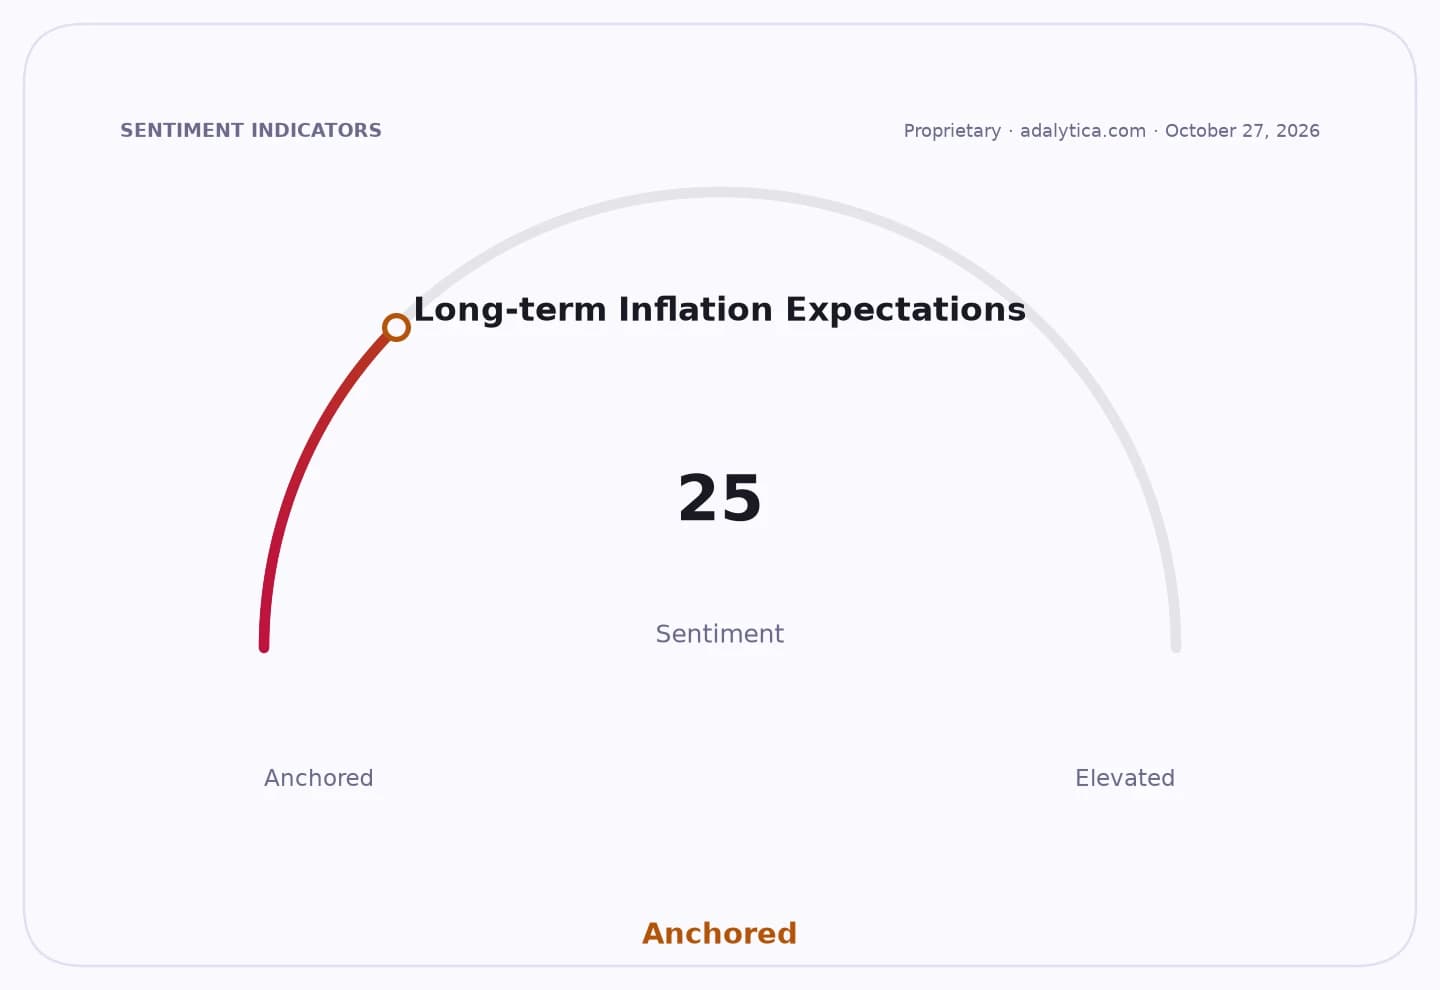
Sentiment Indicators
The immediate trigger in the US was a renewed debate over AI capital spending after Meta Platforms unveiled plans for a new class of stock to fund hundreds of billions of dollars of additional investment, while Nvidia and other chip and data-centre names slid on concern the spending race is outrunning near-term returns. The Nasdaq’s weakness fed through into European trading even though the FTSE 100 is more insulated from the technology shock than the S&P 500 or Nasdaq Composite.
Domestic data did little to lift sentiment. UK retail sales fell 0.4% in September, a steeper drop than economists had expected and a reversal from August’s 0.7% increase. While sales rose 0.7% in the three months to September from the previous quarter, the monthly decline reinforces the view that household demand remains fragile as higher living costs and elevated inflation continue to weigh on discretionary spending.
That caution was underscored by GfK’s October consumer confidence survey, which plunged 11 points to -24, the sharpest monthly fall since the Brexit vote in 2016 outside the Covid shock. The most worrying detail for retailers and the wider economy was the deterioration in intentions to make major purchases and in expectations for the broader economy, suggesting consumers are becoming more defensive just as policymakers are looking for evidence that growth can hold up.
For investors, the combination is awkward. A weaker consumer backdrop is negative for UK retailers, travel names, media groups and other domestically focused businesses that depend on discretionary demand. It also complicates the outlook for the Bank of England, which has to balance slowing growth against persistent inflation pressure, including the effects of energy and food costs. If consumer caution persists into the year-end trading period, earnings expectations for the FTSE 250’s domestic names could come under renewed pressure.
There were pockets of support in the market. Energy stocks such as BP and Shell firmed as Brent crude rose 1% to $113.32 a barrel, helped by reports that the US and Israel are planning renewed military strikes on Iran after the midterm elections. Miners also found some backing, with Anglo American rising after a Bank of America upgrade, while Rio Tinto slipped after announcing a $1.9 billion investment in its Kangwinan bauxite project in Queensland.
The broader message for markets is that London is being pulled by two different forces: imported volatility from Wall Street’s tech correction and a domestic demand picture that is weakening faster than many investors had hoped. If US growth stocks continue to de-rate and UK consumer indicators keep deteriorating, defensive and commodity-heavy areas of the FTSE may outperform, while retailers and other home-market plays remain under the most pressure.
| Entity | Gains | Losses |
|---|---|---|
| FTSE 100 defensives/energy | ▲Relative support from oil and risk aversion | ▼Limited upside from weaker growth sentiment |
| UK retailers/domestic cyclicals | ▲— | ▼Softer sales and collapsing confidence |
| Oil majors and miners | ▲Higher crude and commodity support | ▼Broader macro caution may cap gains |
| US tech/growth stocks | ▲— | ▼AI-spending scrutiny and valuation pressure |