The European Union is on course to carry about 1 trillion euros of outstanding debt by 2027, a jump that underscores how the bloc’s post-pandemic borrowing model is becoming a long-term budget burden just as auditors say spending mistakes are rising and controls are being stretched.
EU debt seen near 1 trillion euros by 2027
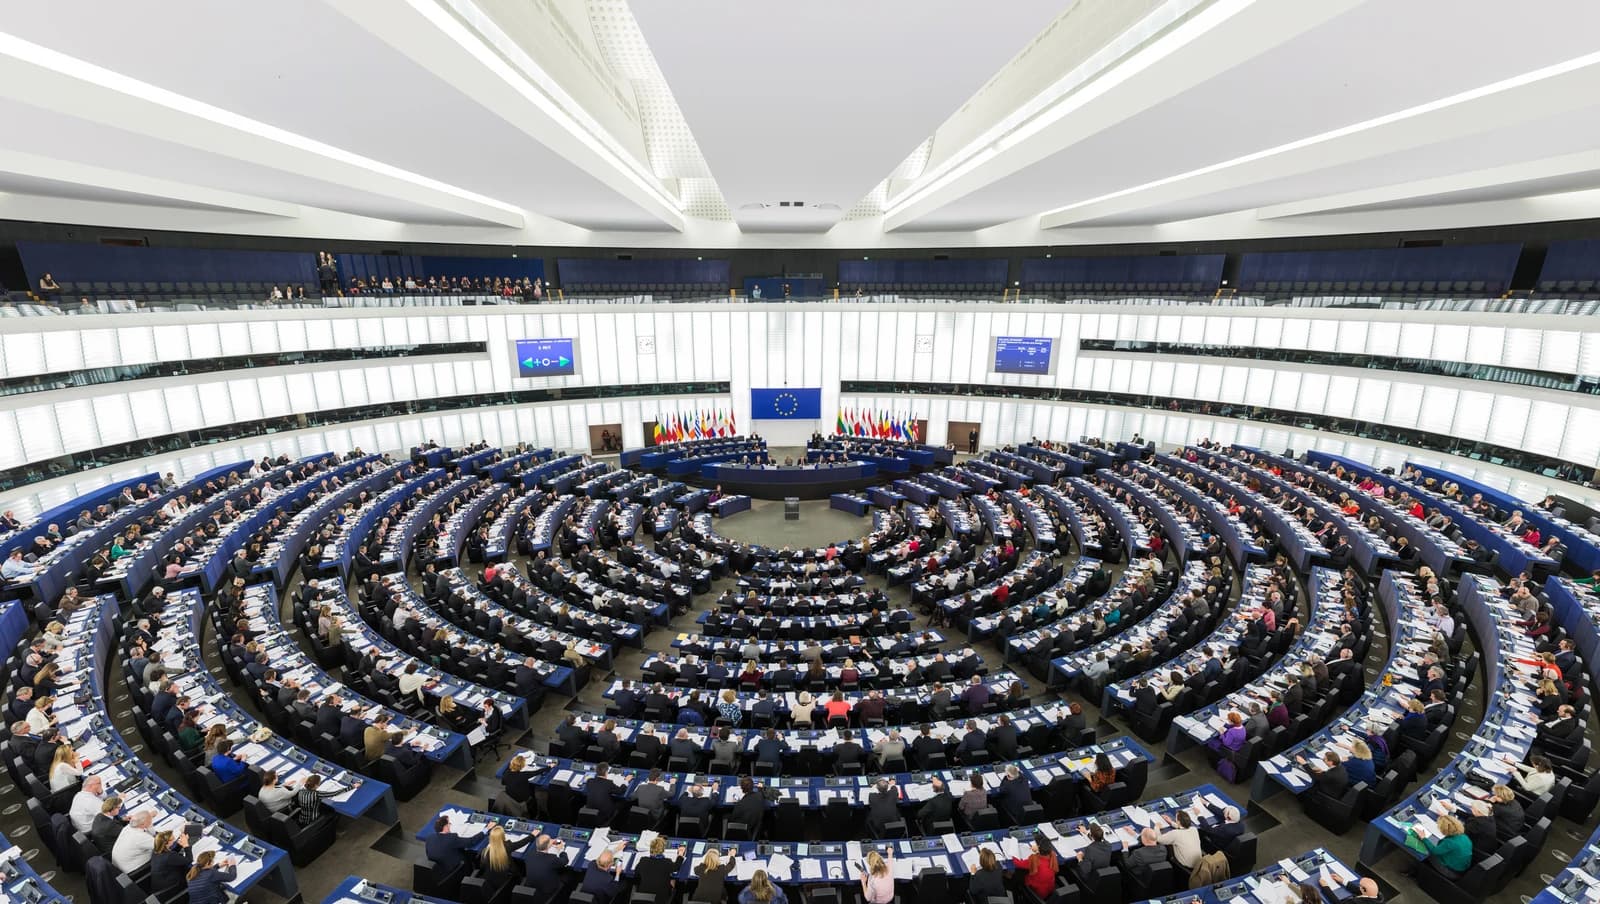
That matters because the EU is moving from crisis-era financing into a new budget cycle that would rely even more heavily on debt, national plans and performance-based payments. The warning from the European Court of Auditors lands as governments negotiate the 2028-2034 budget, where the Commission wants to preserve a large, nearly 2 trillion-euro framework while also servicing NextGenerationEU borrowings and defending cohesion and farm funding.
Sentiment IndicatorsⓘProprietary · adalytica.com · October 10, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The auditors said 3.8% of 2023 spending breached EU or national rules, up from 3.6% a year earlier and well above their 2% materiality threshold. The error rate was especially high in cohesion funds, where it rose to 6.6% from 5.7%, and in agriculture and environment spending, where it increased to 3.9% from 2.6%. While the figures do not measure fraud, the auditors still flagged 17 suspected fraud cases to authorities.
The broader concern is not just compliance. It is the scale and structure of the EU balance sheet. Outstanding borrowing rose more than 20% last year to 738.9 billion euros, and auditors said it could reach 1 trillion euros by 2027 largely because of NextGenerationEU. That debt must be repaid from 2028 to 2058, with the Commission proposing fixed annual repayments of 24 billion euros in the next long-term budget. The auditors said financing costs for the program are now expected to be twice initial estimates, with interest alone potentially reaching about 93 billion euros over seven years.
For investors, the issue is whether the EU can fund its ambitions without shifting more of the burden onto member states or cutting programs. If new own resources do not materialize, capitals may have to contribute more to service debt, a prospect that could collide with already strained public finances across Europe. France’s 10-year borrowing costs recently hit their highest since 2002, a reminder that sovereign funding stress can quickly narrow political room to maneuver.
The report also raises questions about the Commission’s favored model for future spending. Its proposed budget would channel more money through national and regional plans modeled on the pandemic recovery facility, where payments are tied to milestones rather than reimbursement of costs. But auditors found that 9 of 37 Recovery and Resilience Facility grant payments made last year did not meet all conditions, and that many milestones were softened after requests were filed. That creates a risk of payments for weaker-than-promised outcomes, even as the Commission argues its controls keep the risk low.
The political stakes are high. Net contributor countries, led by Germany and the Nordics, want major cuts to the budget proposal, while countries including Italy and Spain are pressing for more generous support for agriculture and regional spending. With a summit due in Brussels and a deal sought before the 2027 election cycle, the fight is increasingly about who pays for a more debt-heavy European state — and whether the bloc can build a credible repayment plan before the bills come due.
| Entity | Gains | Losses |
|---|---|---|
| EU member states seeking bigger budget | ▲More funding headroom | ▼Higher future contributions |
| Net contributor countries | ▲Budget restraint | ▼Larger debt service burden |
| European Commission | ▲Preserves spending model | ▼Faces scrutiny over controls |
| EU taxpayers and investors | ▲Greater transparency if reforms stick | ▼More fiscal risk if debt climbs |