European stock markets are still under pressure, and the bigger message for investors is that the region is failing to hold gains even as broader global risk sentiment remains fragile. The weakness in Europe-focused ETFs such as VGK, FEZ and IEV suggests this is not just a one-day pullback but a market that is struggling to reclaim momentum after a sharp summer run.
Europe ETFs VGK FEZ IEV lose momentum

That matters because Europe is highly sensitive to shifts in global growth, currency moves and U.S. risk appetite. When European equities can’t sustain rallies, it usually reflects a market that is pricing in slower earnings growth, tighter financial conditions or renewed caution around cyclicals and exporters. For asset allocators, that keeps Europe in the “selective, not broad beta” bucket.
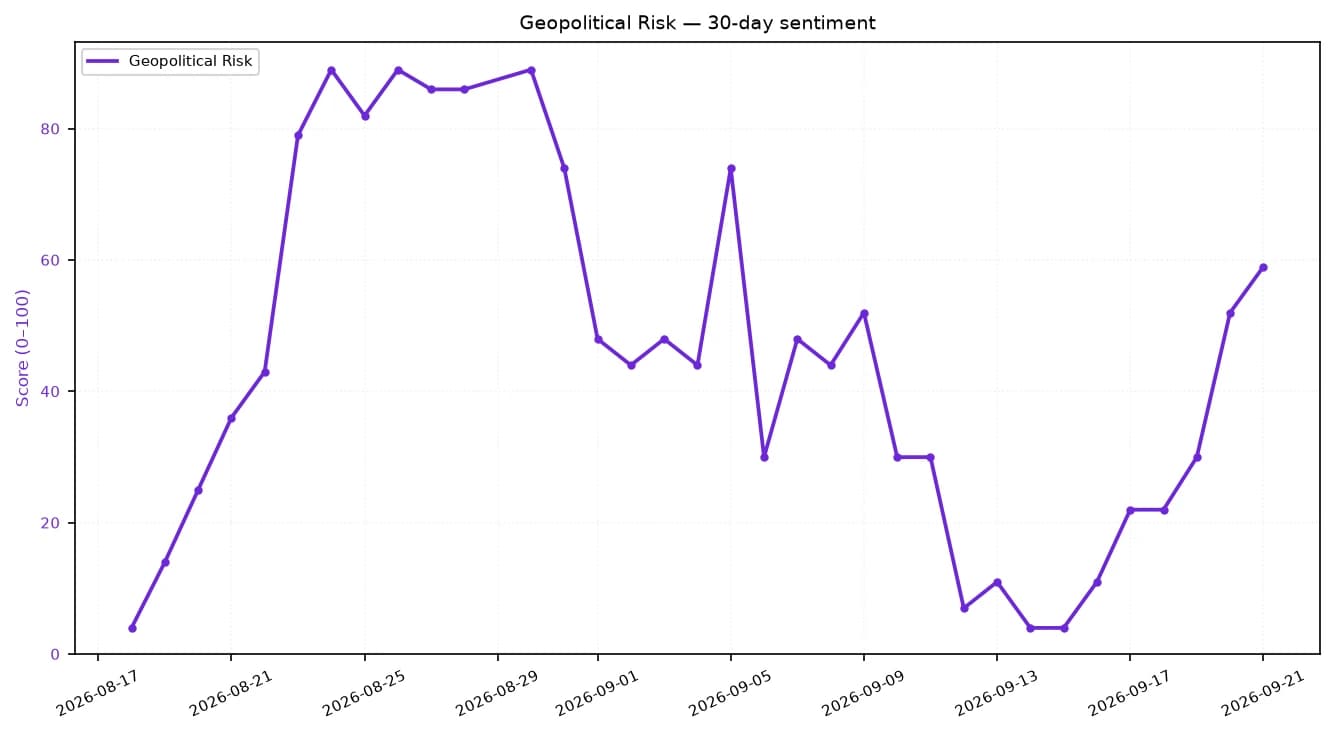
Sentiment IndicatorsⓘProprietary · adalytica.com · September 1, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The technical picture confirms the hesitation. VGK closed at 91.66 on Aug. 31, below its recent peak near 92.70 and only modestly above its 50-day moving average around 90.00, after having traded much higher earlier in the summer. FEZ finished at 70.84, just above its 50-day average of 69.49, while IEV closed at 74.95 versus a 50-day average of 73.82. In other words, Europe is not breaking down hard, but it is no longer in a clean uptrend either.
That is where investors should focus. The market is not rewarding complacency, and that opens the door for stock pickers rather than index buyers. If European equities remain negative, the winners are likely to be companies with pricing power, dollar-linked earnings, strong balance sheets and exposure to defense, infrastructure and industrial capex — not the broad market basket that depends on a smooth macro recovery.
There is also a cross-asset warning sign in the broader mood. Adalytica’s S&P 500 trade signals show “Extreme Fear” on awareness even though sentiment is neutral, a reminder that risk appetite can sour quickly even without a major headline shock. In that environment, investors tend to rotate away from regions with weaker relative momentum and into the most defensive or most strategically supported sectors.
The investable thesis is straightforward: Europe remains a market to trade, not to blindly own. I believe the asymmetric opportunity is in the second-order beneficiaries — defense names, utilities tied to grid buildout, industrials with backlog visibility, and selective exporters that can weather a soft domestic backdrop. Broad Europe ETFs may keep lagging until macro clarity improves, but that creates a setup where quality names can outperform even if the index stays trapped.
For now, the takeaway is to stay underweight the weakest parts of European beta and overweight the pockets where capital spending, security spending and restructuring can still produce earnings growth. If Europe remains negative, that is not a reason to avoid the region entirely — it is a reason to own the right businesses before the market catches up.
| Entity | Gains | Losses |
|---|---|---|
| Defensive/quality European stocks | ▲Relative outperformance | ▼Less upside in broad rallies |
| Broad Europe ETFs (VGK, FEZ, IEV) | ▲Tactical trading opportunities | ▼Momentum and inflows |
| Defense, infrastructure, industrial capex names | ▲Secular demand tailwinds | ▼Cyclical laggards |
| Portfolio hedgers/short sellers | ▲Better entry points | ▼Short squeezes if risk sentiment improves |