European stocks fell on Monday as weekend riots in France and rising political risk in Spain revived fears that the region’s most fragile markets are becoming harder to own, even as investors wait for a heavy week of earnings from both sides of the Atlantic.
European stocks fall as France unrest hits banks
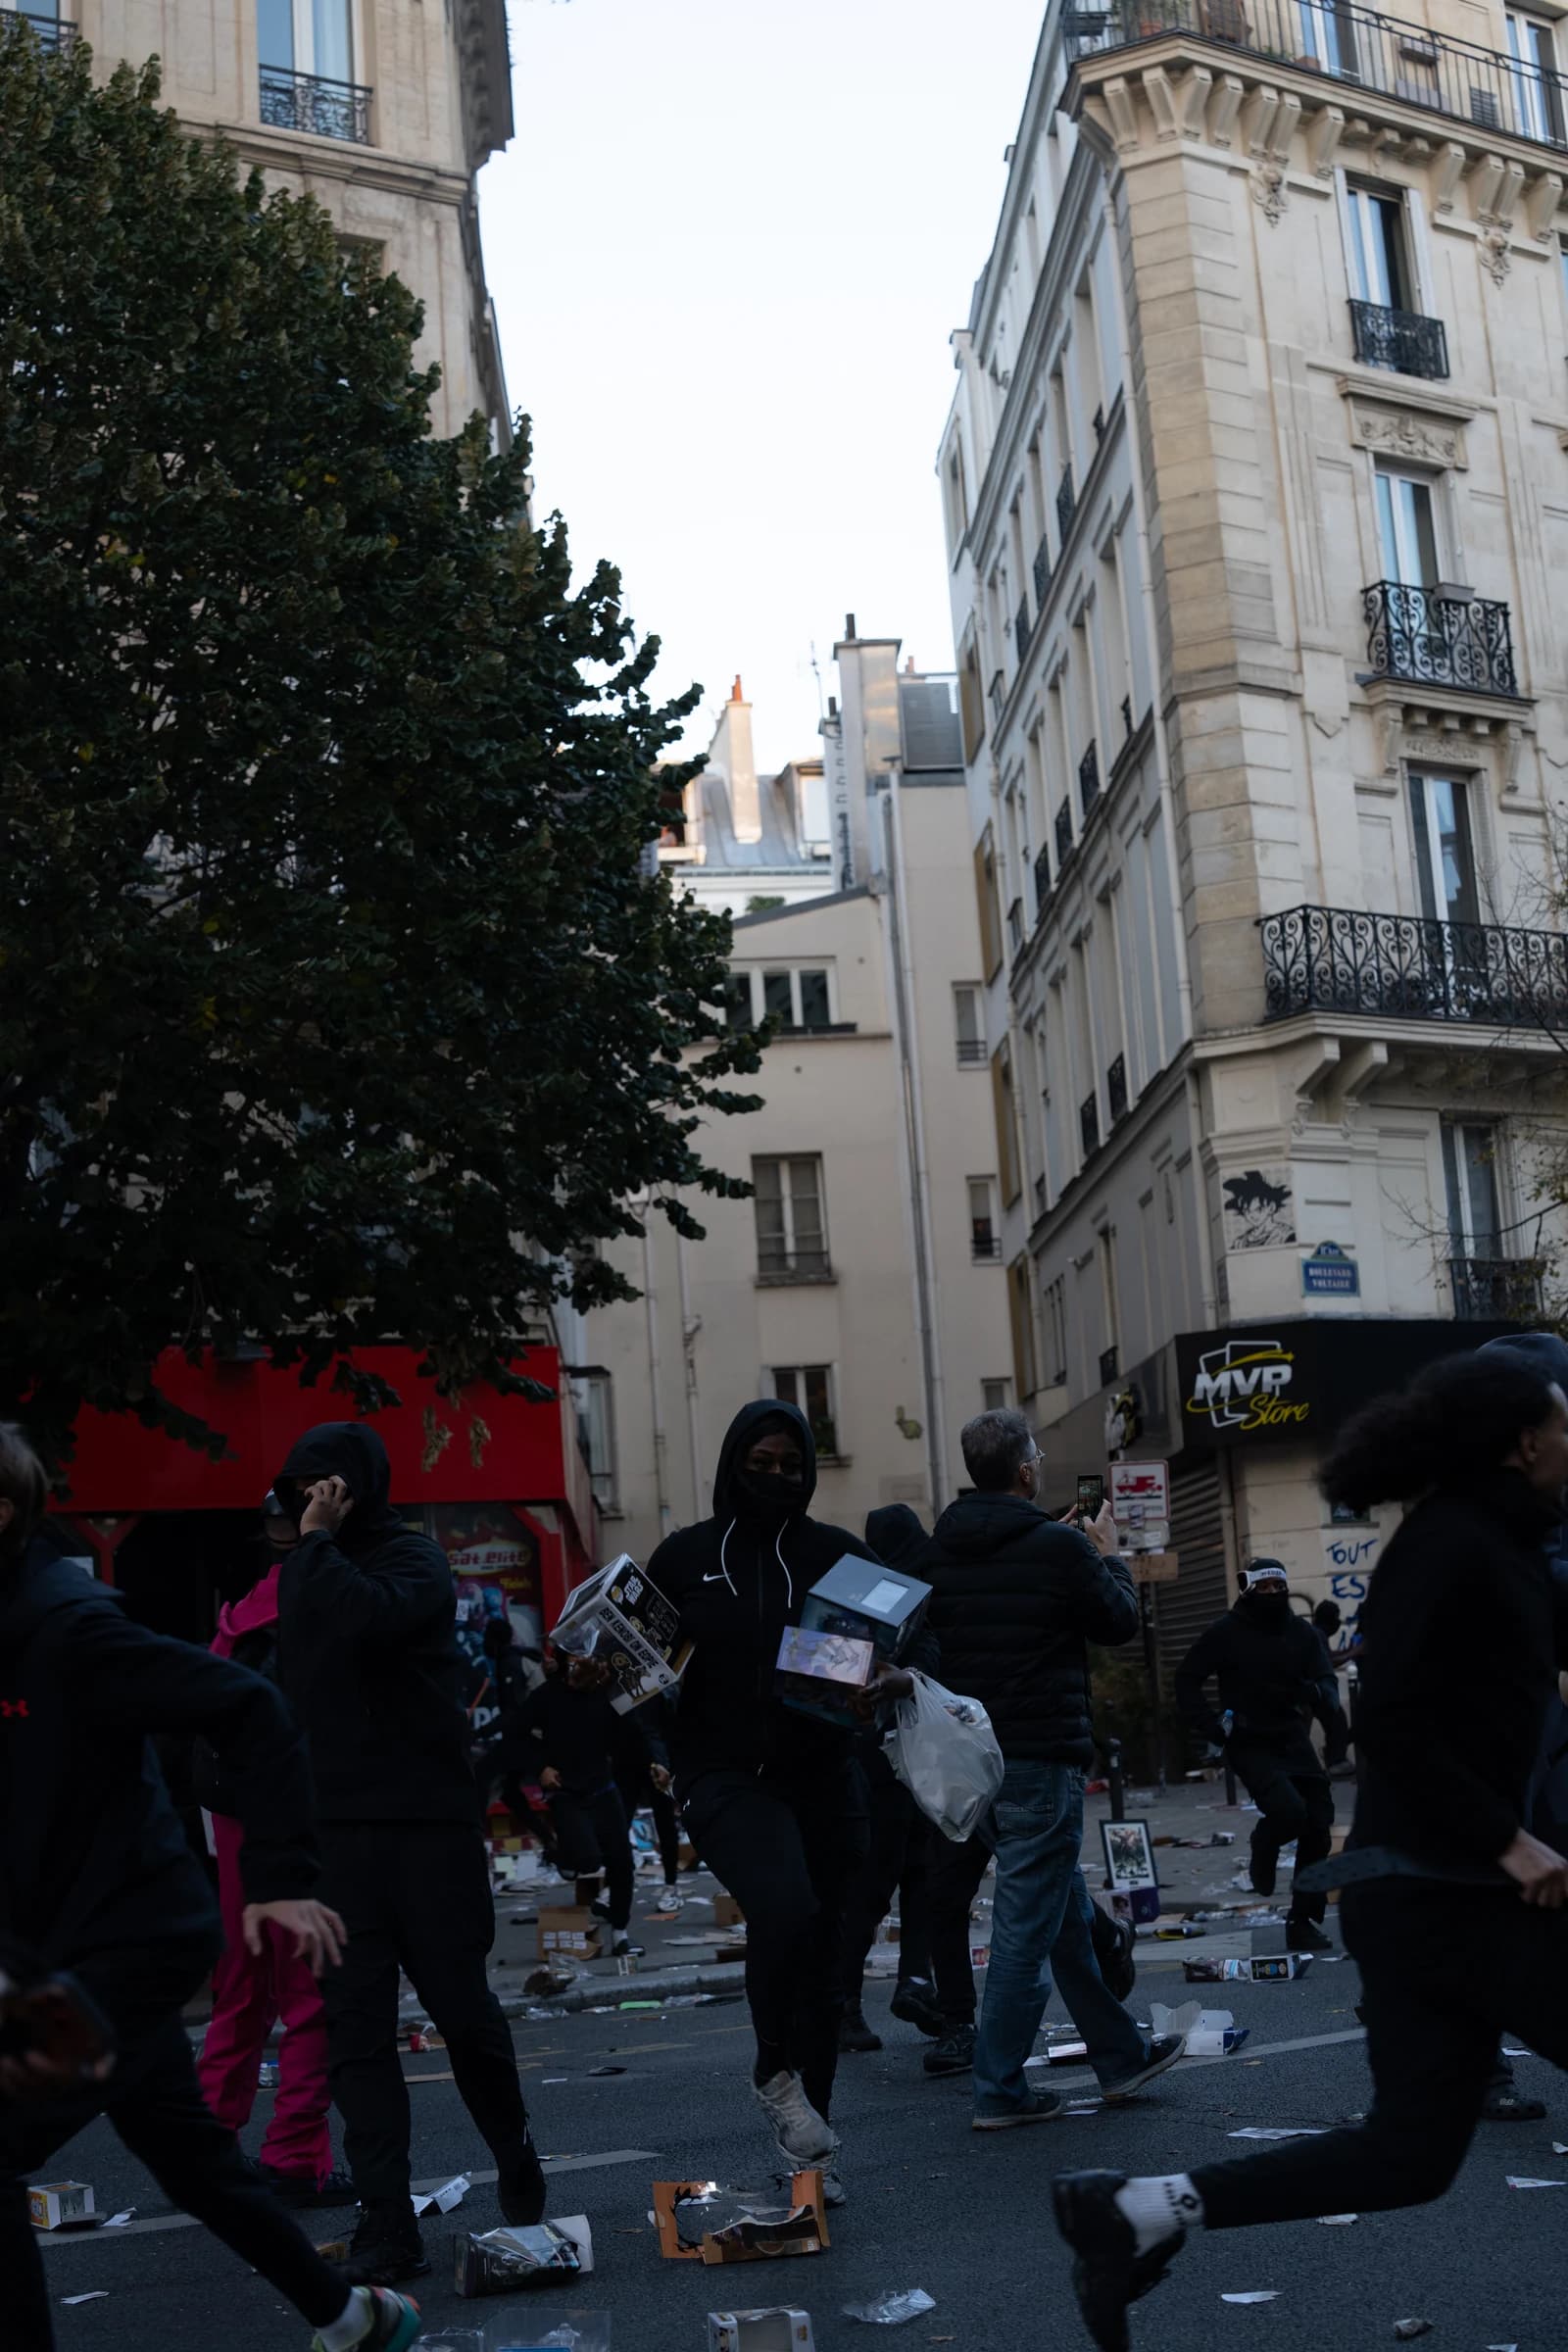
The STOXX 600 closed down 0.80%, while France’s CAC 40 lost 1.11% and Spain’s benchmark slid 1.5% as unrest and election uncertainty weighed on sentiment. For investors, the key issue is not just a one-day pullback: France is the euro zone’s second-largest economy, and any sustained erosion in confidence there can feed into borrowing costs, curb risk appetite and pressure domestically focused sectors across Europe.
Sentiment IndicatorsⓘProprietary · adalytica.com · October 24, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
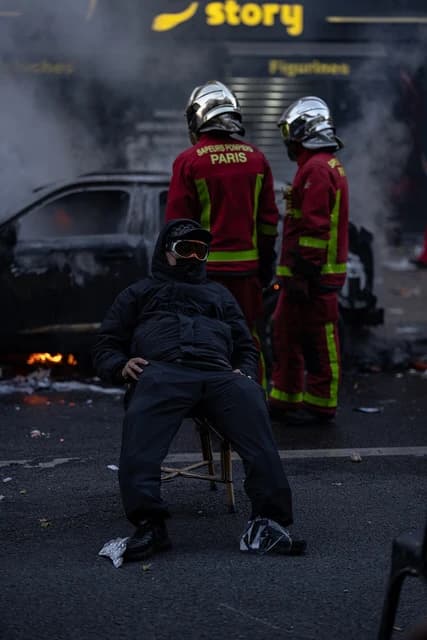
French banks were among the hardest hit, with BNP Paribas, Societe Generale and Credit Agricole falling between 2.5% and 3.4%. Retail and property-linked names also weakened, with Carrefour down 2.2% and Unibail-Rodamco-Westfield off 2%. That matters because these are exactly the kinds of stocks most exposed to consumer confidence, traffic, credit demand and the health of the French economy. When politics turns noisy, their earnings multiples tend to compress first.
The weakness spread beyond France. Germany’s DAX and London’s FTSE 100 both fell more than 1%, while cyclical shares led the decline across Europe. Banks were the worst-performing sector, dropping 2.2%, and defence stocks also lost 1.5%. The only major group in positive territory was technology, up 0.7%, underscoring how selective investors are becoming as they rotate toward earnings visibility and away from politically sensitive beta.
The narrative here is simple: Europe is entering a period where domestic political risk is starting to matter more than the macro data that had steadied markets earlier in the year. France has already been dealing with weak growth and rising debt, and fresh unrest raises the odds of policy paralysis ahead of the 2027 presidential election. Spain adds another layer of uncertainty, with investors watching how an early vote next month could complicate coalition building and fiscal reform.
That is why this pullback should be read as more than headline noise. It reinforces the case for owning balance-sheet strength and global revenue exposure over pure domestic cyclicals. It also keeps pressure on European risk assets at a moment when markets are already jittery over AI-related valuation debates in the U.S. and a packed earnings calendar that could reset expectations again.
For investors, the opportunity is in separating the countries and sectors with policy stability and earnings resilience from those exposed to political churn. Until the streets calm and the election calendar looks less threatening, French banks, retailers and other domestic plays are likely to trade with a risk premium. The better trade remains selective exposure to Europe’s exporters, software and quality compounders rather than broad index beta.
| Entity | Gains | Losses |
|---|---|---|
| European exporters | ▲Relative safe haven | ▼Lower index beta |
| French banks | ▲— | ▼Political risk premium |
| French retailers/property names | ▲— | ▼Consumer confidence hit |
| Select tech stocks | ▲Rotation inflows | ▼Broader cyclical selling |