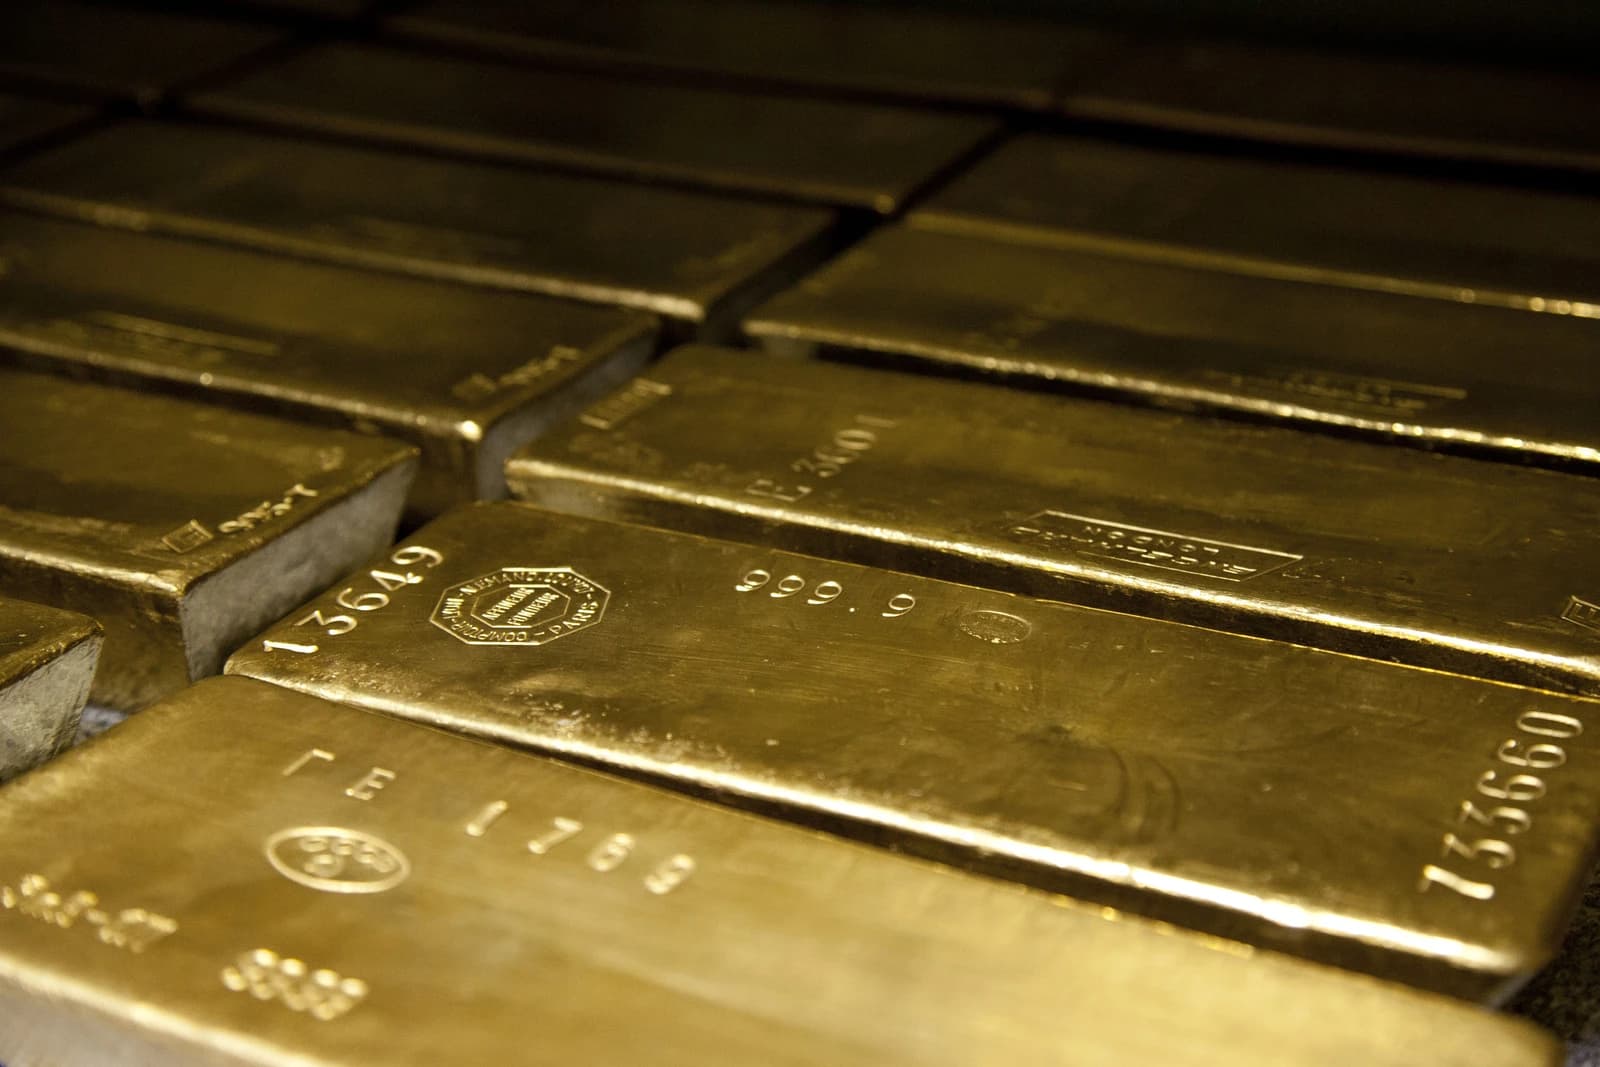
Flowra and Korea Gold Exchange Digital Asset are exploring a structure that would use gold-backed digital assets as collateral to help secure SOL for Solana validators, a move that could widen the use case for tokenized gold beyond trading and storage and channel new capital into blockchain infrastructure.
Flowra and KorDA Explore Gold-Backed SOL Staking

The proposed arrangement remains only at memorandum-of-understanding stage, but it highlights an emerging theme in digital assets: real-world collateral being folded into network operations rather than sitting passively onchain. If developed, the Flowra-KorDA Delegation Program would link KGLD, a gold-backed asset managed by KorDA or an affiliate, to the acquisition and delegation of SOL, creating a pipeline from precious-metals tokenization to staking and validator economics.
Sentiment IndicatorsⓘProprietary · adalytica.com · September 4, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
That matters economically because validator infrastructure depends on dependable access to capital, while tokenized gold has been searching for higher-value utility. Using a gold-backed instrument as collateral could, in theory, reduce funding friction for SOL holders or delegation programs and improve the economics of validator participation. It also offers a way to mobilize balance-sheet-like assets without forcing outright sales of gold exposure.
For Solana, the proposal comes at a time when the token is trading above both its 50-day and 200-day moving averages, with RSI readings in the high 60s, suggesting the market has recovered from earlier weakness but is not yet in an overheated state. Gold has also been strong, with Comex futures near $4,527 and GLD above $400, though Adalytica’s gold fear-and-greed gauge sits at extreme fear, underscoring that the metal’s rally has been accompanied by elevated caution rather than broad conviction.
The market relevance is less about immediate price impact than about the institutionalization of Solana’s staking economy. Flowra would supply the infrastructure, including its order-flow and block-engine tools, while KorDA would handle validator operations, key management and monitoring. That division of labor suggests the companies are trying to build a commercially viable framework for delegation, rewards distribution and validator selection, not just a marketing partnership.
For investors, the bull case is that tokenized assets with hard-asset backing could become a new source of demand for staking ecosystems, tightening the link between real-world asset tokenization and crypto network utility. The bear case is that the model may never move beyond a pilot if custody, regulatory and counterparty issues prove too complex. The companies have already said any use of KGLD as collateral remains subject to legal review, due diligence and separate definitive agreements, and Flowra would not custody the collateral.
The longer-term significance is that Solana’s infrastructure economy may become a testing ground for how traditional collateral and blockchain yield generation intersect. If Flowra and KorDA can clear regulatory hurdles, the program could become a template for other asset-backed delegation structures. If not, it will serve as another reminder that turning tokenized assets into productive capital is far easier in concept than in execution.
| Entity | Gains | Losses |
|---|---|---|
| Flowra | ▲New infrastructure demand | ▼Regulatory and execution risk |
| KorDA | ▲Expanded KGLD utility | ▼Operational complexity |
| SOL holders / validators | ▲Potential new collateral flow | ▼Dependence on program launch |
| Competing staking models | ▲None | ▼Possible loss of capital attention |