Generali’s creditworthiness has become the key variable for holders of a note linked to the Italian insurer, as the product’s payout now depends on whether a credit event ever hits the reference borrower.
Generali Credit Note Trades Near 35.33
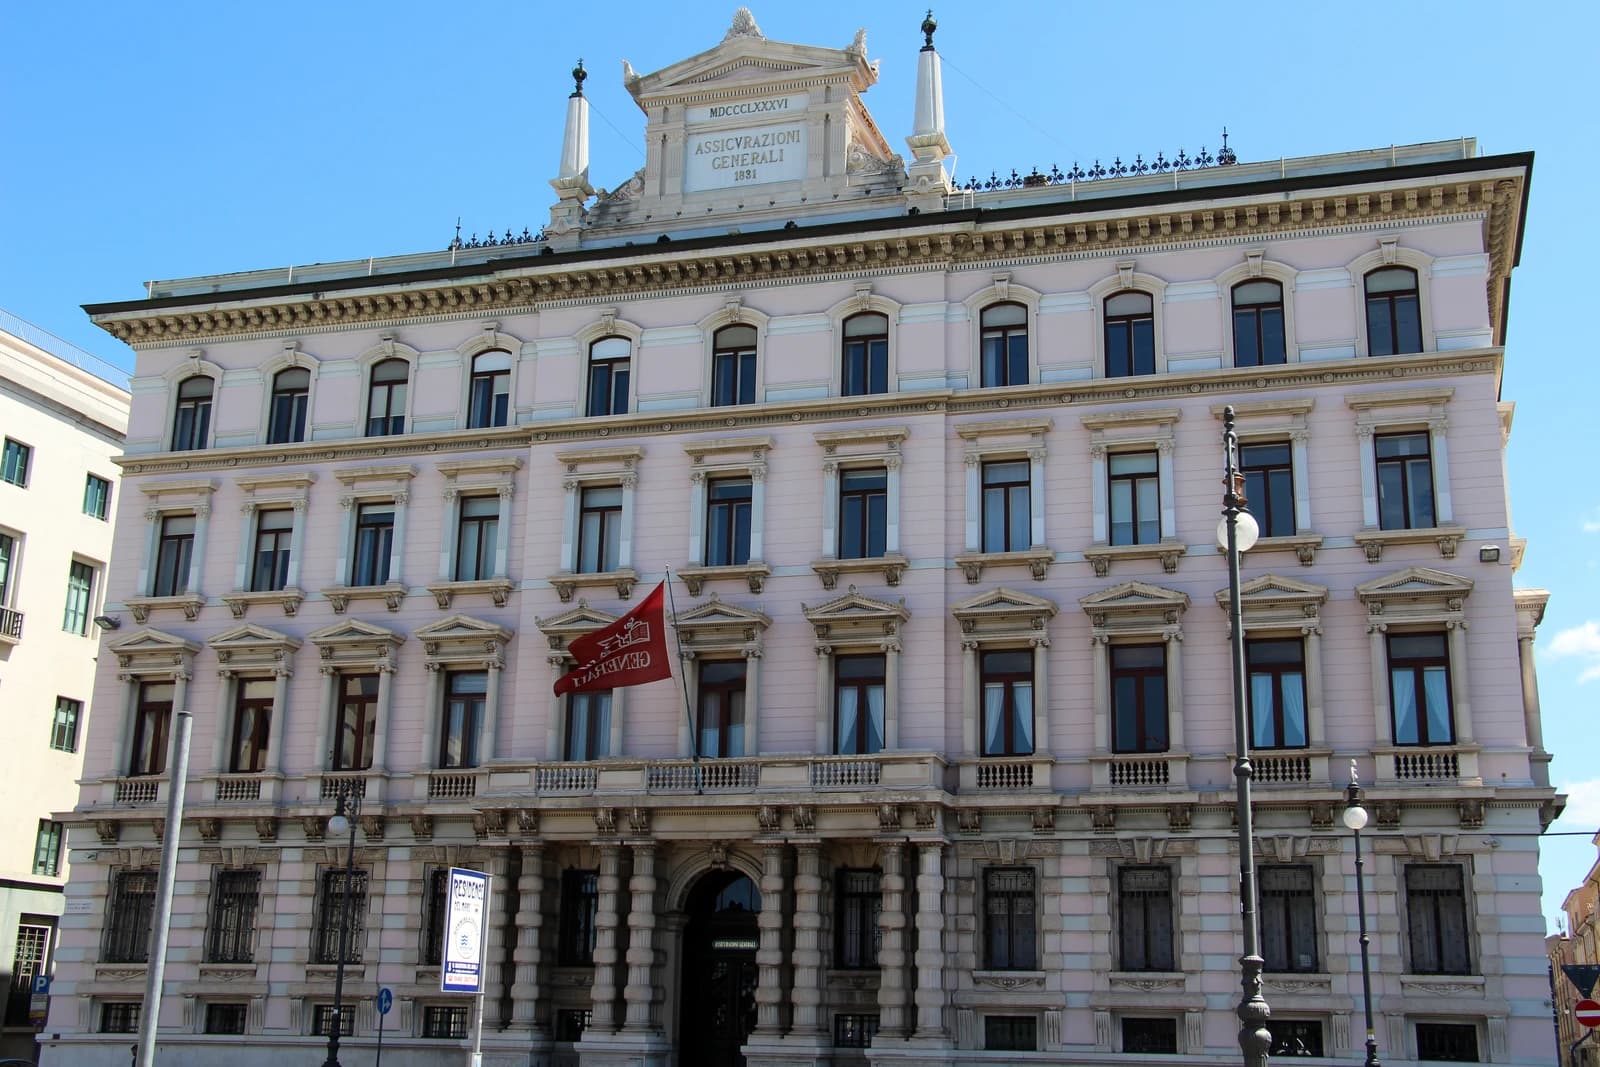
That matters because this kind of bond-like structure turns ordinary market anxiety into a direct capital risk for investors. If Generali were to miss a payment, enter insolvency or restructure debt, future coupons would stop and the certificate would be redeemed early at the prevailing market price. In other words, the instrument offers income only as long as the market keeps trusting Generali’s balance sheet.
The note is still quoted around 35.33, not far from its 50-day moving average of 35.01, after swinging between 34.32 and 35.78 on Tuesday. Relative-strength readings at 62.5 suggest momentum has improved from the deeply oversold levels seen earlier this year, while the MACD has inched back toward neutral territory. For investors, that kind of price action usually says less about excitement and more about uncertainty: the market is watching credit, not just yield.
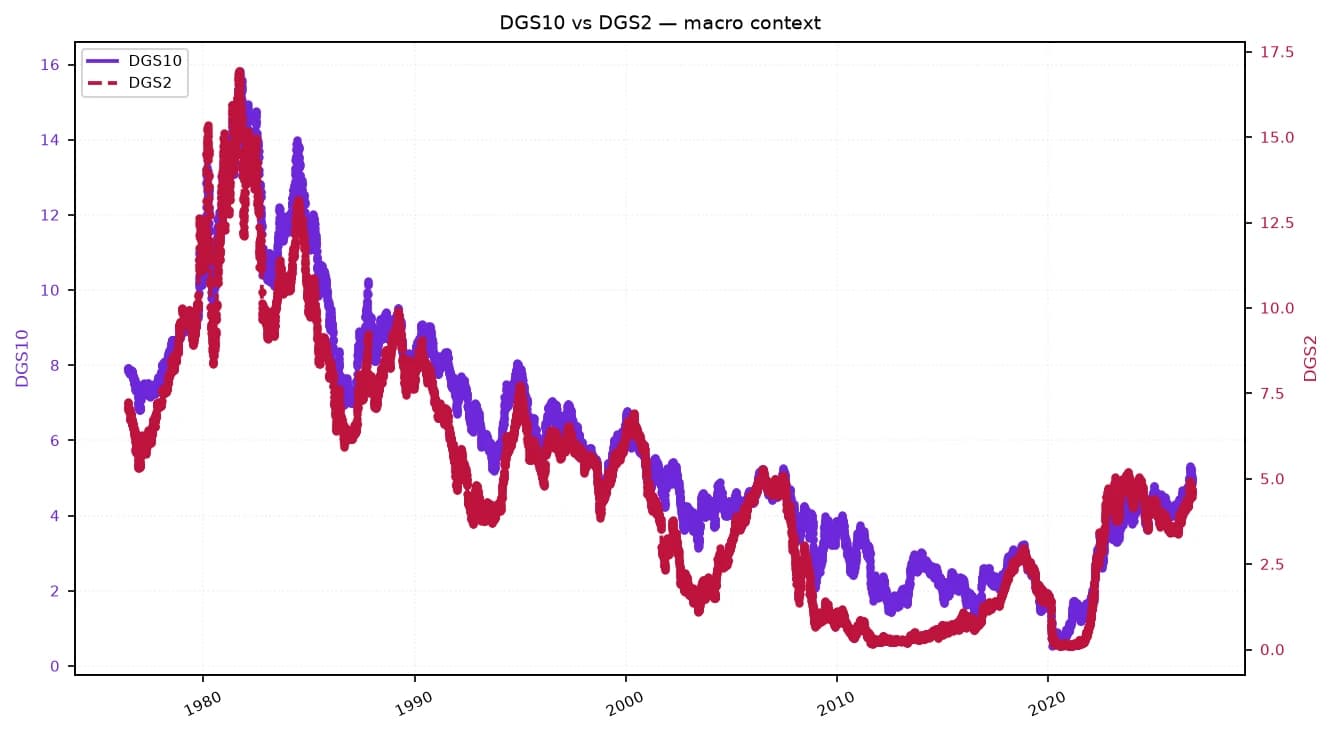
That fits a wider bond market backdrop in which investors have grown more selective. Mortgage bond funds in the U.S. have seen one of their largest outflows since 2021 as changing Treasury yields and hedging pressure jolt fixed income markets. When rates and credit spreads move around this much, structured products tied to a single reference name become harder to value and easier to shun.
For long-term investors, the lesson is straightforward. Credit-linked notes can look attractive when coupon income is hard to find, but the return is only as good as the issuer’s credit profile. Generali remains a major insurer, not a distressed borrower, yet this product reminds investors that even familiar names can carry hidden downside if the bond market turns sour. It is worth watching, but only for investors who understand the credit risk they are being paid to take.
| Entity | Gains | Losses |
|---|---|---|
| Investors seeking income | ▲Higher coupon potential | ▼Credit-event risk |
| Generali | ▲Access to funding demand | ▼Scrutiny over creditworthiness |
| Note holders | ▲Exposure to bond-linked yield | ▼Early redemption at market price |
| Fixed-income traders | ▲Trading opportunity | ▼More volatility and hedging costs |