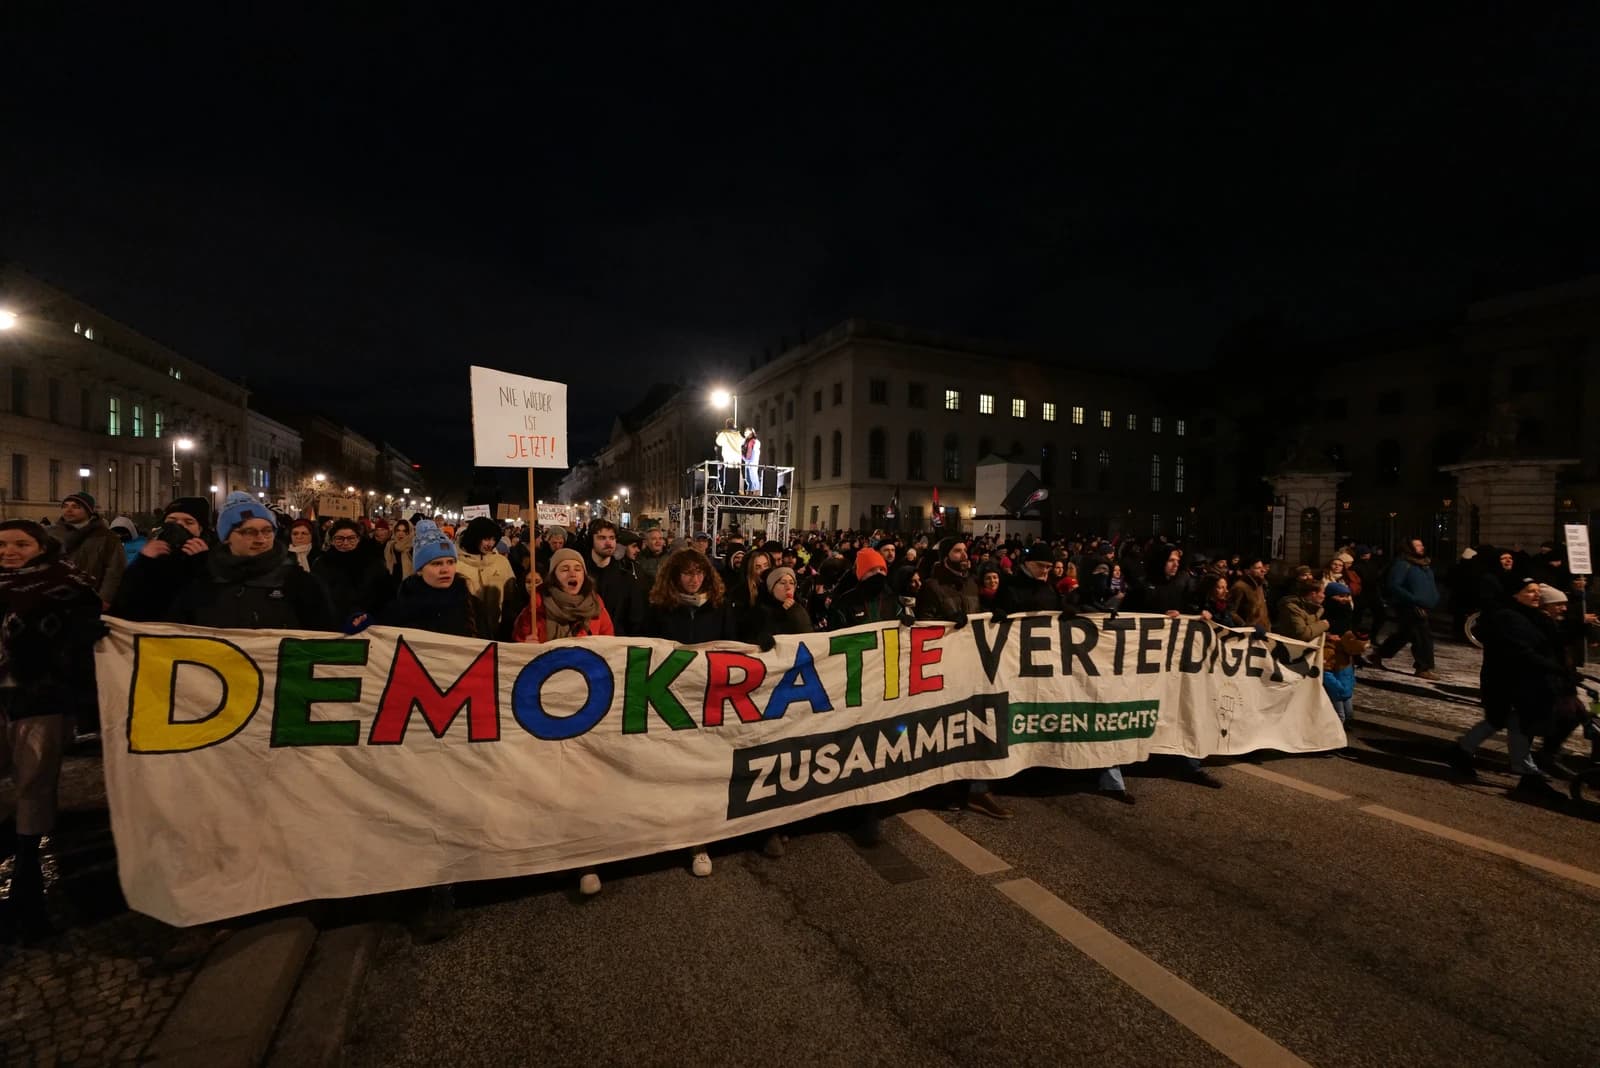
Germany’s latest vote is a warning that Europe’s far-right is still gaining political gravity, but the bigger message for investors is that the advance is uneven, contested and highly marketable around the edges rather than a clean, continent-wide takeover.
Germany vote lifts far-right Europe trade themes

That distinction matters because the rise of nationalist and anti-immigration parties is now shaping everything from migration policy and EU coalition math to fiscal priorities, defense spending and relations with Russia, China and the United States. But the path is not linear: while the Alternative for Germany won its first state election victory and far-right parties have gained influence in parts of Italy, Finland, Croatia and Slovakia, other populist leaders have stumbled, softened or been forced into compromise once in office.
Sentiment IndicatorsⓘProprietary · adalytica.com · September 8, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse

For markets, that means the real trade is not a simple “Europe turns far-right” thesis. It is a more fragmented, more tactical rotation into beneficiaries of political volatility: border-security spending, defense, domestic policing, energy security, industrial reshoring and infrastructure tied to strategic autonomy. Investors betting on a sweeping policy regime change should remember that some of the loudest nationalist brands have already moderated in power, with Italy’s Giorgia Meloni winning praise for a more centrist governing style, while Hungary’s Viktor Orbán and Britain’s Reform UK have both faced setbacks.
The German result still matters because it reinforces the pressure on mainstream parties to move right on migration, law and order and industrial policy. That dynamic is already visible in Brussels, where the center-right European People’s Party has increasingly worked with the far-right, helping drive a historic migration overhaul that would have been politically unthinkable a few years ago. Once the center normalizes those alliances, the policy mix can shift faster than headline election results suggest.
That is why the next set of elections in France and Spain matters so much. France remains the biggest single upside catalyst for the far-right, with Marine Le Pen still a front-runner to succeed Emmanuel Macron, while Spain’s Vox has been building local governing leverage despite holding only 32 of 350 seats in parliament. If either country moves further right, the market implications would extend well beyond rhetoric: tighter immigration policy, tougher EU bargaining, less fiscal orthodoxy and a deeper push for security self-sufficiency.
The euro and Europe equity investors are already being forced to price that tension, not as a one-way political collapse, but as a rolling series of country-specific shocks. Germany’s political shift is a reminder that the anti-far-right firewall is weakening, yet the reversals in Hungary, the Netherlands and Britain show that populism still faces real resistance, especially when it has to govern rather than campaign.
For investors, the asymmetric opportunity lies in treating Europe’s far-right rise as a volatility engine, not a binary outcome. That favors selective exposure to defense, border control, cyber security, energy infrastructure and domestic industrial names that benefit from a more fragmented Europe and a more defensive policy posture. The market is still underestimating how much capital will follow politics into those themes over the next 12 to 24 months.
| Entity | Gains | Losses |
|---|---|---|
| Far-right parties | ▲More seats, leverage | ▼Coalition constraints |
| Mainstream conservatives | ▲Policy influence via deals | ▼Centrist credibility |
| Defense and security stocks | ▲Higher spending tailwind | ▼Noneconomic volatility |
| Immigration-sensitive incumbents | ▲Harder policy debate | ▼Voter backlash |