Ghana’s central bank pumped almost $13 billion into the foreign-exchange market over the past year to steady the cedi, underscoring how heavily policymakers have leaned on reserves to cushion the currency from dollar strength and domestic demand for hard currency.
Ghana central bank spent $13 billion supporting cedi
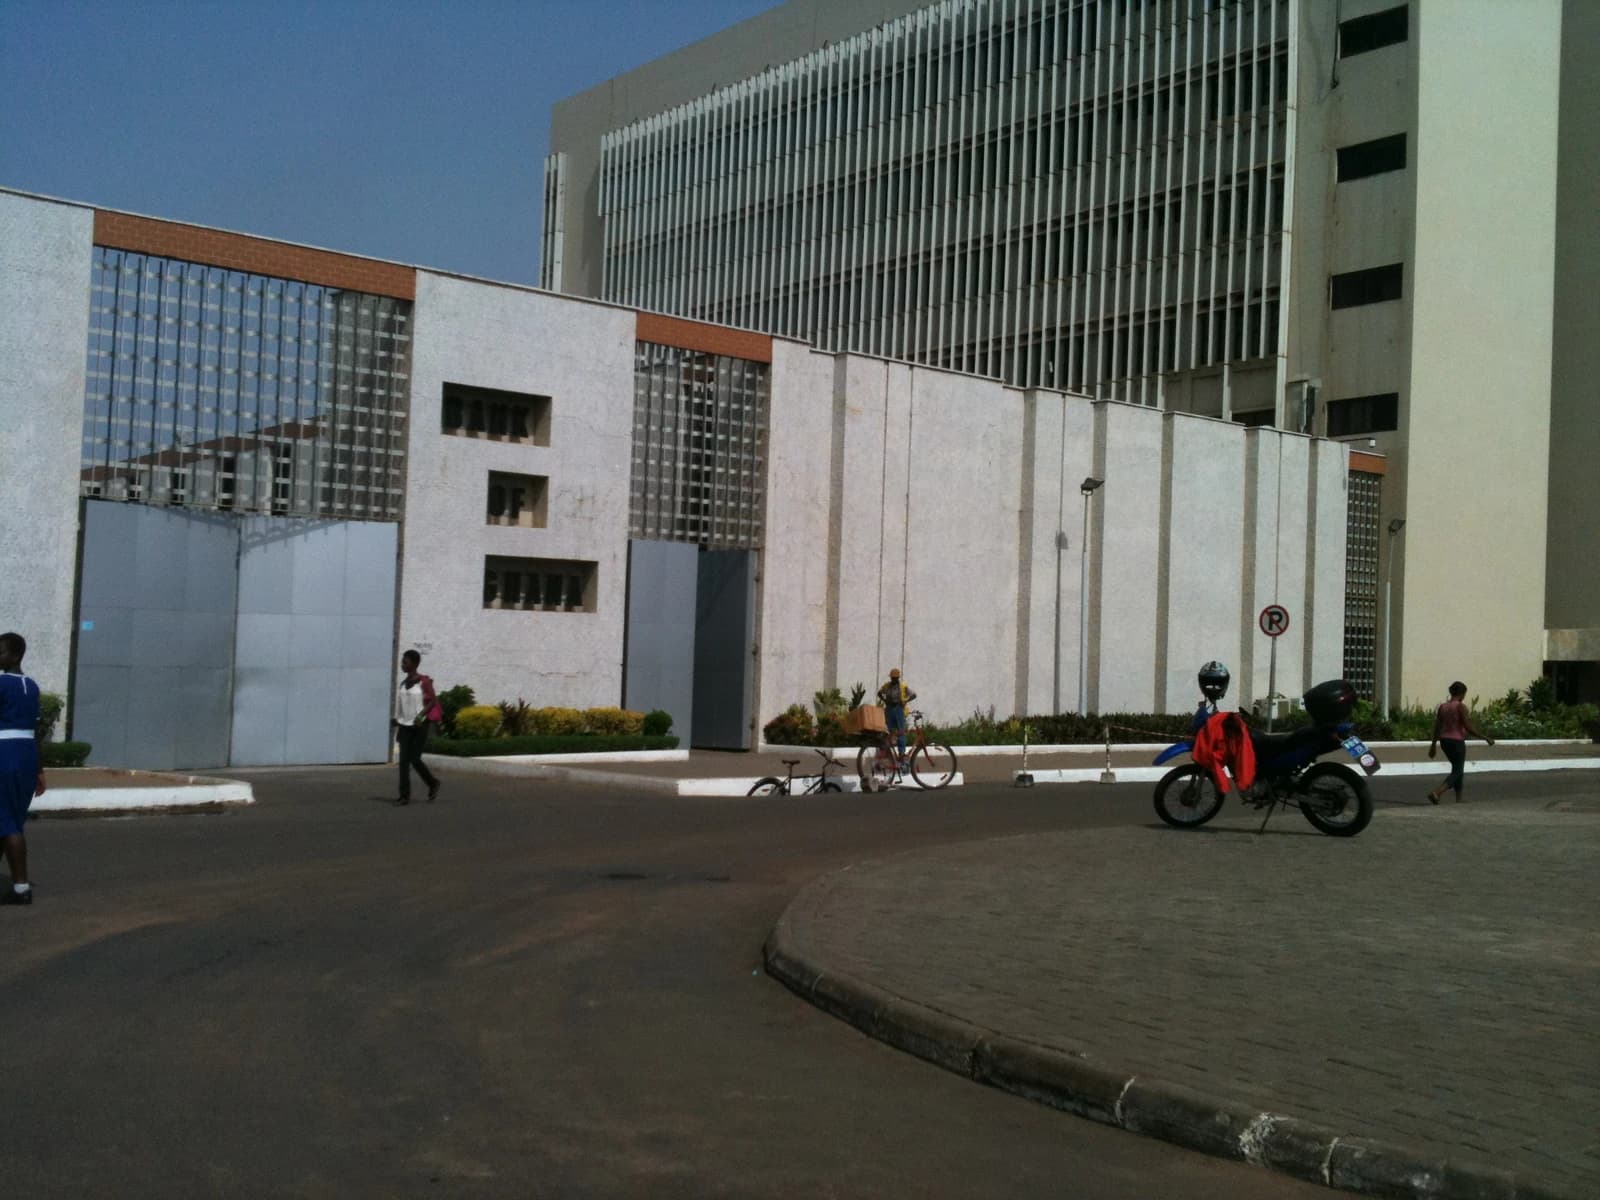
The scale of intervention matters because it can buy time for inflation to ease and import costs to stabilize, but it also highlights the cost of defending a currency in a thin market. For investors, the question is whether the Bank of Ghana is managing a temporary squeeze or burning through ammunition to delay a more durable adjustment.
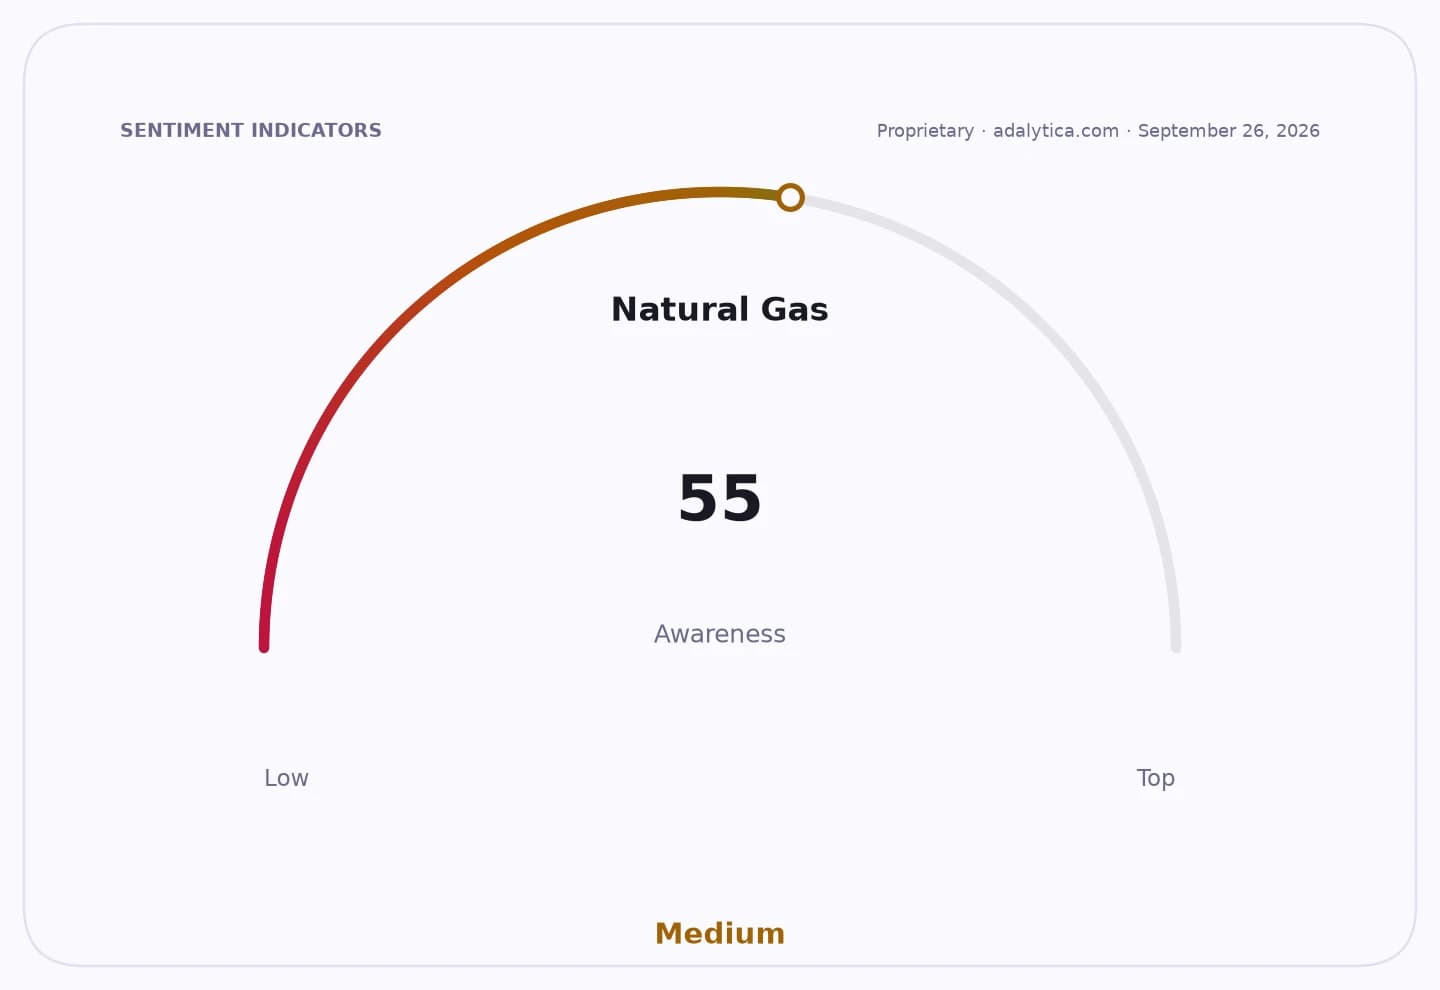
Sentiment IndicatorsⓘProprietary · adalytica.com · August 12, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The cedi has remained under pressure even as the US dollar has softened globally in recent weeks. The dollar slipped against major peers after weak US employment data, with the euro trading above $1.15 and the yen touching a three-month high near 158 per dollar, but that broad move has not removed the strain on African and emerging-market currencies that still face local liquidity and balance-of-payments pressures.
In Ghana, the intervention reflects the central bank’s determination to prevent sharp swings that would feed through to fuel, food and imported goods. That is especially important in an economy where imported inputs remain critical for businesses and where exchange-rate volatility can quickly hit consumer prices and corporate margins.
Market watchers will read the intervention as both support and warning. Heavy FX sales can calm the market in the short term, but they also raise questions about reserve preservation, policy credibility and how long the bank can keep smoothing the currency if external inflows do not strengthen.
Technical trading patterns also point to a fragile stabilization rather than a decisive turn. USD/GHS has been hovering near its 50-day moving average, while the latest readings showed momentum easing after a recent run-up in the pair, suggesting the cedi is still being managed more than naturally supported.
The next catalyst is whether Ghana can reduce pressure through stronger export receipts, improved foreign inflows and tighter monetary coordination, or whether the central bank will need to keep intervening at a similar pace to prevent another leg of weakness.
| Entity | Gains | Losses |
|---|---|---|
| Bank of Ghana | ▲Short-term cedi stability | ▼Foreign reserves |
| Ghana importers | ▲Lower near-term FX volatility | ▼Higher policy uncertainty |
| Ghana consumers | ▲Slower pass-through to prices | ▼Inflation if cedi weakens again |
| FX speculators | ▲Trading volatility | ▼Upside if intervention holds |