Gold prices extended their slide on Nov. 19, with domestic bars and rings across major Vietnamese brands falling sharply as global bullion sank to a 14-month low near $3,726 an ounce.
Gold Falls to 14-Month Low on Strong Dollar
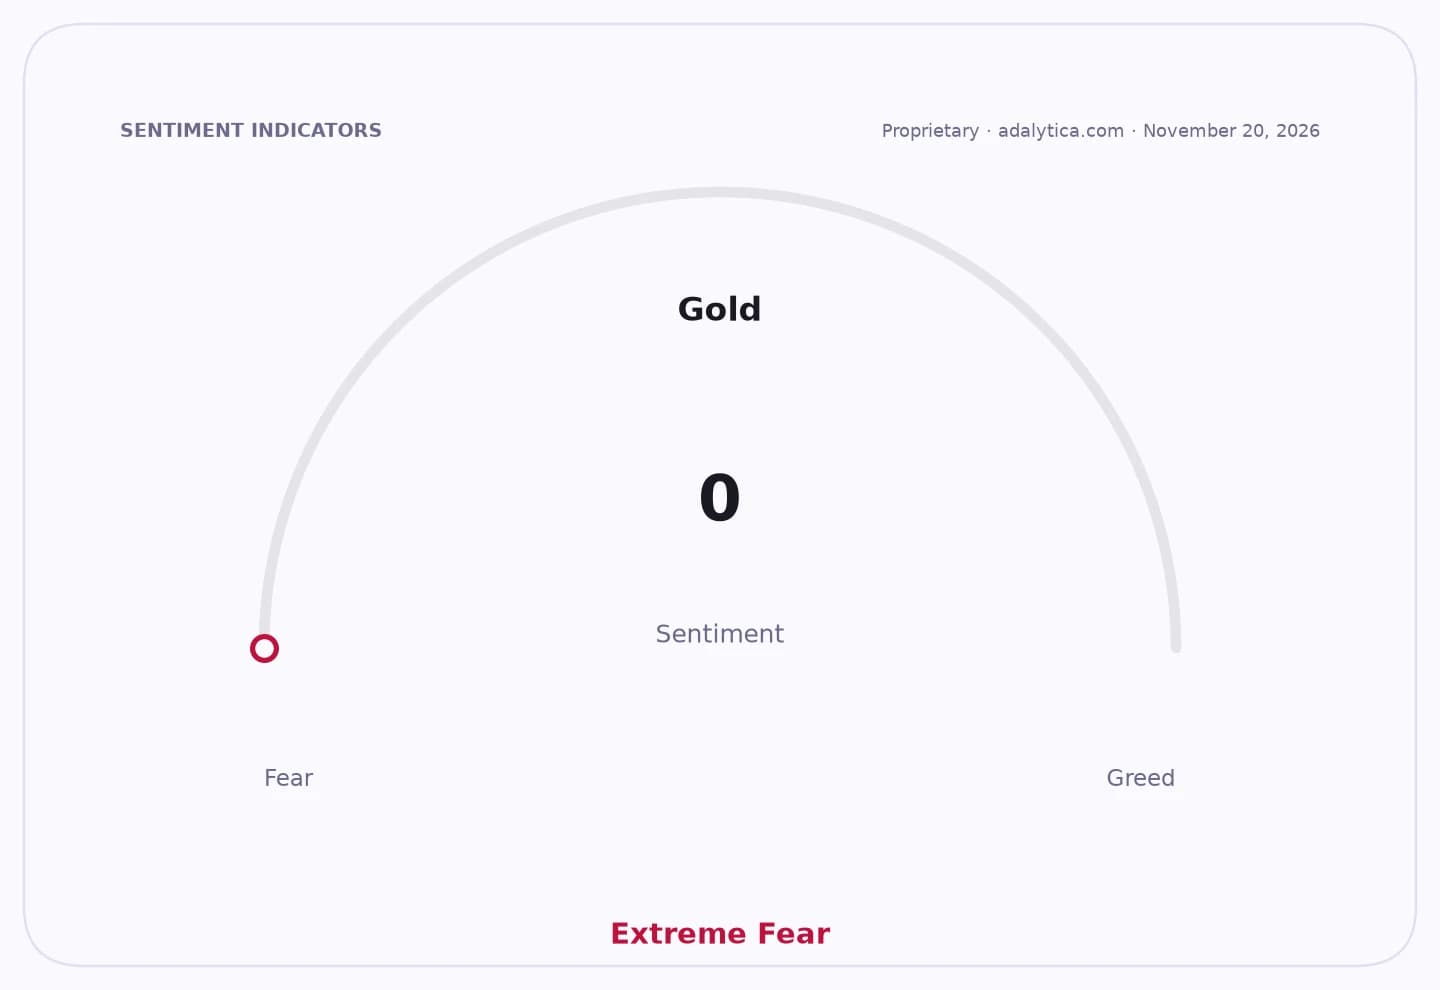
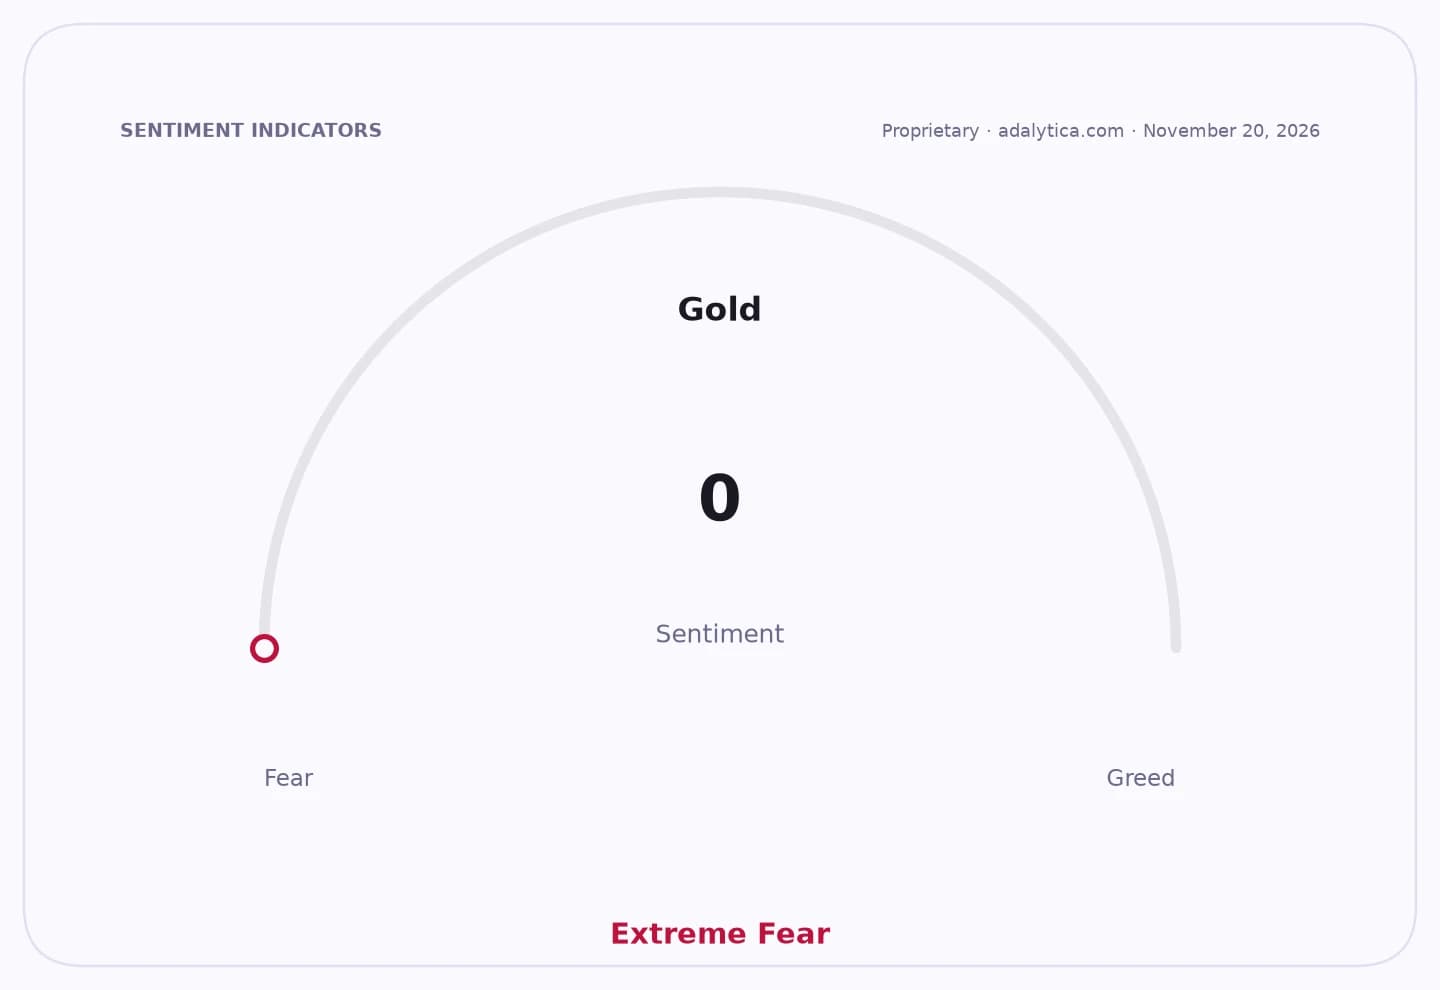
Gold
That matters because gold is not just a retail product in Vietnam; it is a barometer for global real yields, the dollar and expectations for Federal Reserve policy. When bullion breaks lower while U.S. rates remain elevated, the cost of holding a non-yielding asset rises, and the market begins repricing the entire precious-metals trade.
Sentiment Indicators
In the local market, SJC, PNJ, DOJI and Bao Tin Manh Hai all cut gold bar prices by 500,000 dong per tael on both sides to 134.2 million-137.2 million dong. Phu Quy lowered buying prices by 1.1 million dong and selling prices by 500,000 dong to 133.2 million-137.2 million dong. Gold rings also weakened further, with the highest quoted selling price at 137 million dong per tael.
The driver is global. Spot gold broke below $3,750 an ounce and fell to the lowest level since September 2025 as the dollar strengthened and Treasury yields stayed near 5.1%, leaving investors with little reason to own bullion. Markets are now pricing a 95.7% chance the Fed will lift rates another 25 basis points at its Dec. 8-9 meeting, according to futures data cited by Kitco, a backdrop that keeps pressure on precious metals and on mining shares.
That stress is visible in exchange-traded funds as well. The SPDR Gold Shares ETF, or GLD, has slipped below its 50-day moving average and is trading well under its 200-day moving average, while its RSI has fallen to 34.2, a sign of weakening momentum rather than a simple pause. The VanEck Gold Miners ETF, GDX, is faring worse, underscoring that miners are being hit not only by lower bullion prices but also by margin compression fears if the slide persists.
The macro setup is the real story. U.S. housing data offered mixed signals, with starts rising but permits falling, leaving growth hopes intact enough to support higher-for-longer rate expectations while not yet convincing traders that the Fed will ease. On top of that, the dollar has climbed to near 103.70, and the market is still waiting for the October Fed minutes for any hint of dovish pushback.
For investors, the message is straightforward: this is a tactical headwind for gold bulls, but it is also the kind of selloff that can create asymmetric opportunities once rate expectations stabilize. Near term, the pressure is on bullion, ETFs and miners. The best setup, if the Fed narrative eventually softens, may be in high-quality gold producers and leveraged miners that have already been marked down before the next macro turn.
| Entity | Gains | Losses |
|---|---|---|
| Gold buyers in Vietnam | ▲Lower entry prices | ▼Sellers’ margins |
| Gold miners and bullion ETFs | ▲— | ▼Margin pressure, weak momentum |
| U.S. dollar and Treasury yields | ▲Relative strength | ▼Gold demand |
| Fed hawks / higher-for-longer bets | ▲Policy credibility | ▼Precious metals bulls |