Greece is set to widen its debt-settlement scheme to 120 monthly installments, a move aimed at helping households and smaller businesses cope with overdue obligations to the tax office and social security funds while improving collections for the state.
Greece widens debt settlement to 120 installments
Liquidity Conditions
The draft package, tabled in parliament by the finance ministry, lifts the maximum number of payments from 72 to 120 and extends the pool of debts that can be folded into the plan. It covers certified arrears to the tax authorities and social insurance funds that became overdue by Dec. 31, 2024, provided they were not already in a settlement plan on Sept. 30, 2026. The minimum monthly payment stays at 30 euros, and applications must be filed by June 30, 2027.
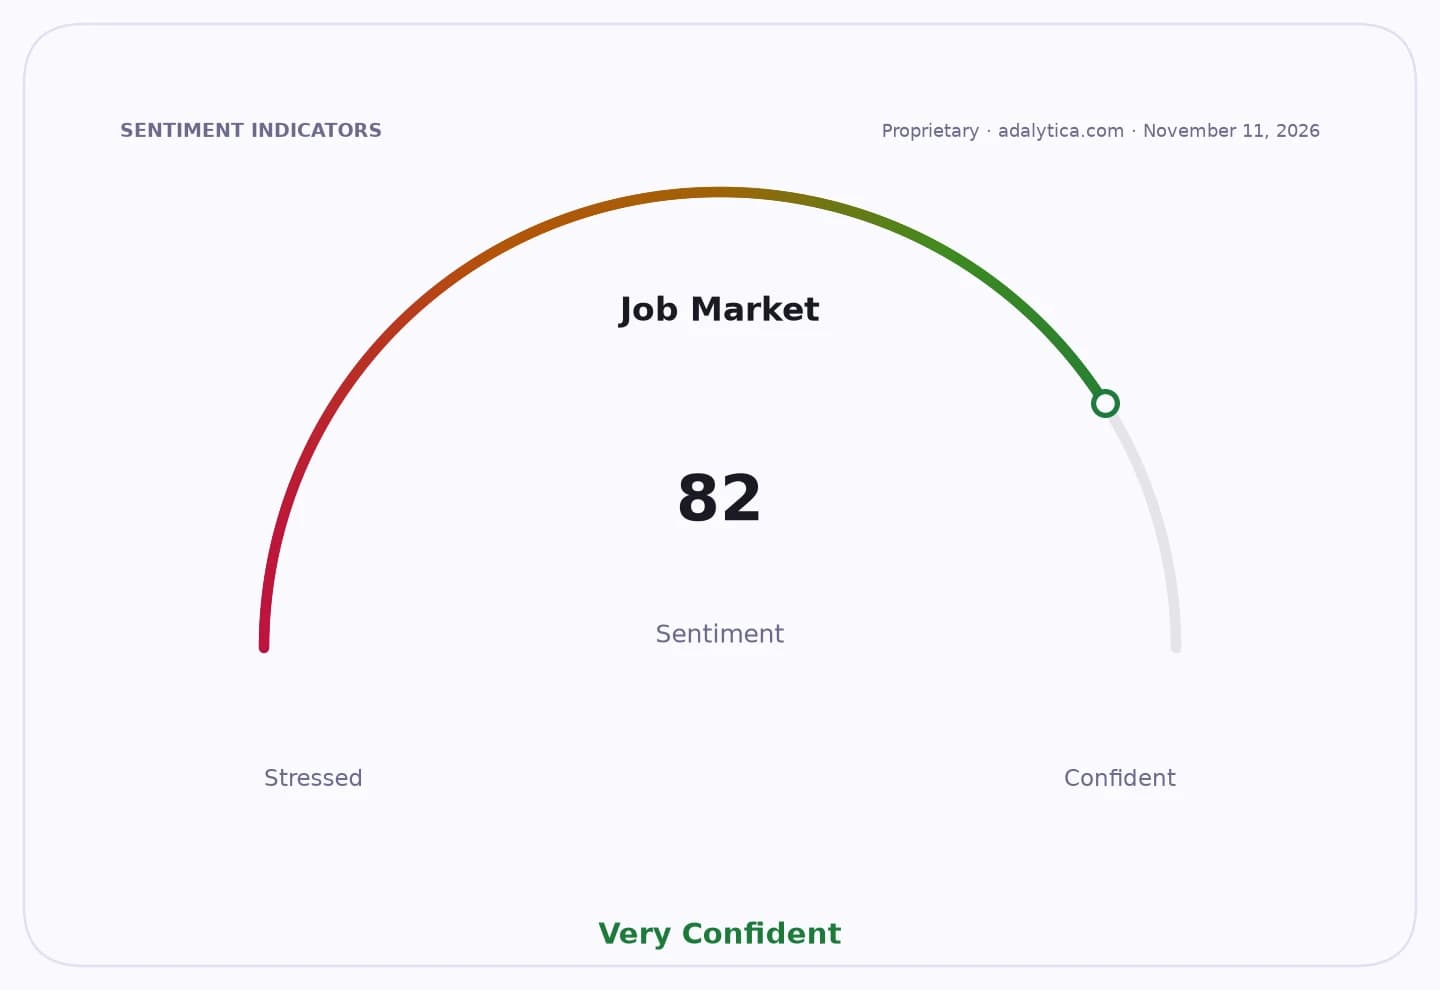
Sentiment Indicators
The policy matters because Greece still carries the legacy of a long arrears overhang. A longer repayment horizon lowers the monthly burden for debtors, increasing the odds that more households and firms will re-enter the formal repayment system instead of falling into enforcement, write-offs or insolvency. For the state, the trade-off is obvious: collections may arrive more slowly, but the probability of actually collecting increases if distressed taxpayers can service the debt.
The bill also allows borrowers already under the existing 72-installment regime to switch voluntarily to the new 120-payment framework. That could offer immediate cash-flow relief, though it also lengthens the interest burden. In practice, the measure is designed to reduce default pressure at a time when financing conditions remain tight and economic uncertainty still weighs on vulnerable borrowers.
The package goes beyond tax arrears. It shortens the period for full debt discharge after bankruptcy from 36 months to 12 months, accelerating financial rehabilitation for failed borrowers and potentially making insolvency a more credible restart mechanism. It also removes time limits on settlements for debts arising from calls on Greek state guarantees and guarantees issued by the Hellenic Development Bank and TEMPME, broadening the universe of obligations that can be restructured.
For investors, the key question is whether the government is using a one-off relief measure to stabilize collections or quietly normalizing repeated debt amnesties. A more generous installment plan can support consumer spending, protect small-business cash flow and lower near-term social stress, but it can also encourage payment deferral if market participants conclude that arrears will always be refinanced. That balance will matter for fiscal credibility, bank recovery values and the broader perception of Greek credit quality.
The bill now moves through parliament, and the market will watch whether the new terms translate into higher participation, better tax compliance and fewer nonperforming balances across the economy.
| Entity | Gains | Losses |
|---|---|---|
| Debtors | ▲Lower monthly payments | ▼Longer repayment period |
| Greek state | ▲Higher collection odds | ▼Slower cash receipts |
| Banks/servicers | ▲Better recovery prospects | ▼More extended workout timelines |
| Compliant taxpayers | ▲Fewer spillovers from distress | ▼Risk of moral hazard |