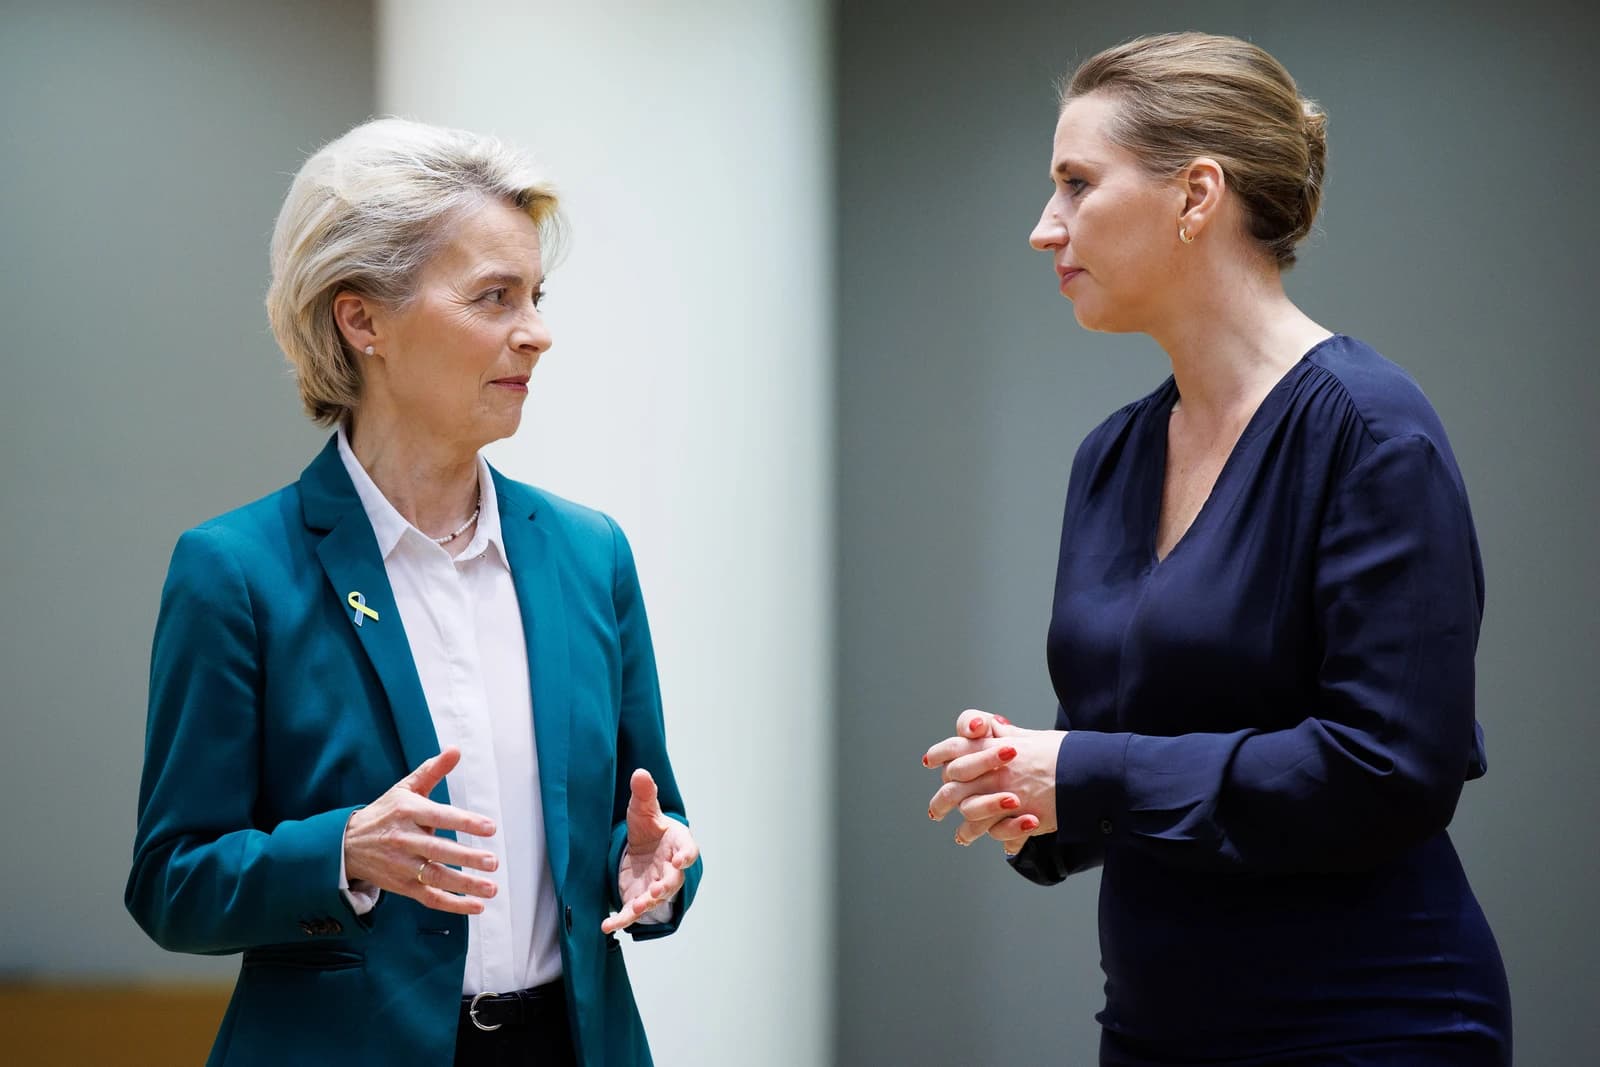
Greece’s next growth phase will depend less on EU recovery money and more on private capital, Prime Minister Kyriakos Mitsotakis said, signalling a policy pivot that matters for an economy still trying to convert post-crisis gains into a durable investment cycle.
Greece Shifts Growth Focus to Private Investment
The message is economically significant because the Recovery Fund has been one of the main supports for Greek growth, public works and confidence since the pandemic. Mitsotakis acknowledged that the country will still have European funding through the next budget cycle, including a new ES PA and Common Agricultural Policy allocation, but he framed that as a bridge rather than a growth model. “The secret will be private investments,” he said, adding that the government must “sweep away” the barriers that continue to hold investment back.
Sentiment IndicatorsⓘProprietary · adalytica.com · September 6, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
For investors, the shift matters because it raises the bar for Greece’s medium-term story. If growth is to remain above euro-area averages once Recovery Fund disbursements fade, the key test becomes whether Athens can attract enough domestic and foreign capital into productive sectors — industry, infrastructure, energy, real estate and technology — to offset the loss of public stimulus. That is a more demanding proposition than relying on grant-funded projects, and it makes policy execution, permitting reform and the speed of judicial and administrative change central to valuations.
Mitsotakis also pushed back against the idea that Greece’s expansion is simply the result of EU money, pointing to Italy’s weaker growth despite also drawing on Recovery Fund resources. The comparison was meant to underline a broader thesis: funds alone do not generate sustained output unless they are matched by investment appetite and a business environment that can absorb them.
That argument speaks directly to the market backdrop. Greece has benefited from a rebound in investor confidence in recent years, but the next leg will depend on whether the state can turn lower-risk sovereign perceptions into broader private-sector participation. The bull case is that Greece still has tailwinds: fresh EU funds, a healthier banking system than in the last decade, and sectors such as tourism, energy and logistics that can attract capital quickly. The bear case is that bureaucracy, slow licensing and structural bottlenecks keep investment below the level needed to lift productivity and wages materially.
The policy implication is clear. Once the Recovery Fund tap narrows, Greece will be judged not by how much public money it spends, but by how much private money it can crowd in. For equity and bond investors, that means watching reform delivery, capex flows and the pace of project approvals as closely as headline growth figures.
| Entity | Gains | Losses |
|---|---|---|
| Greek government | ▲Reform credibility | ▼Patience for slow execution |
| Private investors | ▲New opportunities | ▼Policy and permitting risk |
| EU funds/RRF | ▲Transitional support role | ▼Centrality to growth narrative |
| Public-sector-led model | ▲Short-term infrastructure boost | ▼Long-term dominance in growth |