Guardian Media Group lifted revenue to a record £282m as a surging US business and rising digital supporter income helped cushion the hit from the sale of The Observer and the long slide in print.
Guardian Media Group revenue hits record £282m
The result matters because it shows one of Britain’s most prominent news groups is increasingly being financed by readers outside its home market, at a time when traditional newspaper economics remain under pressure and AI threatens to weaken referral traffic and discovery. The Guardian’s model is still loss-making, but it is becoming less dependent on print and more reliant on recurring digital revenue and an expanding international audience.
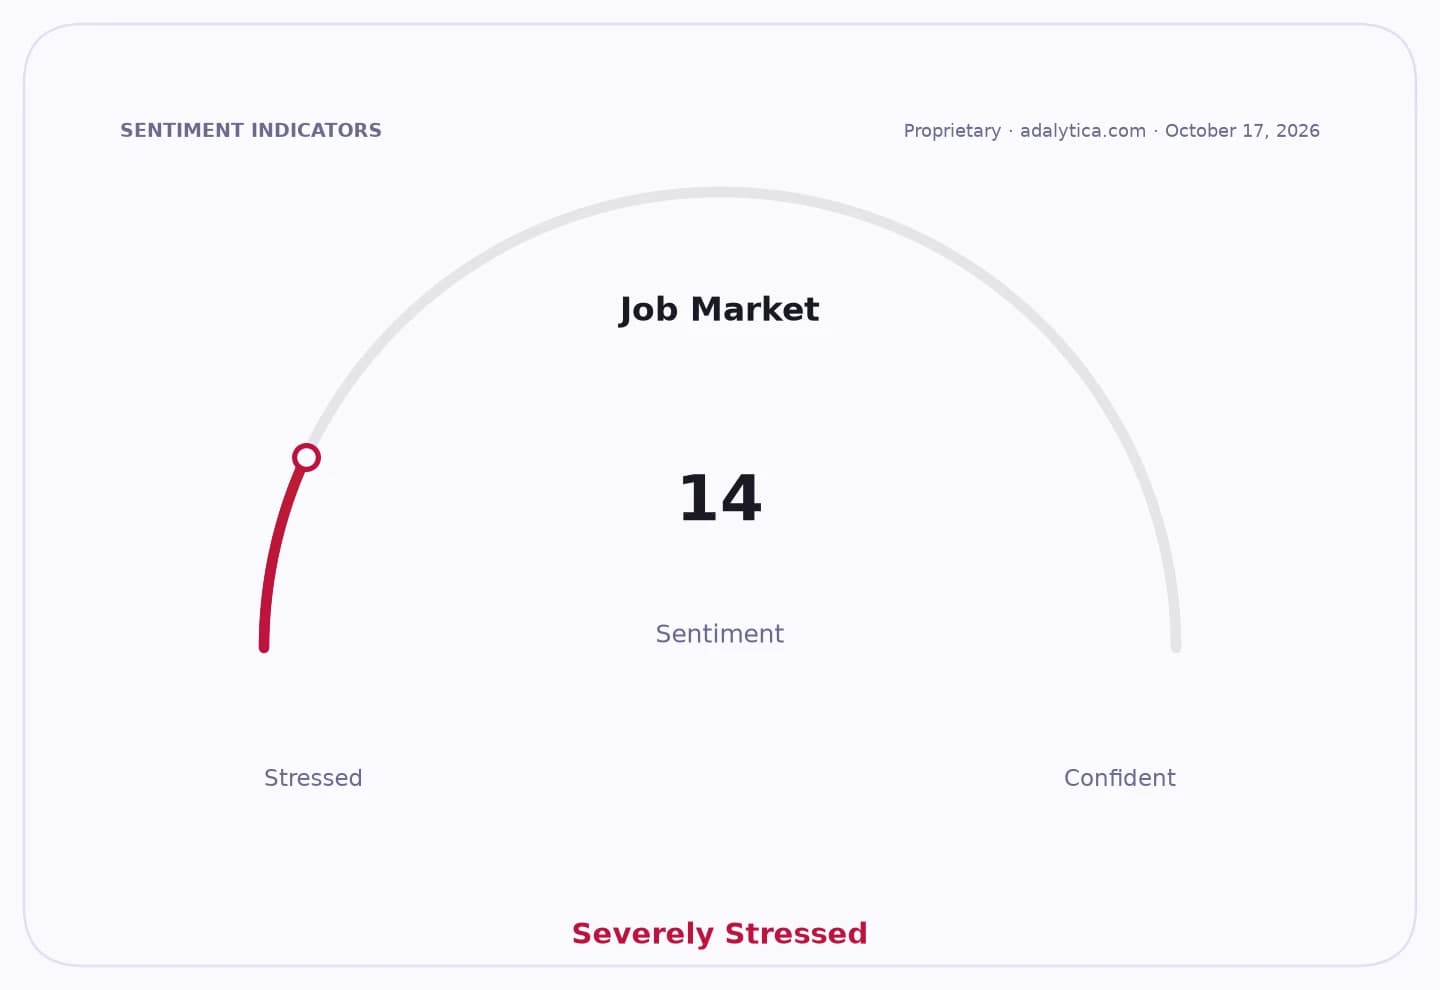
Sentiment IndicatorsⓘProprietary · adalytica.com · October 19, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
Revenue from paying online readers rose 17% to £126m in the year to March 2026, a record for that line of business. Overall revenue increased 2% to £282m even though annual print revenue fell by about £18m after the Observer was sold to Tortoise Media in April 2025. The group said the total was a record for its news operation, excluding revenue from former subsidiary businesses.
The US is now the clearest engine of growth. Revenue from the market climbed 14% to £63.8m, while UK revenue slipped to £167.6m. Non-UK revenue made up 41% of the business, underscoring how far the Guardian’s commercial base has shifted beyond Britain. The paper said it now has 1.4 million recurring paying digital supporters, up 116,000 on the year, with about 500,000 based in the US.
That matters to investors and the wider media industry because the Guardian is one of the most closely watched examples of a reader-funded newsroom that does not rely heavily on advertising or a paywall. If the model can keep growing in the US, it strengthens the argument that global news brands can build durable subscription-like revenue streams around direct audience relationships. If not, it leaves the group exposed to rising content costs, shifting platform algorithms and a tougher digital market.
The Guardian’s losses, measured as net cash outflow, fell to £17m from £25m a year earlier and £37m in 2024, aided by the enlarged supporter base and the endowment fund, which grew by £100m to £1.35bn. That financial cushion gives the company room to keep investing, but it also highlights a basic tension: growth is improving, yet the business still depends on its endowment to underwrite deficits.
The US operation has become central to that strategy. It now employs 150 journalists, double the number three years ago, as the Guardian pushes deeper into a market where political scrutiny, audience scale and digital ad potential are all larger than in the UK. Management is also leaning into visual journalism, social video and younger audiences through Project Berger and Guardian Studios, a sign that future revenue growth may depend as much on format shift as on traditional article subscriptions.
For investors and peers, the key question is whether the Guardian can keep converting brand strength into recurring revenue fast enough to outpace structural headwinds. The bull case is that its global audience, especially in the US, still has room to pay. The bear case is that print erosion, rising competition and changing information habits will eventually cap growth, even for a strong brand. For now, the numbers suggest the Guardian is still finding new buyers for its journalism, and doing so increasingly in America.
| Entity | Gains | Losses |
|---|---|---|
| Guardian Media Group | ▲Record revenue, lower losses | ▼Print income decline |
| US operation | ▲Faster growth, larger audience | ▼Higher investment burden |
| Digital supporters | ▲More journalism access | ▼Greater reliance on recurring payments |
| Print business / Observer legacy | ▲— | ▼Revenue erosion, reduced scale |