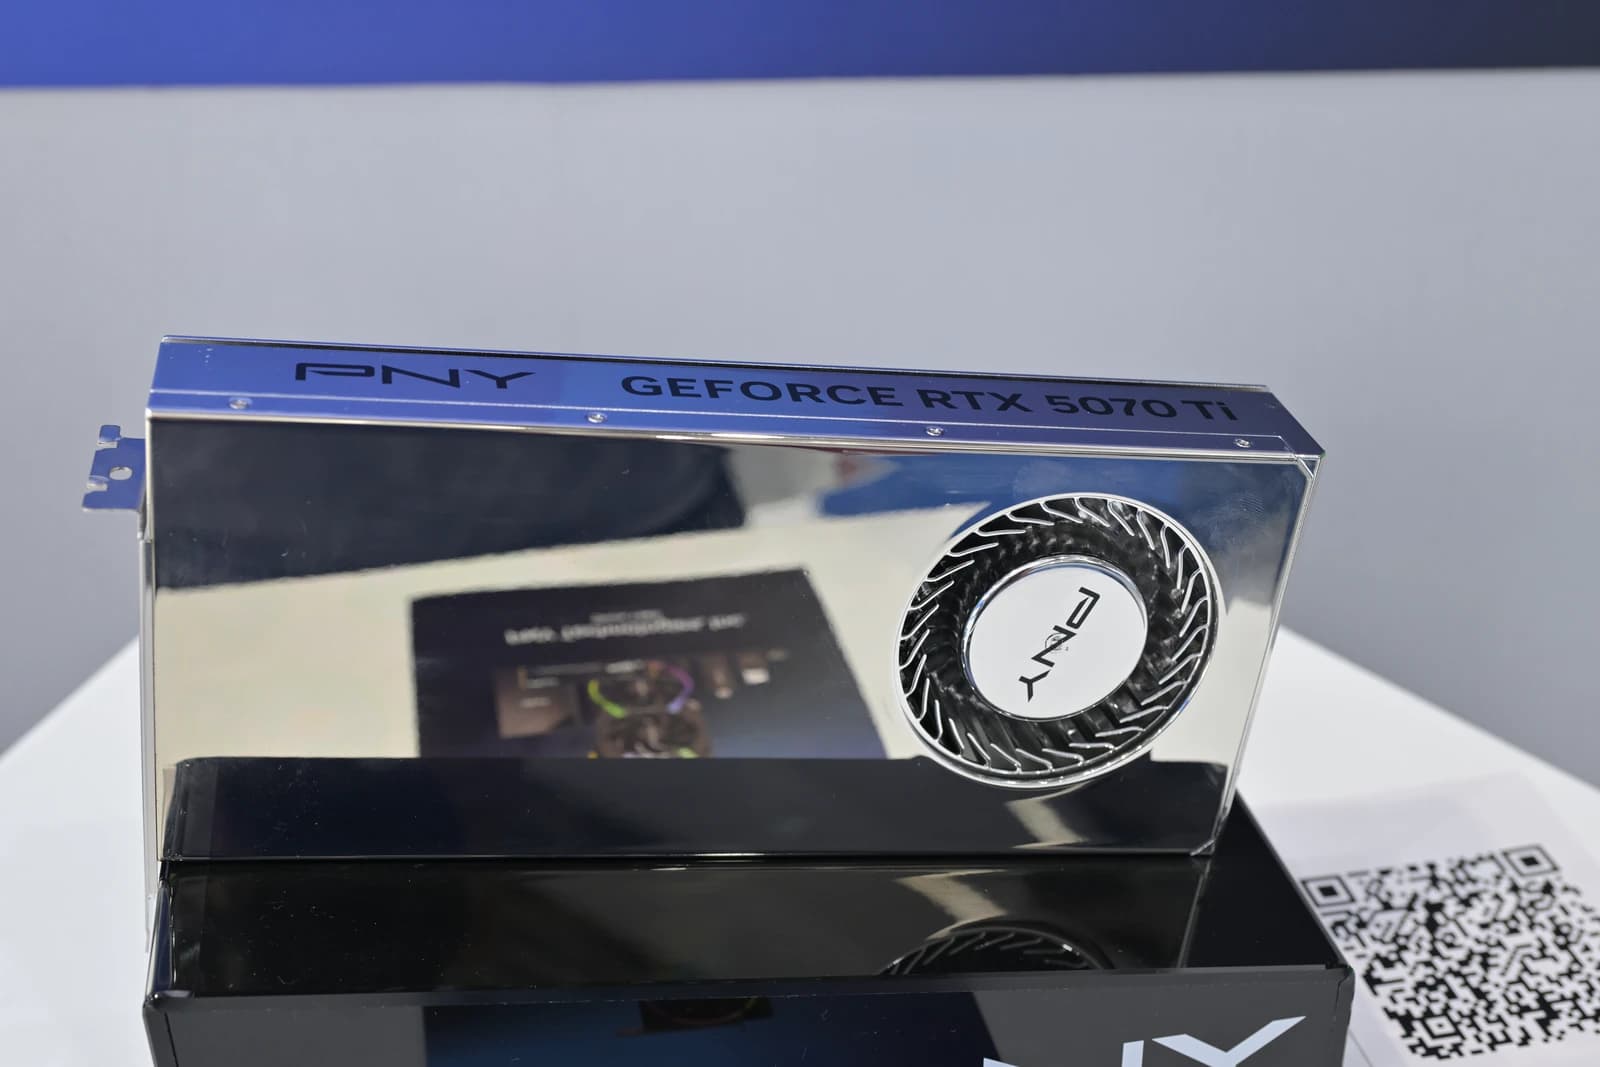
Two H20 96G eight-card servers in central China were still available for rent after two days on the market, a small but closely watched sign that pricing in the AI-compute rental market is softening even as demand for Nvidia-powered capacity remains uneven.
H20 96G server rentals in China stay open
The units are listed at 43,000 yuan a month, tax included, on one-year contracts with a one-month deposit, according to SMM. Bandwidth is billed separately at 15 yuan per M per month, and the configuration includes 400G IB networking, 2TB of memory and redundant power supplies.
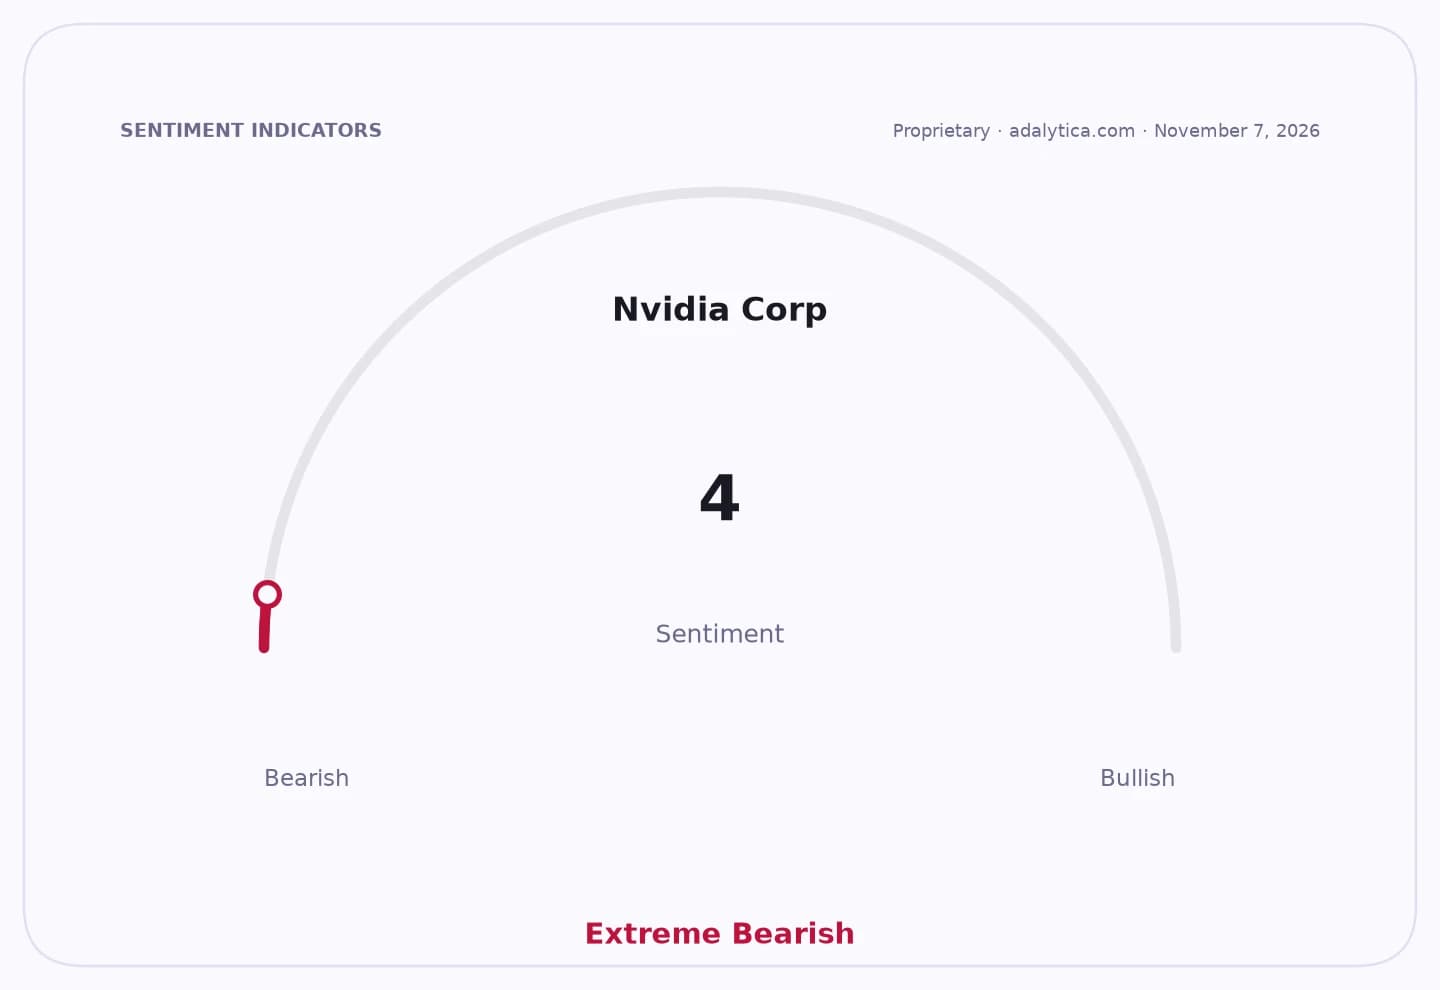
Sentiment Indicators
That price sits below the 46,000 yuan pre-sale quote for the same specification in east China, but above the 41,000 yuan annual contract level in south China. SMM said the delivery date has not yet arrived and the observation window is too short to conclude demand is weakening, but the fact that the listing has remained open for two days suggests buyers are becoming more selective on cost, geography and contract structure.
For investors, the read-through is less about two servers than about the pace of monetization across the AI infrastructure supply chain. If rental prices keep drifting lower, it could pressure margins for data center operators, cloud brokers and resellers chasing scarce H20-capacity economics, while also signaling that near-term deployment demand is not as tight as some have expected.
That matters for chipmakers and compute-linked names because H20 rental pricing is one of the clearest market-based gauges of how much customers are willing to pay for constrained AI hardware in China. Any sustained easing would imply slower pricing power for intermediaries, even if underlying interest in inference and training workloads remains intact.
The next catalyst is whether the units move once delivery starts on Oct. 20, which will show whether the current listing delay is just a timing issue or the first sign of a broader cooling in China’s AI compute rental market.
| Entity | Gains | Losses |
|---|---|---|
| Renters / buyers | ▲Lower entry cost | ▼Less urgency to secure capacity |
| Server lessors / brokers | ▲Potential volume if deals clear | ▼Softer pricing power |
| China AI compute market | ▲More price discovery | ▼Signs of supply easing |
| Nvidia H20 ecosystem | ▲Continued demand visibility | ▼Weaker rental-rate leverage |