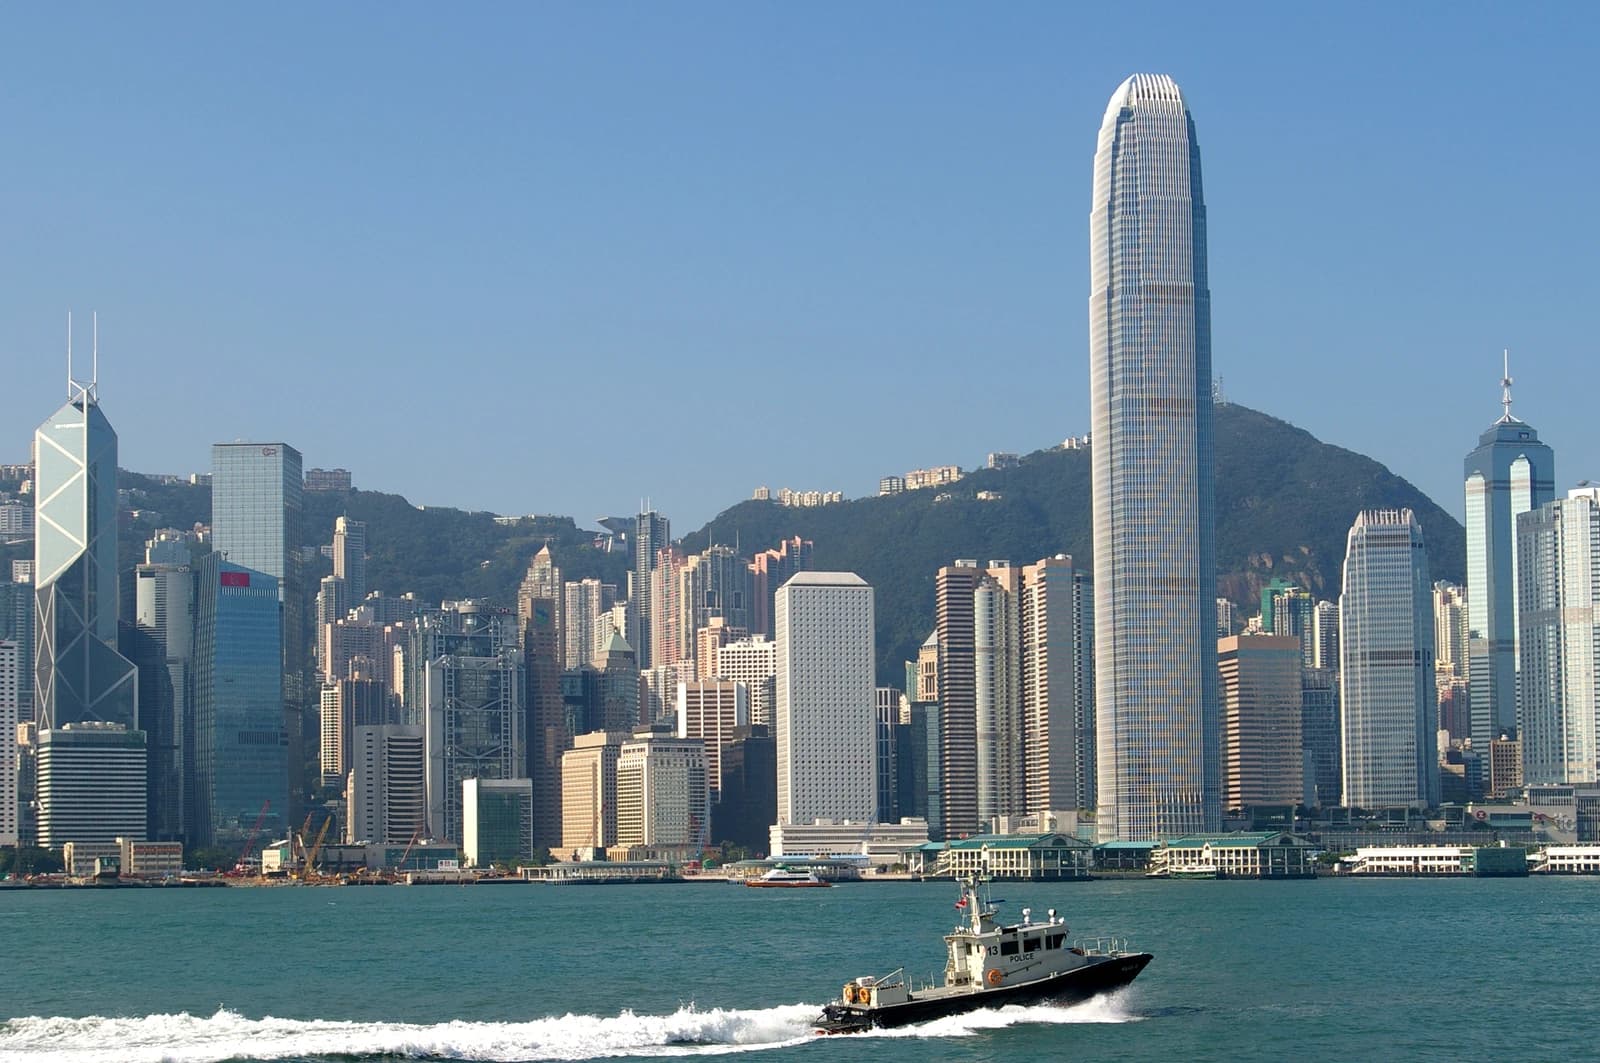
Hong Kong’s Hang Seng Index slipped on Wednesday, with losses in financial and technology shares outweighing gains in energy, retail and electronics as investors braced for US inflation data that could keep global borrowing costs elevated.
Hang Seng Falls 0.13% Before US CPI Data
The benchmark [HSI.X] closed at 24,314.17, down 31.05 points, or 0.13%, with the retreat leaving the market little changed but underscoring caution in rate-sensitive sectors. Akeso fell 9.6%, Z.AI Co. dropped 4.8% and Kingboard Laminates lost 5.2%, illustrating the pressure on growth and biotech names even as oil-linked stocks found support.
Sentiment IndicatorsⓘProprietary · adalytica.com · October 15, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The immediate market focus is the US consumer price index report later in the day, followed by producer prices on Thursday. Economists expect headline US CPI to accelerate to 3.6% year on year in September from 3.4% in August, while core CPI is seen rising 2.5% from 2.4%, numbers that could reinforce bets the Federal Reserve will keep policy tight or even raise rates again.
That backdrop mattered in Hong Kong because higher US inflation typically supports the dollar and Treasury yields, tightening global financial conditions and dampening appetite for Asian risk assets. A stronger rate outlook can be especially negative for technology shares and other valuation-sensitive sectors, while financial stocks face a more mixed response as higher yields can help margins but also raise broader market volatility.
The market was also digesting firmer price signals out of China, where producer prices rose 5% in September from a year earlier, above forecasts and up sharply from 3.8% in August. Consumer inflation in China rose 0.9%, below expectations, keeping alive concerns that demand remains uneven even as input costs climb.
Oil added another inflationary wrinkle, with Brent crude climbing to $106.60 a barrel after repeated attacks on Saudi energy infrastructure fueled supply worries. That kept pressure on the inflation narrative globally and helped explain why defensive and commodity-linked shares held up better than financial-tech names in Hong Kong.
With the Hang Seng hovering below its 50-day moving average and the index still beneath its 200-day average, traders are likely to stay cautious until the US inflation prints and Fed expectations settle. The next catalyst is the CPI release, which could determine whether rate fears extend the recent rotation out of Asian growth stocks.
| Entity | Gains | Losses |
|---|---|---|
| Energy stocks | ▲Higher oil prices | ▼Rate-sensitive tech shares |
| Hong Kong banks | ▲Wider yield backdrop | ▼Growth and biotech stocks |
| Oil exporters | ▲Stronger Brent crude | ▼Importers facing higher costs |
| US dollar | ▲Tightening rate expectations | ▼Risk assets in Asia |