Vietnam’s biggest real-estate lobby is pushing lawmakers to formally recognize affordable commercial housing, arguing the market has effectively shut out middle- and lower-income buyers as high-end projects dominate supply in Ho Chi Minh City.
HoREA seeks affordable housing law in Vietnam

The proposal from the Ho Chi Minh City Real Estate Association, or HoREA, lands as housing affordability remains a political and economic pressure point across large cities, where a shortage of lower-priced homes is worsening rent strain, mobility challenges and broader cost-of-living stress. For developers, the issue is increasingly about whether policy can revive a mass-market segment without turning it into subsidized social housing.
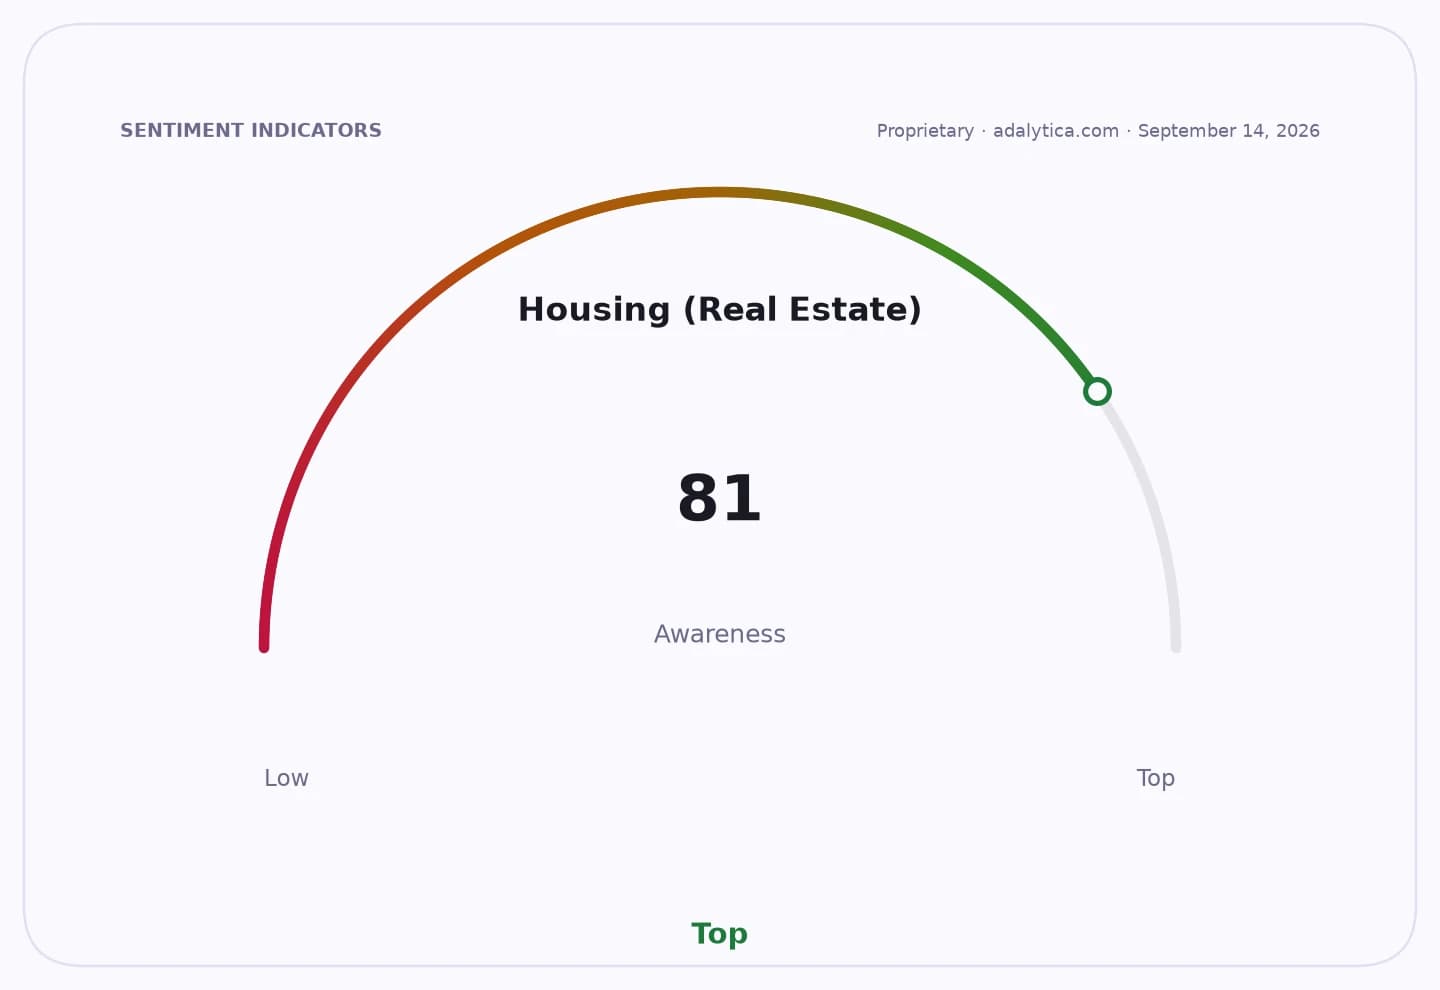
Sentiment IndicatorsⓘProprietary · adalytica.com · September 10, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse

HoREA wants the concept added to the revised Housing Law after a version circulated on July 22 included a dedicated chapter for affordable commercial homes, only for a later draft on Aug. 5 to drop the language. The group is urging the government, construction ministry, police ministry and justice ministry to restore it and set a legal framework for projects sold outright, sold in installments or rented at capped prices.
The backdrop is a sharp collapse in supply. In Ho Chi Minh City’s former boundary, the number of commercial housing projects eligible to raise capital fell to just six in 2024 from 92 in 2017, while units dropped to 3,845 from 42,991. Affordable commercial homes have effectively disappeared entirely: HoREA said the segment fell from 12,495 units in 2017 to zero from 2021 through 2024.
At the same time, premium housing has taken over the market. HoREA said high-end projects accounted for roughly 70% of supply from 2019 through 2023 and made up all 3,845 commercial units tracked in 2024. That imbalance matters because it leaves a large pool of buyers stuck between social housing eligibility and the luxury market, pushing demand into the rental market and keeping price pressure elevated.
HoREA’s proposal is meant to fill that gap. It targets middle-income buyers, lower-income households not eligible for social housing, and some social-housing-eligible buyers who can stretch to a commercial product if financing is available. The group argues developers should participate voluntarily, keep their profit calculations market-based and comply with a local price ceiling rather than a government-imposed cap on margin.
The lobby is also reviving the logic of Vietnam’s 2013 VND30 trillion credit package, which supported homes priced at no more than VND1.05 billion and drew wide developer participation. This time, it is proposing a VND145 trillion credit line, with suggested lending rates of 6.1% for developers and 5.9% for buyers.
The economics of the proposal hinge on land costs, which HoREA says account for about 35% of one affordable commercial project it cited in Dĩ An, where a 70-square-meter unit was priced around VND3.15 billion, or VND45 million per square meter. The association says using land-price tables and adjustment coefficients to calculate compensation and land-use fees could create room to lower final selling prices.
For investors, the debate matters because it could shift the economics of Vietnam’s residential sector away from a narrow luxury pipeline and toward larger-volume, lower-margin development if lawmakers adopt the framework. Any move to cap prices while leaving profits uncapped would favor landholders and efficient builders, but it could also pressure developers reliant on scarce premium inventory.
The proposal also has implications beyond Vietnam. AMH, AvalonBay and Equity Residential have all faced investor scrutiny in a U.S. market where housing shortages have supported rents and valuations, while policy efforts from Washington to local governments increasingly focus on affordability. In Vietnam, the question is whether a legal definition and financing support can bring back a missing middle before the housing market becomes even more skewed toward the wealthy.
| Entity | Gains | Losses |
|---|---|---|
| Middle-income buyers | ▲More access to priced-out supply | ▼Less reliance on the rental market |
| Developers able to build at scale | ▲Larger buyer pool, policy support | ▼Lower margins than luxury projects |
| High-end housing owners | ▲None | ▼Less policy attention, possible demand shift |
| Landowners with expensive sites | ▲Potential value unlock | ▼Pressure if land-cost reforms cut project pricing |