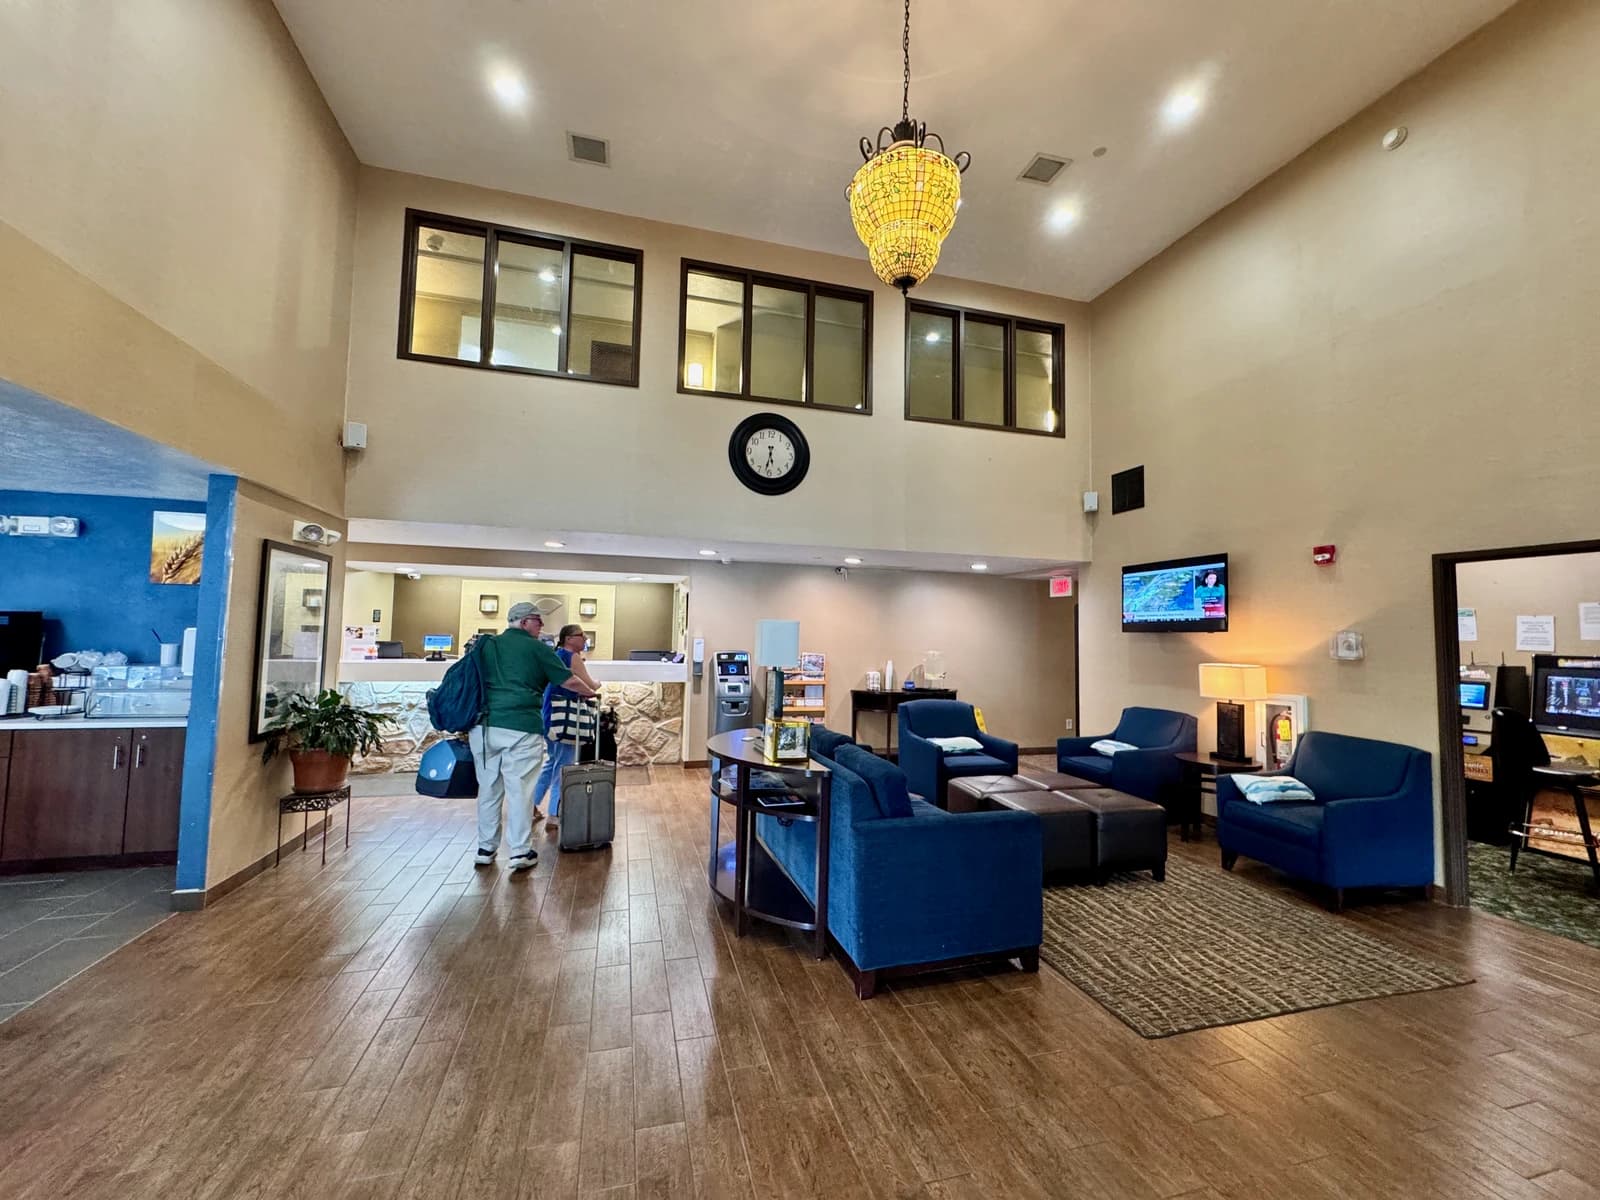
Host Hotels & Resorts delivered a solid third quarter and lifted its full-year outlook, but the bigger investor question is whether stronger hotel demand is enough to offset the REIT’s heavy reinvestment burden and more cyclical earnings profile.
Host Hotels raises outlook after strong Q3
The lodging landlord said comparable-hotel revenue per available room rose 7.3% to $348.19 in the quarter, with average rates up 5.6% and occupancy up 2.1%. That translated into adjusted funds from operations of 39 cents a share, up 11.4% year over year and well above the 20-cent quarterly dividend. Management also nudged its 2026 comparable RevPAR growth forecast to 6% from 5%, and raised expected adjusted FFO to $2.21 a share from $2.16.
Sentiment Indicators
The result reinforces a simple thesis: premium hotels in major markets are still benefiting from a healthy mix of transient leisure, business travel and group bookings. Host said the quarter got a lift from World Cup-related demand and stronger corporate travel, while group demand remained firm. That matters because hotel REITs are among the most economically sensitive real estate owners; when demand holds up, pricing power and occupancy can move quickly, but so can downturns.
Investors have already rewarded the improvement. Host shares have climbed more than 60% over the past year and recently traded above $26, leaving the stock at less than 12 times FFO with a dividend yield above 3%. On paper, that is not demanding for a company with investment-grade credit and a portfolio skewed to luxury and upper-upscale properties.
The catch is that hotel ownership is capital intensive in a way that makes headline FFO look cleaner than the economics really are. Host expects $550 million to $600 million of capital spending in 2026, including as much as $305 million for recurring renewals and replacements. Unlike a net-lease REIT, it cannot push maintenance costs onto tenants. That means a meaningful slice of cash generation must stay inside the business simply to keep the portfolio competitive.
Host is trying to improve that equation by recycling capital into higher-quality assets. It bought the 195-room 1 Hotel Brooklyn Bridge and the 308-room Renaissance Dallas at Plano Legacy West, while selling lower-priority properties including the Four Seasons Resort Orlando, the Four Seasons Jackson Hole and the St. Regis Houston. Management said those sales will save about $137 million of capital spending over the next five years, supporting a more durable earnings base over time.
That strategy is constructive for long-term holders, but it does not eliminate the core risks. Hotel earnings are still tied to the economic cycle, and the stock has already rerated sharply. In that context, the bullish case rests on continued demand strength and disciplined portfolio turnover, while the bear case is that the valuation now reflects much of the good news while leaving investors exposed to recession risk and ongoing capex needs.
For now, Host looks like a quality operator with improving fundamentals rather than an obvious bargain. The latest quarter supports the business case, but not necessarily a rush to buy the stock at current levels.
| Entity | Gains | Losses |
|---|---|---|
| Host Hotels & Resorts | ▲Higher RevPAR and FFO | ▼Heavy maintenance capex |
| Shareholders | ▲Stronger dividend coverage | ▼Limited upside at current valuation |
| Luxury hotel market | ▲Better pricing power | ▼Risk of cyclical slowdown |
| Net-lease REITs | ▲More predictable cash flows | ▼Less growth from hotel rebound |