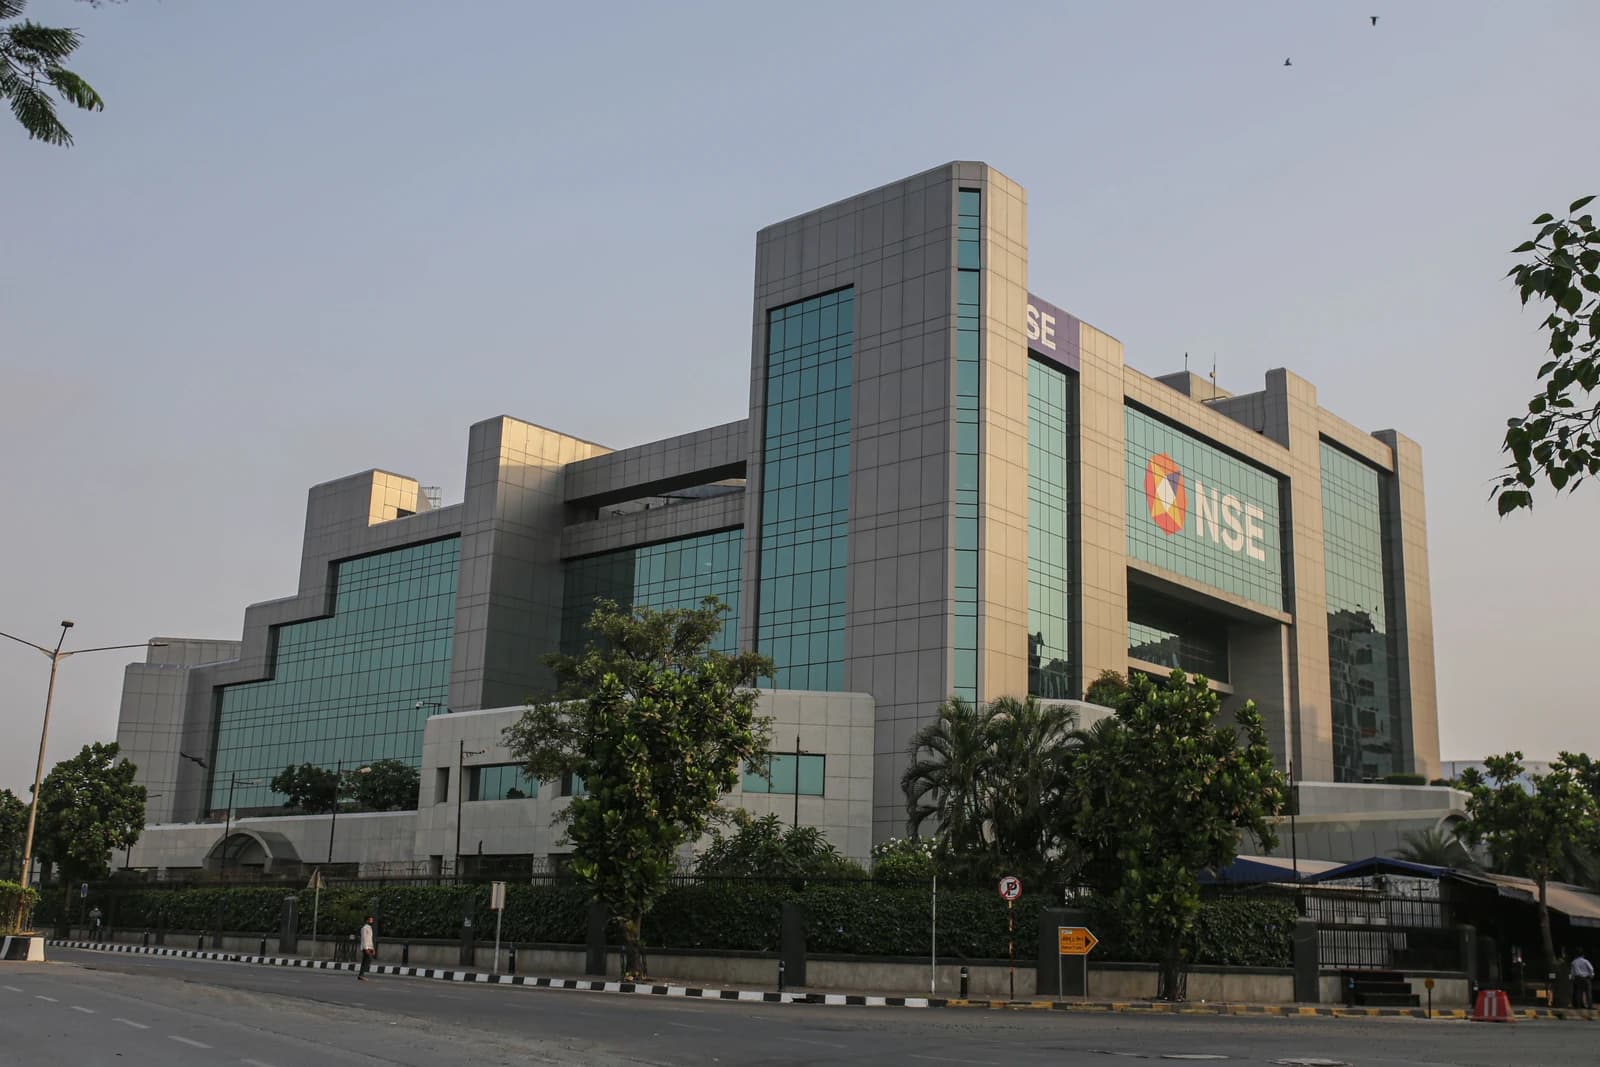
India’s banks are expected to turn a $133 billion FCNR-B deposit surge into loan growth over the festive season, giving lenders a timely liquidity boost as credit demand stays firm and the Reserve Bank of India keeps pressure on underwriting standards.
India banks get $133B FCNR-B deposit boost
The central bank’s special foreign-currency deposit window closed a month early on Aug. 31 after drawing a stronger-than-expected response from non-resident Indians, according to RBI Deputy Governor Rohit Jain. That mattered because FCNR-B money arrives as foreign-currency liabilities and can be deployed by banks to support lending without immediately straining rupee funding conditions, effectively giving the system a fresh pool of low-friction liquidity just as households and businesses typically borrow more for the holiday period.
Sentiment IndicatorsⓘProprietary · adalytica.com · September 29, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
Jain said banks had told the RBI they expected to deploy the funds over the next few months, aided by festive-season demand. The central bank is not directing lenders toward any specific sector, but it is watching how the inflows are used and remains focused on credit discipline. That suggests the RBI sees the deposits less as a windfall for aggressive balance-sheet expansion than as a buffer that can support measured loan growth in an economy where credit appetite remains solid.
The scale of the response was large even by India’s standards. RBI data cited by the deputy governor showed total inflows across FCNR(B), overseas foreign currency borrowings and external commercial borrowings at $143.596 billion as of Sept. 18, with FCNR-B deposits alone accounting for $133 billion. The scheme was originally scheduled to run until Sept. 30, but was shortened after hitting its objective early, underscoring how attractive the funding avenue proved for banks and how willing the diaspora was to place money with Indian lenders despite currency risk being borne in foreign currency terms.
For banks, the immediate implication is better access to funding at a time when deposit competition can tighten margins. For borrowers, the bigger issue is whether lenders convert the liquidity into productive credit rather than simply parking it. That balance will shape net interest margins, loan growth and asset quality into the year-end, particularly if banks lean into consumer and small-business demand without easing underwriting too far.
The RBI’s message was broader than the deposit window. Jain said India’s foreign-exchange reserves are now managed with safety, liquidity and return in mind, and that the country has become the world’s fifth-largest holder of reserves. He also noted the central bank’s push for cleaner state-government securities issuance and its support for tokenisation, but the immediate market takeaway is that RBI policy is still centered on resilience: enough liquidity to keep credit flowing, but not enough to encourage a lending race.
That matters for investors because the FCNR inflows support the case for steadier earnings at Indian lenders, especially those with strong corporate and retail franchises heading into the festive period. It also reduces near-term funding stress in a system where deposits, rather than capital, often determine how quickly banks can grow. The risk is that the liquidity cushion proves temporary if loan demand slows after the season or if banks misread the signal and lower pricing discipline.
For now, the FCNR-B window has done what policymakers wanted: it brought in foreign-currency funds quickly, strengthened bank liquidity and set up a pipeline for credit demand into the busiest lending season of the year. What happens next will show whether the inflows become durable loan growth or simply a short-lived balance-sheet lift.
| Entity | Gains | Losses |
|---|---|---|
| Indian banks | ▲Lower funding pressure | ▼Tighter margin discipline |
| Borrowers | ▲Easier festive credit access | ▼Less pricing power from banks |
| RBI | ▲Stronger system liquidity | ▼Risk of weaker underwriting |
| Non-resident depositors | ▲Foreign-currency safety | ▼Lower yield alternatives |