India’s government bond rally looks set to extend, but only modestly, as Brent crude dips below $100 a barrel and gives policymakers a little more room to breathe on inflation and the fiscal outlook.
India bonds rise as Brent dips below $100
The move matters because oil is one of the biggest external shocks for India’s macro balance sheet. A sustained pullback in crude eases pressure on the current account, softens imported inflation and reduces the odds that the Reserve Bank of India has to stay tighter for longer. That should support sovereign bonds even as the benchmark 10-year U.S. Treasury yield sits above 5%, keeping global duration under pressure and limiting how far Indian yields can fall.
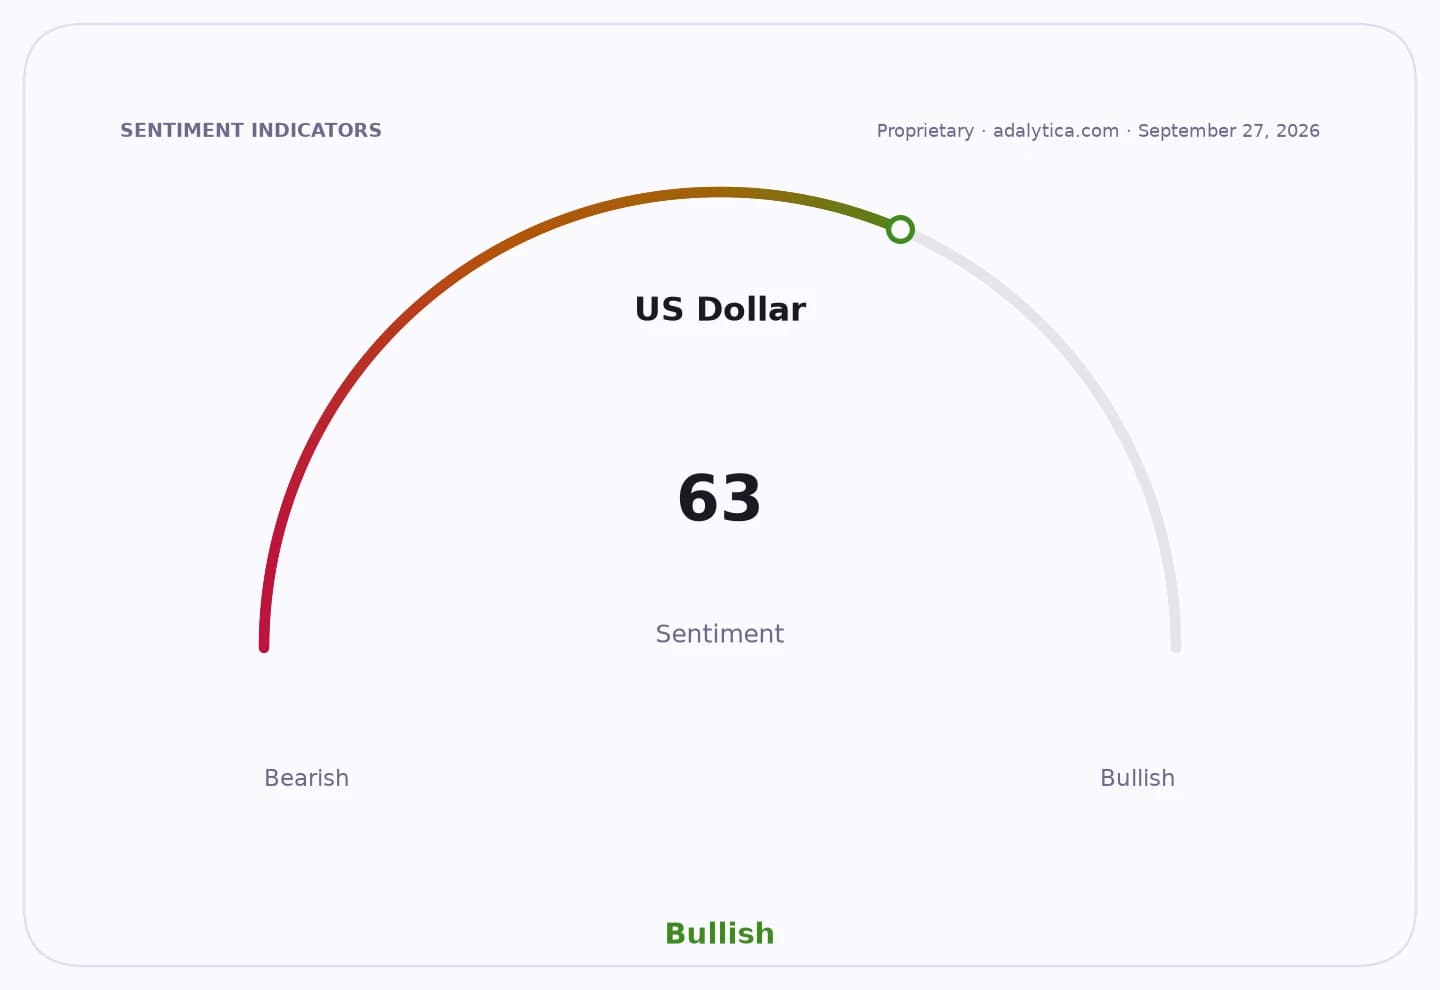
Sentiment IndicatorsⓘProprietary · adalytica.com · September 27, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
Indian assets have already started to reflect that shift. The India ETF, INDA, has slipped to $47.86 after briefly trading above $50 in late August, with its RSI readings pointing to near-term technical softness and the fund sitting below both its 50-day and 200-day moving averages. The rupee has also weakened to around 95.82 per dollar, underscoring that the market still sees external conditions as fragile even with crude easing.
For bond investors, the key question is not whether lower oil helps — it does — but whether it is enough to offset the drag from higher global rates. The 10-year U.S. Treasury yield has climbed to about 5.18%, raising the hurdle for emerging-market debt rallies and keeping foreign appetite selective. In that environment, India’s bond market is more likely to grind higher than stage a sharp repricing.
The inflation backdrop gives that view some support. U.S. consumer prices are still running at elevated levels, with the latest CPI reading above 334 on the index, while equity risk appetite remains firm. But for India, the more relevant point is that softer crude reduces the odds of a renewed inflation flare-up just as domestic borrowing needs remain heavy.
The near-term bull case for Indian bonds is straightforward: cheaper oil, a softer import bill and a better chance of policy stability. The bear case is equally clear: if U.S. yields remain elevated and Brent stabilizes rather than keeps falling, the rally could stall quickly. That leaves Indian government debt vulnerable to only a limited extension higher unless global rates relent as well.
| Entity | Gains | Losses |
|---|---|---|
| Indian government bonds | ▲Lower inflation pressure | ▼Limited upside if U.S. yields stay high |
| Indian consumers/importers | ▲Cheaper energy costs | ▼— |
| RBI / policymakers | ▲More room on inflation | ▼Less pressure to tighten, but still constrained |
| Oil producers / exporters | ▲— | ▼Softer crude pricing |