India’s finance minister is telling corporate bosses to do something far more important than chase scale: build the technology, patents and know-how that can lift productivity and margins for decades.
India Finance Minister Urges Higher R&D Spending
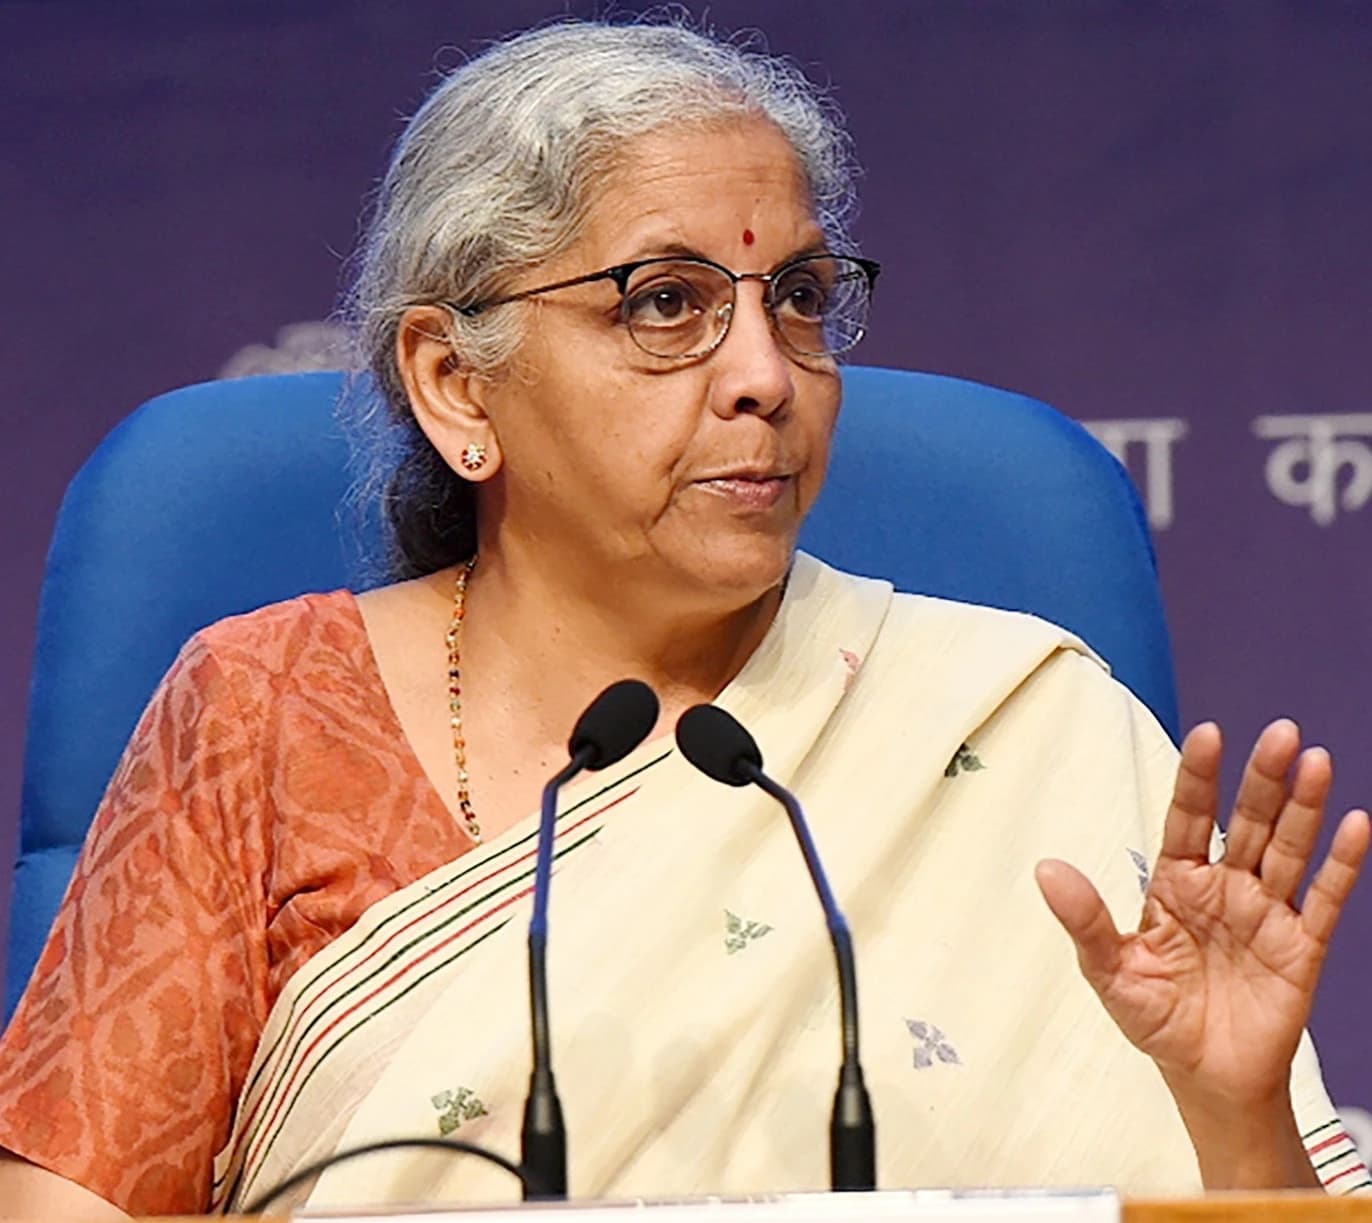
Nirmala Sitharaman’s call for Indian businesses to increase research and development spending marks a clear push to move the economy from a low-cost manufacturing story to an innovation story — the kind that creates higher-value exports, stronger brands and more durable companies. For investors, that matters because economies that compete on design, software and intellectual property tend to generate better returns on capital than those relying only on assembly and volume.
Sentiment IndicatorsⓘProprietary · adalytica.com · September 26, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
She put hard numbers behind the argument. India’s gross R&D spending is just 0.83% of GDP, far below the OECD average of 2.7%, China’s 2.6% and the US at 3.5%. The private sector accounts for 36% of India’s R&D spending, compared with more than 70% in leading advanced economies. In other words, India’s companies still underinvest in the very capabilities that usually drive long-term competitive advantage.
That is the real market takeaway. If Indian industry starts spending more on in-house innovation or university partnerships, the payoff could show up in better products, stronger pricing power, fewer defects and more resilient supply chains. Those are not abstract policy goals. They are the ingredients of a broader re-rating in quality, governance and profitability across sectors from manufacturing and industrials to software, electronics and pharmaceuticals.
The minister also linked innovation to a wider national agenda, saying India must become “imagined in India,” not just “made in India.” That language matters because it reflects a bigger economic shift underway: India wants to capture more value from each product by moving up the chain into design, engineering, software and patents, rather than leaving those gains to foreign licensors and original equipment owners.
That ambition fits with the government’s push to position India as a more resilient economy in a world of fractured trade and supply chains. Sitharaman’s message was not isolationist; it was that resilience should come from fiscal strength, domestic capacity and industrial scale. For long-term investors, that points to a country trying to build a deeper economic moat, not just faster growth.
Family-owned businesses and mid-sized firms were another focus, and for good reason. Many of India’s most promising companies are still run informally, with succession disputes and blurred lines between ownership and management. Professionalising those firms could be just as important as funding lab work, because innovation only compounds when governance is strong enough to support it.
The message for investors is straightforward: India’s next market winners may not be the companies that simply manufacture the most, but the ones that can invent, defend and scale differentiated products over time. The companies that spend on R&D, build institutions and treat quality as a discipline may deserve the highest attention. That makes this a story worth watching — and one long-term investors should keep on the watchlist.
| Entity | Gains | Losses |
|---|---|---|
| R&D-heavy Indian companies | ▲Higher margins, stronger moats | ▼Low-investment peers |
| Consumers and global buyers | ▲Better quality, more reliable products | ▼Cheap but undifferentiated suppliers |
| India’s economy | ▲Higher-value exports, productivity gains | ▼Assembly-led growth model |
| Family-run MSMEs without professional governance | ▲Long-term credibility if they reform | ▼Succession disputes, weak controls |