India’s services economy picked up in August, with the PMI rising to 54.1, a sign the country’s largest growth engine is still expanding even as conditions remain far from easy.
India Services PMI Rises to 54.1 in August
That matters because services are doing the heavy lifting for India’s economy at a time when manufacturers have slowed. The composite PMI held at 54.3, showing overall private-sector activity is still growing at a healthy clip, but the real story is that services helped offset a softer industrial backdrop. For investors, that points to continued support for GDP growth, corporate revenues and employment, even if the pace is not yet strong enough to call it a broad-based boom.
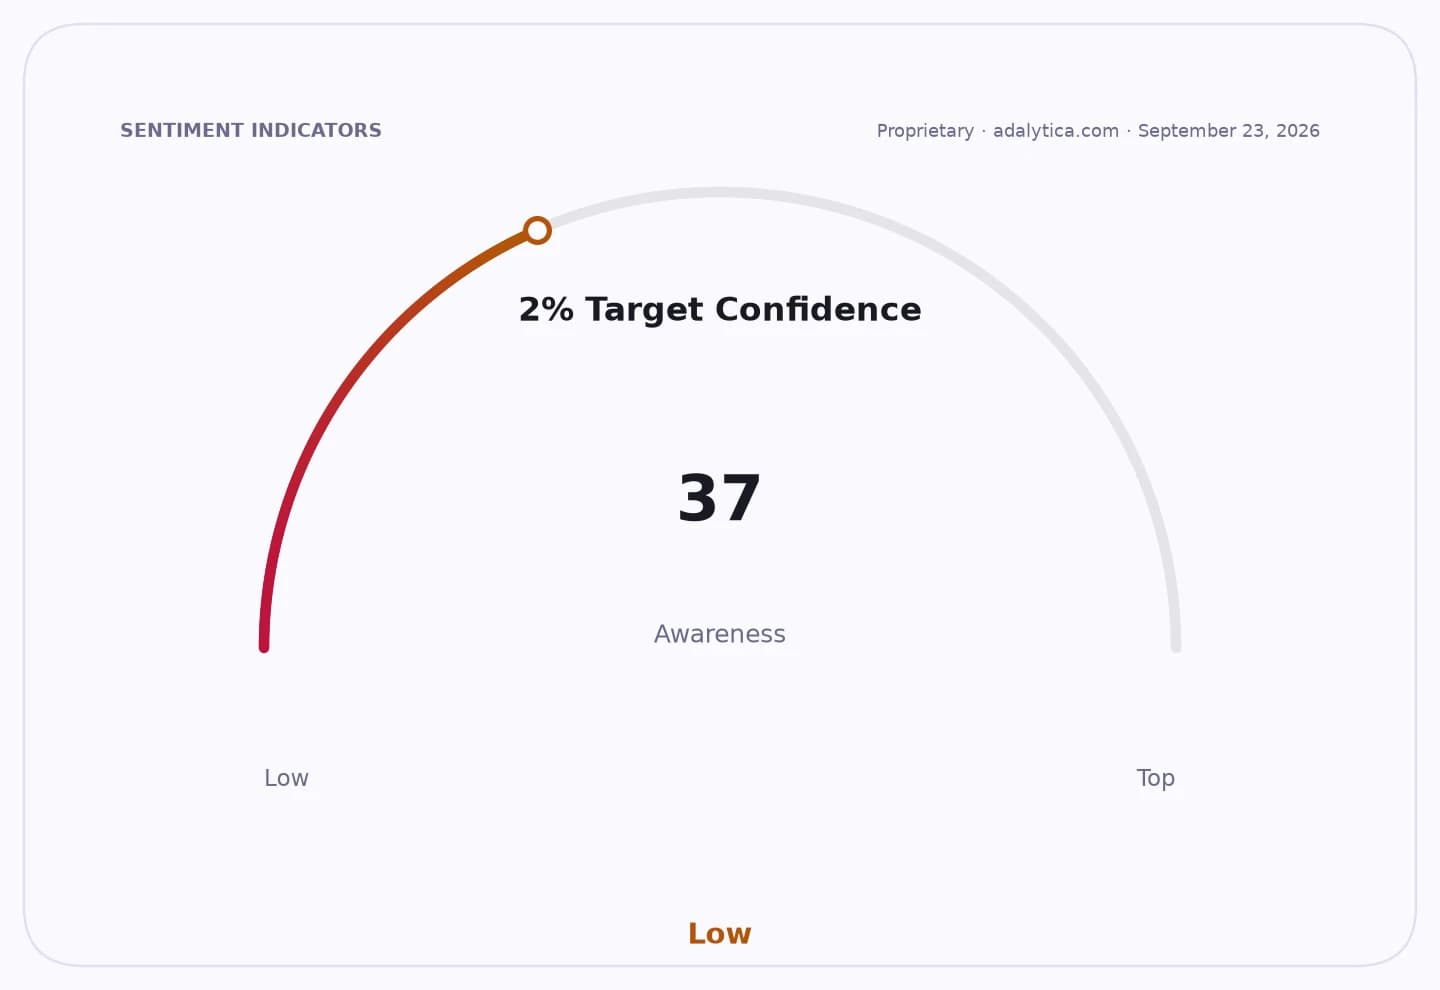
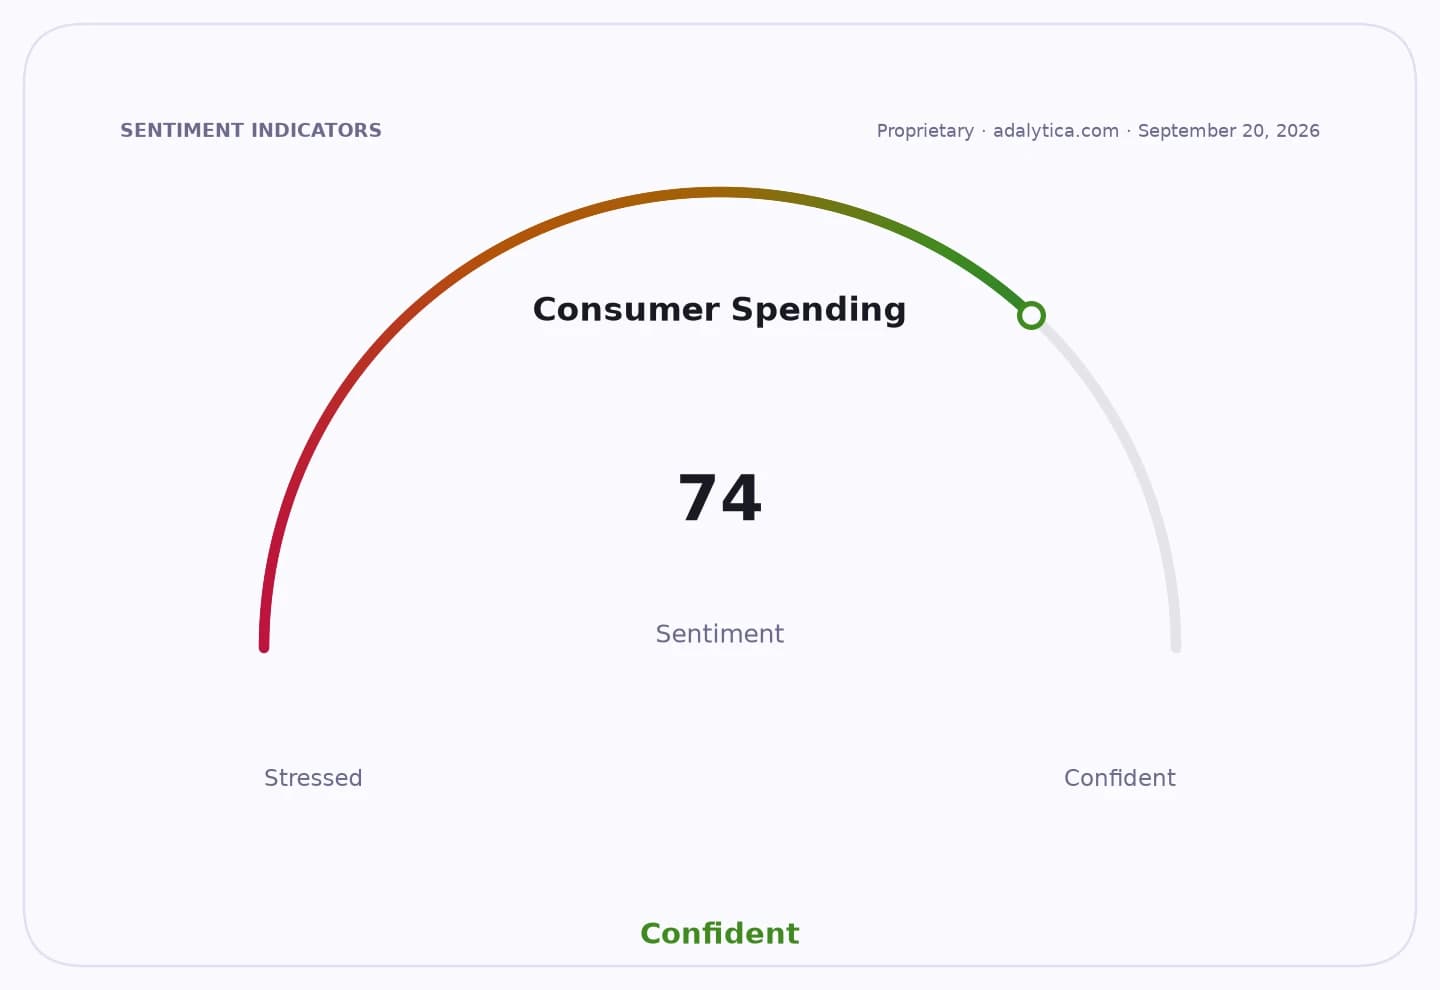
Sentiment IndicatorsⓘProprietary · adalytica.com · September 3, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The details are encouraging, but not spectacular. New business accelerated on the back of resilient export demand and marketing efforts, and employment climbed to a 15-month high. That suggests companies are still willing to hire, invest and chase demand, which is exactly what long-term investors want to see in an economy trying to build durable growth.
At the same time, this is not a clean upside surprise. The report said the expansion was still the second-weakest since March 2022 and slightly below the long-run average. Sales growth was also the second-slowest in nearly four and a half years, held back by tougher market conditions and softer client appetite in some service categories. In other words, India’s service sector is growing, but it is doing so in a more selective and uneven environment.
Inflation pressures are also creeping back into the picture. Input costs rose a little faster in August because of higher spending on digital platforms, electricity, materials, labour, marketing and regulatory requirements. That does not look like a full-blown inflation shock, but it does matter for margins. Companies with pricing power should be better placed than those competing on cost alone.
For equity investors, the most important takeaway is that India’s domestic demand story remains intact, and export-linked service firms are still finding opportunity abroad. That combination supports the case for staying invested in high-quality Indian businesses with strong balance sheets, recurring demand and room to compound earnings over years, not months.
The risk, as always, is that slower sales growth and rising costs eventually squeeze profitability. But for now, the August PMI report still points to an economy that is expanding, hiring and adapting — a constructive backdrop for patient investors who can look past the monthly noise.
| Entity | Gains | Losses |
|---|---|---|
| India services firms | ▲stronger demand, hiring | ▼margin pressure from costs |
| Export-oriented businesses | ▲resilient overseas orders | ▼weaker client appetite in some markets |
| Employees | ▲15-month high hiring | ▼inflation-linked cost strain |
| Margin-light competitors | ▲little | ▼firms with pricing power |