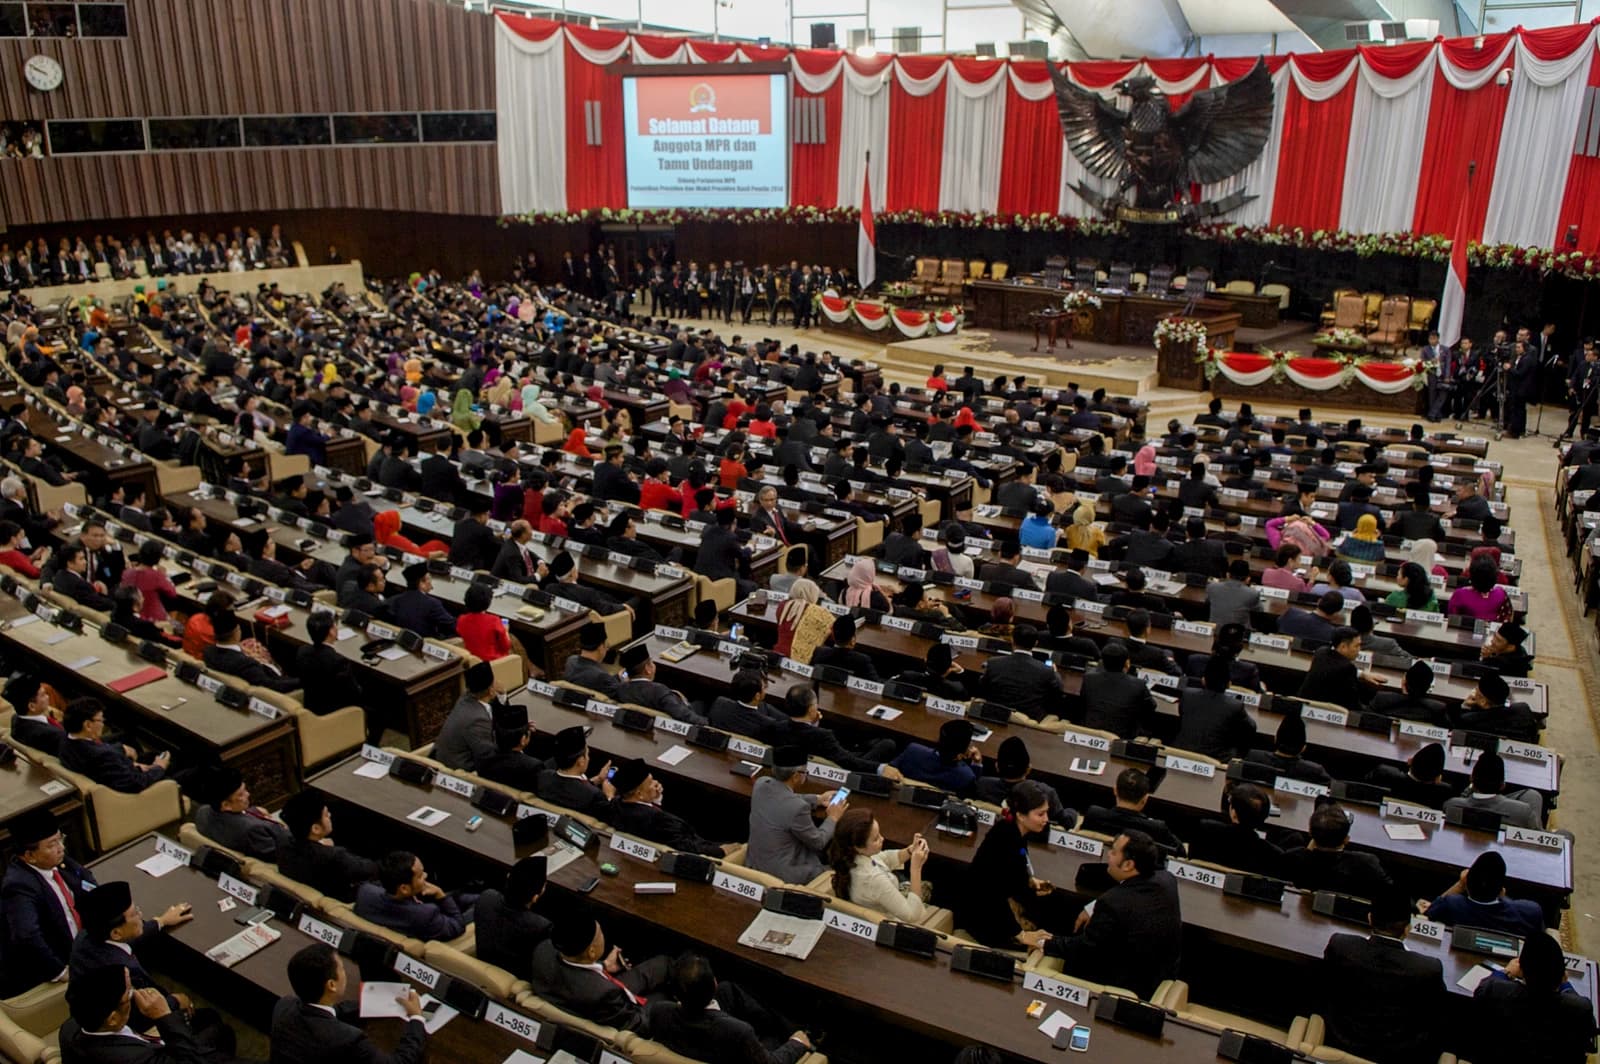
Indonesia’s village-cooperative push is running into the oldest rule in finance: the debt still has to be paid, even if the business is not yet working.
Indonesia village cooperatives face loan repayment risk
That is the key takeaway from a government program meant to build “koperasi desa merah putih” across the country. The cooperatives are not yet fully operating, but the loans used to set them up will begin coming due on Sept. 25, 2026, and Finance Minister Suahasil Nazara says the budget is ready. The ministry is waiting only for verification of the cooperatives and formal billing from the state-owned banks in Himbara that distributed the credit.
Sentiment IndicatorsⓘProprietary · adalytica.com · October 2, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
For investors, the important issue is not the headline politics of a rural development drive. It is whether a state-backed program can turn into a clean repayment stream or instead become a slow-moving fiscal obligation. If the cooperatives take longer than expected to generate cash flow, the burden shifts back to the government balance sheet, where it can crowd out other spending and complicate Indonesia’s broader fiscal management.
That matters because debt service is not optional. When public programs are financed through banks, the economic question is whether the underlying assets — in this case, village cooperatives — can earn enough to repay the funding. If they cannot, someone else pays. Here, that likely means the state, either directly through the budget or indirectly through pressure on the government-owned lenders that issued the credit.
The setup also exposes a familiar tension in policy lending. Governments often want to push money into productive activity before the revenue model is proven. That can accelerate development. But it also raises execution risk. A cooperative that has not yet started operating cannot yet produce the income needed to service debt, which makes the timing of repayments as important as the size of the loan itself.
For long-term investors, the bigger lesson is about discipline. Indonesia can support rural enterprise and still protect its finances, but only if rollout, verification and repayment are tightly managed. Markets tend to reward programs that create self-sustaining businesses, not liabilities that sit on the public ledger waiting for the budget to catch up.
Watch whether the cooperatives begin generating real cash flow before the repayment schedule tightens. That will determine whether this becomes a genuine development success story or simply another case of the government paying for growth before it arrives.
| Entity | Gains | Losses |
|---|---|---|
| Indonesian government | ▲Rural development optics | ▼Near-term fiscal flexibility |
| Village cooperatives | ▲Access to startup funding | ▼Pressure to repay before scaling |
| Himbara banks | ▲Loan disbursement volume | ▼Repayment uncertainty |
| Taxpayers | ▲Potential local economic activity | ▼Risk of ultimately backstopping the bill |