Enterprises are no longer asking whether industrial 5G works — they are asking whether it pays, and that shift is turning the market from a technology trial into a capital-allocation decision.
Industrial 5G ROI at Peel Ports
That matters because the next phase of industrial wireless networking will be won by vendors and service providers that can prove measurable gains in productivity, downtime, safety and asset utilization, not just faster connectivity. For investors, that raises the bar for equipment makers, software partners and telecom operators chasing factory, port and logistics contracts: the winners will be the ones that tie 5G to hard operating savings and repeatable deployment models.
Sentiment IndicatorsⓘProprietary · adalytica.com · October 4, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
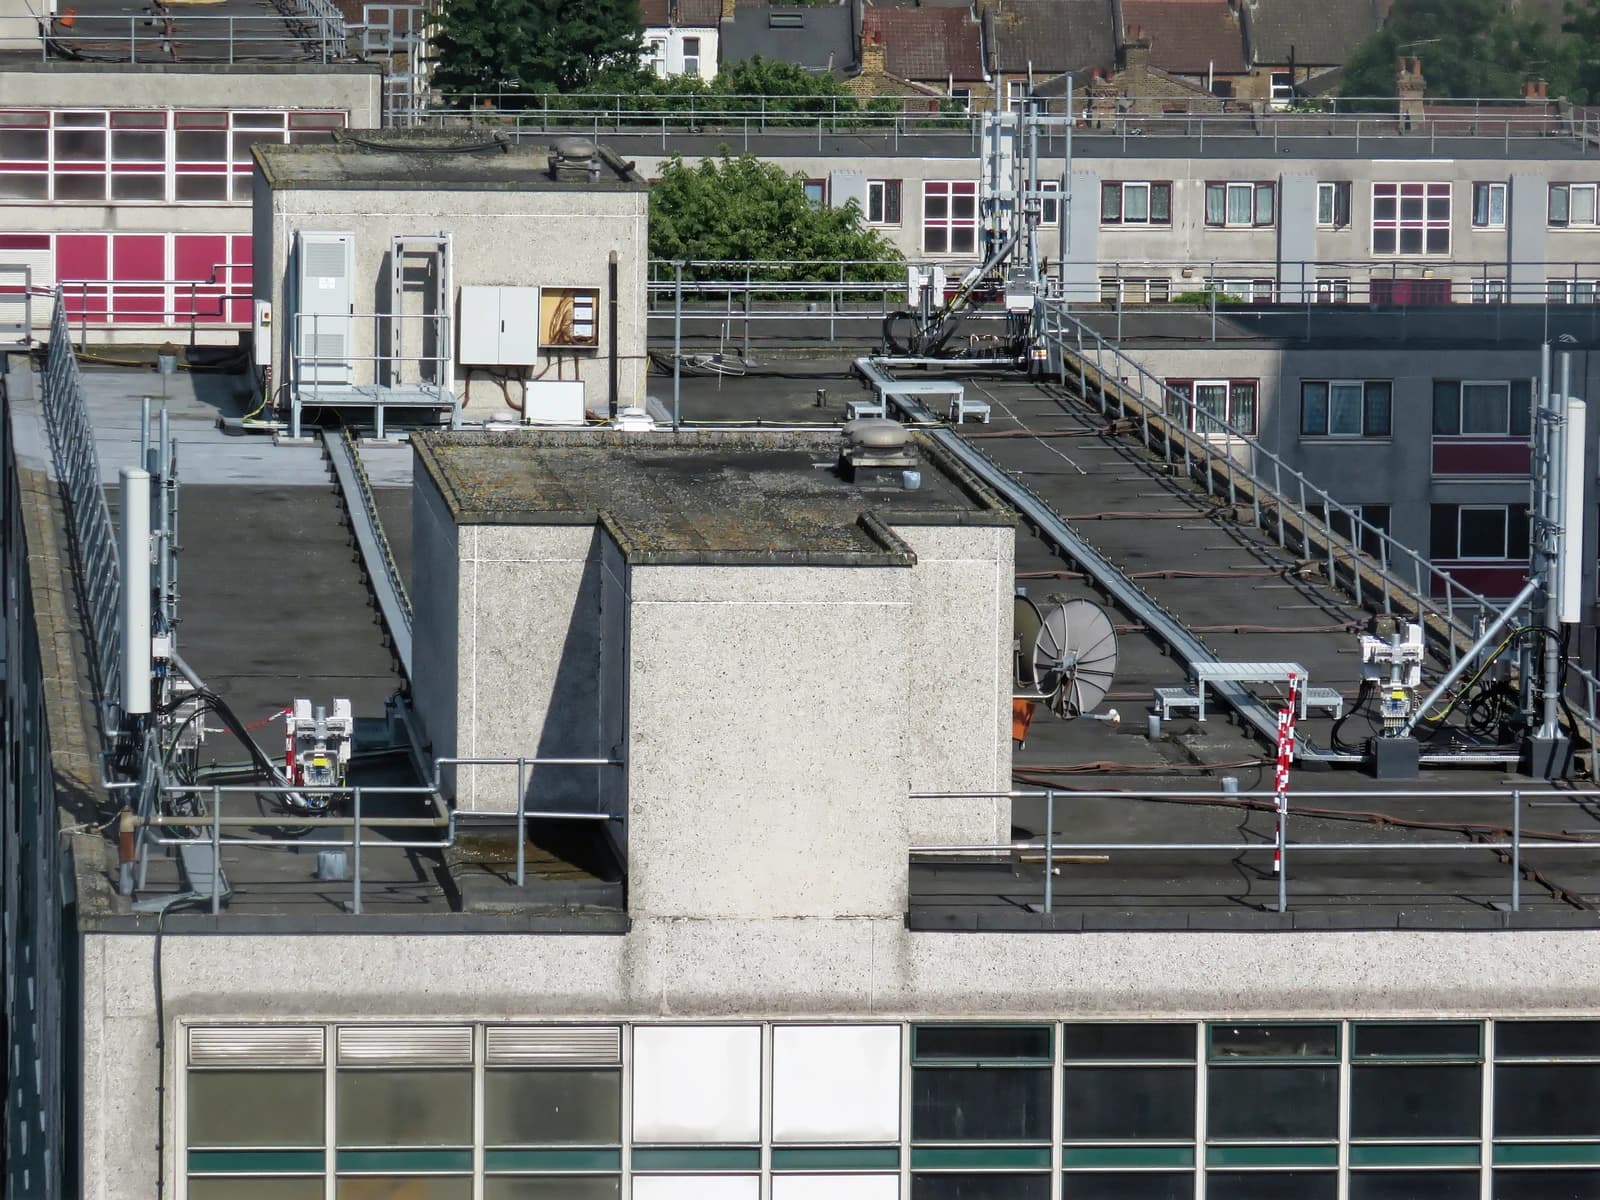
The clearest example in the data comes from Peel Ports Group, where the economics were quantified in plain terms. The company said its previous Wi-Fi setup could interrupt as much as 15% of operations as equipment moved between access points. After a private 5G proof of concept across about 80 acres, it connected four kinds of operational equipment with different throughput and latency needs, and within two weeks had confirmed the network met those requirements. A three-month analysis found about 49% of equipment movements had been unproductive.
That is the kind of result industrial buyers want: not a better network for its own sake, but a network that makes existing assets work harder. Peel Ports said improved connectivity supported its global pooling model, letting container movements be assigned dynamically and reducing unnecessary travel. It also said nearly 80 Wi-Fi access points could be replaced by four 5G radios, creating a payback period of less than eight months.
For long-term investors, that is the real story behind industrial 5G. The technology starts to matter financially when it cuts enough hardware, labor friction and downtime to justify the switch. Once that happens, the opportunity broadens beyond radios and core network gear into body-worn cameras, mobile CCTV, IoT devices, AI video analytics and safety systems that ride on the same infrastructure.
But the market is still sorting out how to scale these wins. IDC says enterprises need proof that performance holds up in real operating conditions, especially when 5G supports operational technology or other critical processes. The next hurdle is integration: legacy machines often need retrofits, gateways, device management and application links before they can use 5G at all. That means many pilots will stall unless vendors can package connectivity, devices and software into a complete industrial solution.
This is why commercial models are changing too. IDC says interest is rising in network-as-a-service and other subscription-based structures that let companies start with one use case before expanding. That should favor suppliers that can sell outcomes and flexibility rather than large upfront projects. It also means partnerships will matter more, as connectivity providers, device makers and application vendors have to work together if industrial customers want a single end-to-end system.
For investors, the lesson is straightforward: industrial 5G is entering the phase where adoption depends on proof, not promise. That usually slows the story in the short run, but it strengthens it over years if the economics keep holding up across ports, factories and transport networks. The companies that can repeatedly show quick paybacks, better asset use and lower operational risk deserve the most attention. Keep it on the watchlist, because measurable ROI is what turns a promising technology into a durable business.
| Entity | Gains | Losses |
|---|---|---|
| Industrial 5G vendors | ▲More repeatable sales | ▼Hype-driven demand |
| Enterprises | ▲Lower downtime, faster payback | ▼Upfront integration costs |
| Wi-Fi-heavy legacy setups | ▲None | ▼Replaced infrastructure |
| Investors in proven enablers | ▲Long-term compounding | ▼Pilot-only suppliers |