When insurers cut premiums below actuarial estimates, the real question is not whether the policy is cheap enough to win business, but whether the expected return justifies the capital tied up in the risk.
Insurers and underwriting returns on capital
That is the central argument in a growing debate over underwriting efficiency: premiums and loss ratios alone do not tell investors whether an insurer is creating value. What matters is how much capital a book of business consumes, and whether the return on that capital clears the firm’s cost of capital. In other words, underwriting is not merely about pricing risk; it is about deciding where shareholders’ capital should be deployed.
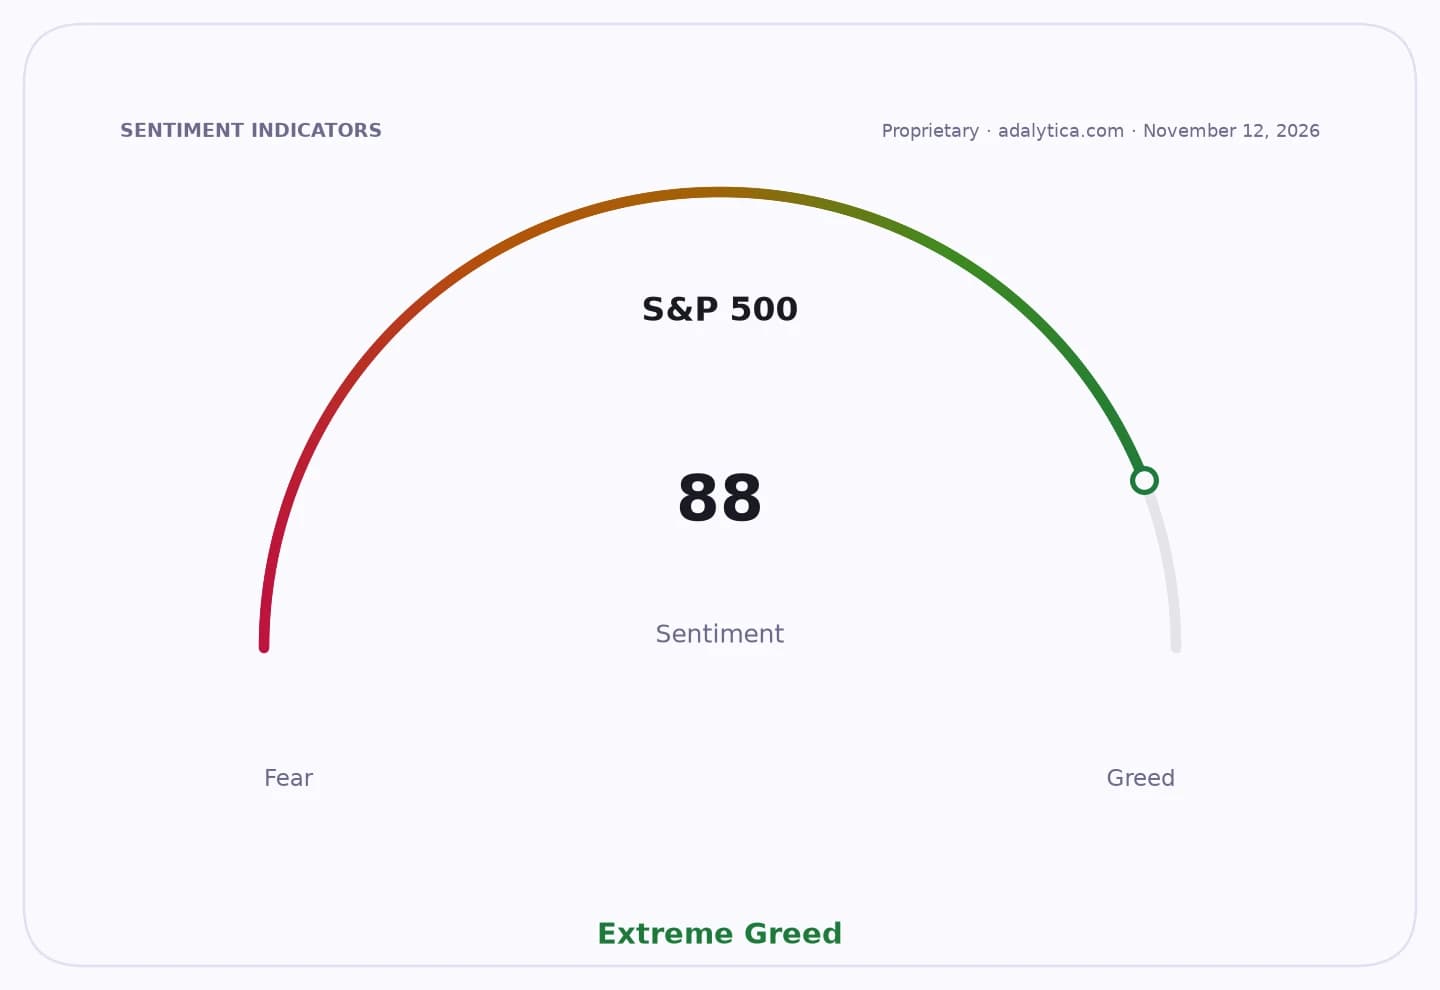
Sentiment Indicators
The distinction becomes economically important because a discount to technical price does not erase the underlying risk. If an insurer prices a policy at 92 when its model suggests 100, the missing 8 points do not disappear. They become an implicit investment decision, justified only if the insurer can point to offsetting value — retaining a key client, cross-selling other products, gaining access to a strategic market or improving long-term portfolio mix. If that value cannot be measured or defended, the discount is less a commercial strategy than a transfer of value from shareholders to policyholders.
That framing matters at a time when insurers face pressure to preserve growth in a slowing economy while still protecting margins. In a market where capital is finite and reinsurance, claims inflation and volatility all affect balance-sheet capacity, two books of business with identical accounting profits can produce very different economic outcomes. A business that looks attractive on margin may still be inferior if it requires disproportionately more economic capital. For investors, that means the relevant metric is not just premium growth, but return on capital after risk.
The logic also cuts the other way. Pricing above technical indications can be rational when a risk is opaque, concentration is high or the capital charge is elevated. In that case, the insurer is signaling that it wants more compensation for uncertainty and capital usage. The underwriter’s role is therefore not to follow the model mechanically, but to judge when a deviation from model price is an investment decision with an expected return above the cost of capital.
That is why the broader investment question is whether underwriting discipline is tightening or loosening. If firms are relaxing pricing to chase volume, they may be buying growth at the expense of returns. If they are holding the line, they may sacrifice near-term premium income but protect long-term franchise value. For shareholders, the difference shows up in combined ratios, capital efficiency and ultimately valuation multiples.
The debate now is less about whether insurers can write more business and more about whether they should. The best operators will be those that can prove a premium discount is a deliberate investment with measurable strategic payback, not an unpriced giveaway. In a capital-intensive industry, that distinction determines whether underwriting is a source of value creation or a hidden drain on equity.
| Entity | Gains | Losses |
|---|---|---|
| Insurers with disciplined underwriting | ▲Higher returns on capital | ▼Slower top-line growth |
| Insurers chasing premium volume | ▲More business now | ▼Lower capital efficiency |
| Policyholders / clients | ▲Better pricing terms | ▼Less underwriting leverage |
| Shareholders | ▲Capital preserved | ▼Value leakage if discounts lack payoff |