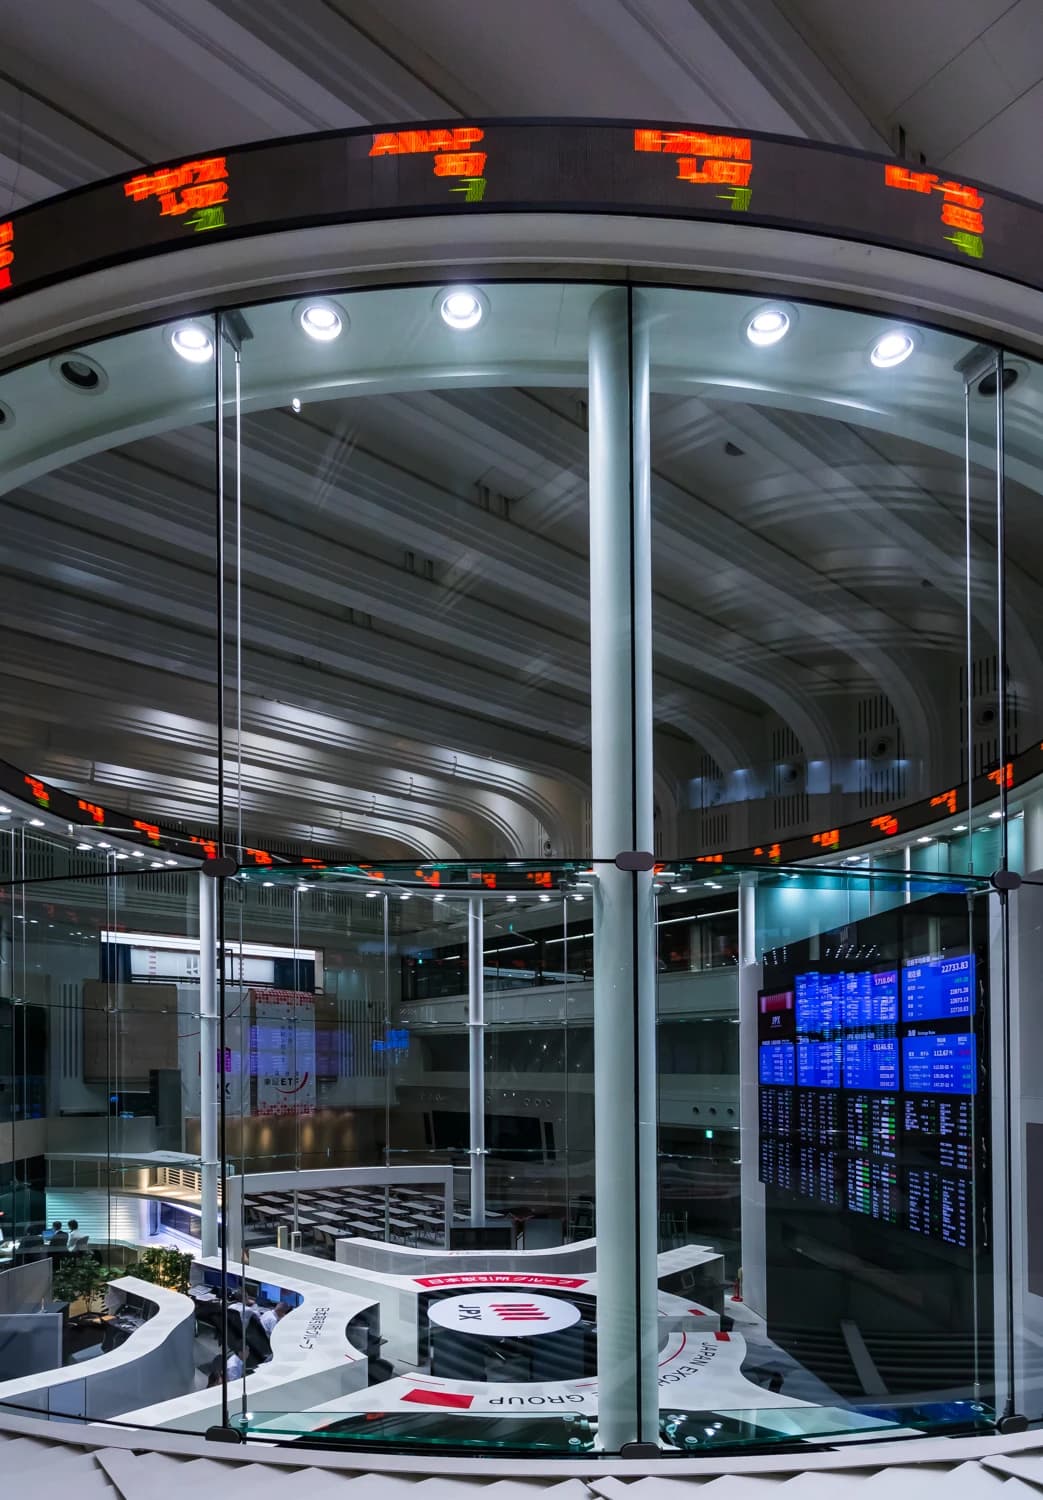
Japan’s government bond market caught a bid as investors looked for shelter from wobblier equity markets, pushing yields lower across the curve and underscoring how quickly risk appetite can spill into sovereign debt.
Japan JGB Yields Fall as Investors Buy Safety
The benchmark 10-year Japanese government bond yield slipped 1.5 basis points to 2.855%, while the 20-year yield fell 2.5 basis points to 3.755% and the 30-year yield eased to 4.030%. The five-year yield also edged down, reflecting broad buying in bonds as stocks came under pressure. Because bond prices move inversely to yields, the move shows demand strengthening for higher-quality assets.
Sentiment Indicators
That matters because Japan’s long end has become a key pressure point for global markets. Superlong JGBs are closely watched by pension funds and other institutional investors, and any shift in their appetite can ripple into funding costs, portfolio allocations and auction outcomes. Reuters said weak demand at a recent 20-year bond sale had already pushed that maturity’s yield higher on Wednesday, a reminder that supply-demand conditions can quickly overwhelm otherwise supportive safe-haven flows.
The trigger this time was not just domestic. Longer-dated U.S. Treasury yields eased overnight as oil prices retreated, helping global bond markets stabilize. Crude fell more than 1% after U.S. crude and fuel inventories rose by more than expected, reviving talk of a possible supply surplus. Lower oil prices tend to cool inflation expectations, which in turn supports bond prices and can make long-duration debt look more attractive.
For investors, the message is straightforward: when equity markets get choppy, Japanese sovereign debt can still serve as a refuge, especially for institutions looking for duration and relative stability. But the rally has limits. Analysts cited by Reuters said expectations for further Bank of Japan rate hikes, plus concerns about domestic supply and demand, could cap additional gains in JGBs. If the BOJ keeps tightening, yields may stay under upward pressure even if risk aversion persists.
That creates an important balancing act for long-term investors. The safer trade is not necessarily the best-performing one if policy normalization continues and supply remains heavy. In other words, the bond market’s current calm may be temporary, but it still tells you something useful: when stocks wobble, capital is moving back toward safety, and Japanese government debt is one of the first places it tends to go. Worth watching for anyone allocating across global rates, equities and currency-sensitive assets.
| Entity | Gains | Losses |
|---|---|---|
| JGB buyers | ▲Safer prices | ▼Lower yields |
| Japanese government | ▲Easier funding tone | ▼Higher borrowing costs if yields rebound |
| Equity investors | ▲Defensive hedges | ▼Risk-asset exposure |
| BOJ hawks | ▲Stronger case for tightening | ▼Bond bulls and duration buyers |