KAsset is trying to turn one of retirement investing’s hardest problems into a product people can actually own: how to generate cash flow without abandoning long-term growth.
KAsset Launches K-WPLIFETIME Retirement Fund
That is the real pitch behind K-WPLIFETIME, the new fund from Kasikorn Asset Management that will open its initial public offering from Oct. 20 to 26, with J.P. Morgan Asset Management adding its global investing know-how. For Thai investors, the launch lands at a moment when the retirement math is getting tougher, not easier. People are living longer, healthcare costs are rising and inflation keeps eroding purchasing power. A portfolio built only to “save enough” can still fail if the money runs out too soon.
Sentiment IndicatorsⓘProprietary · adalytica.com · October 23, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The fund’s structure is designed around that longevity risk. KAsset says it will use a flexible allocation across high-quality bonds, quality equities, dividend stocks and REITs, in Thailand and overseas, with the goal of balancing income today and growth for tomorrow. It will also use automatic redemption payments to help create a cash stream in retirement, rather than forcing investors to sell holdings at the wrong time.
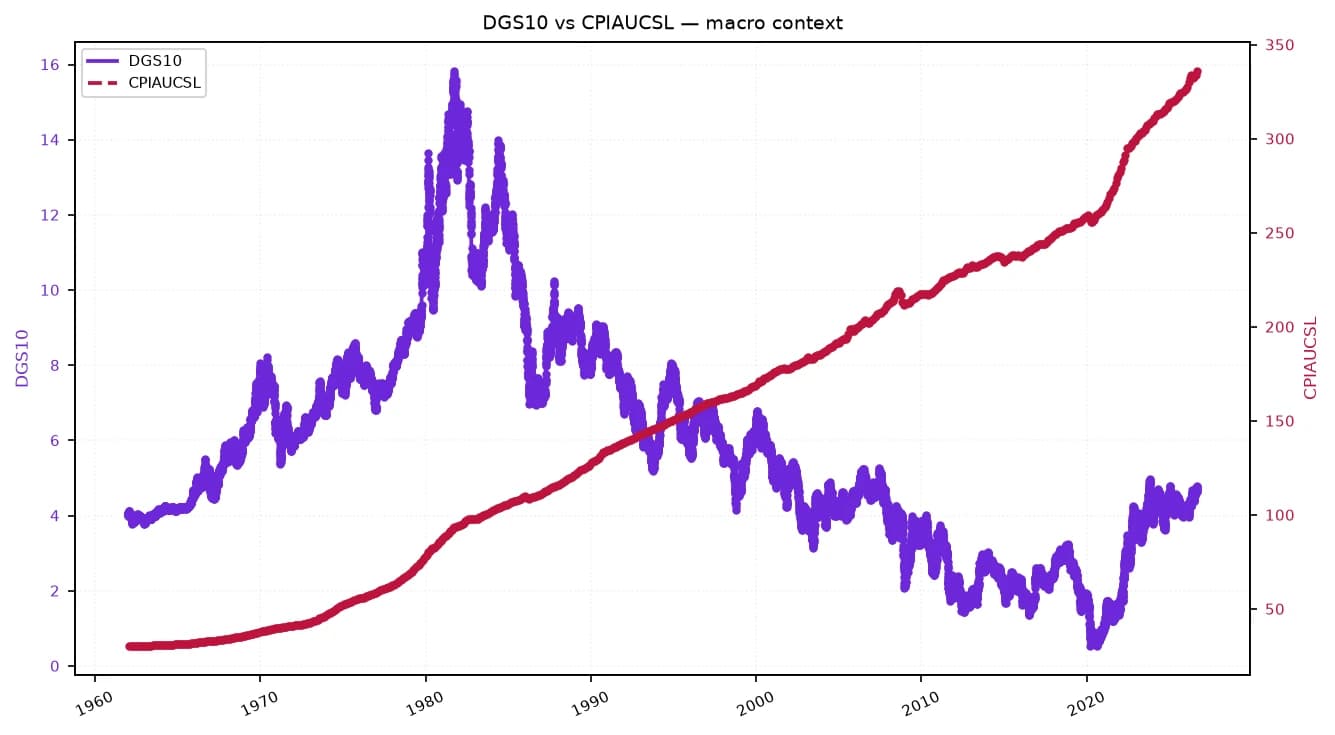
That matters economically because retirement investing is shifting from a pure accumulation game to an income-management game. In practical terms, the challenge is no longer just building a nest egg; it is preserving real spending power over decades. With U.S. inflation still running above where many retirees would like it to be, the 10-year Treasury yield around 5.1% and the U.S. unemployment rate near 4.1%, the global backdrop is still one where higher living costs and uneven growth can punish complacent savers. For long-term investors, that makes products built around cash flow and resilience more relevant than ever.
The partnership with J.P. Morgan gives the fund credibility in a crowded asset-management market. J.P. Morgan’s own shares have held up well, with the stock trading around $336 recently, above both its 50-day and 200-day moving averages, a sign the market still values its scale and earnings power. For KAsset, the appeal is less about chasing a hot theme and more about importing a proven investment framework into a local retirement solution tailored for Thai investors.
It is also a reminder that the mutual fund industry is increasingly competing on outcome design, not just product shelf space. Investors are asking a simpler question: can this fund help me pay bills in retirement without forcing me to sell after a market drop? That is where dividend payers, REITs and quality fixed income can matter over the long run, especially for savers who are years away from retirement today but want a portfolio that can endure through it.
There are risks, of course. Income-focused portfolios can still lose value, and automatic payouts do not eliminate market volatility or inflation. The mix of assets matters, as does the discipline behind rebalancing and risk control. But for investors thinking in 3 to 10 years or longer, the bigger story is that retirement products are becoming more sophisticated because the old assumptions no longer work.
If KAsset can deliver a fund that protects purchasing power while still growing capital, K-WPLIFETIME could become a useful template for how Asian asset managers compete for the retirement dollar. It is worth watching for investors who want diversified, income-oriented exposure with a long-term horizon.
| Entity | Gains | Losses |
|---|---|---|
| KAsset | ▲New retirement product flow | ▼Higher responsibility to deliver returns |
| J.P. Morgan Asset Management | ▲Distribution reach in Thailand | ▼Limited if fund underperforms |
| Thai retirees | ▲More income-focused options | ▼Less protection if inflation stays high |
| Traditional cash savers | ▲— | ▼Purchasing power erosion |