Japanese equities are being whipped around by the fastest volatility in 18 years, with the AI-linked trade doing most of the damage as a sharp slide in Kioxia dragged sentiment across the sector and spilled into U.S. peer Sandisk.
Kioxia Slide Hits Japanese AI Trade
That matters because the move is not just a single-stock event: it shows how crowded positioning in a handful of semiconductor and storage names can turn a theme trade into a market-wide risk-off episode. The Nikkei’s drop of more than 3% underscored how quickly investors are reassessing a rally built on AI optimism, even as rising bond yields and Middle East tensions added a macro layer of stress.
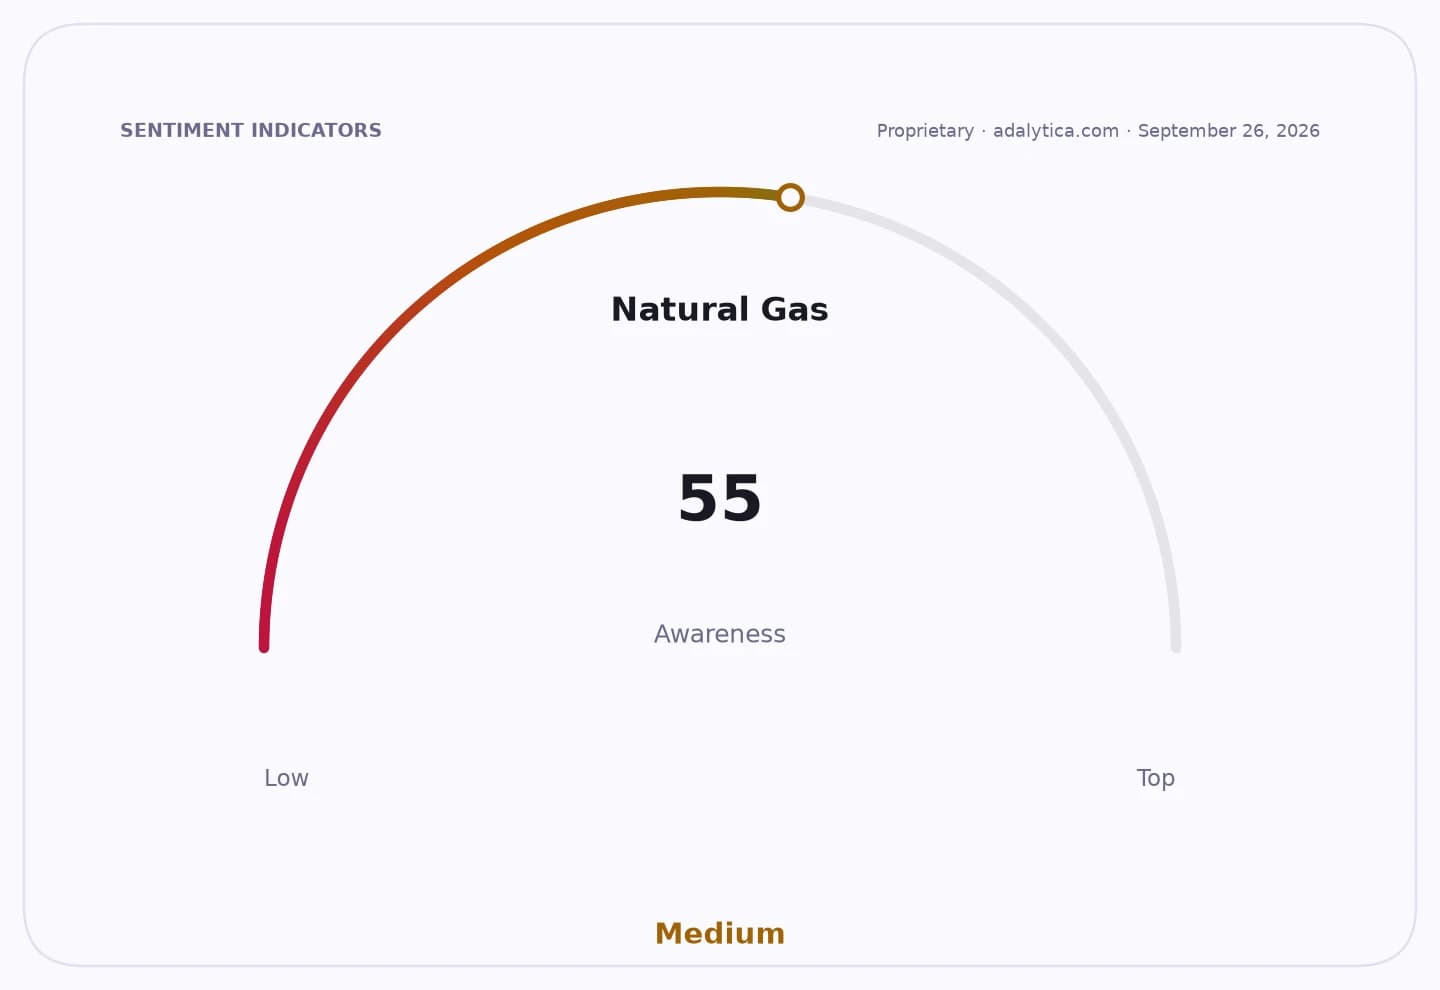
Sentiment IndicatorsⓘProprietary · adalytica.com · August 19, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
Kioxia’s 12% fall was the clearest trigger. Storage chips have become one of the market’s preferred ways to express exposure to AI spending, but they are also highly vulnerable to de-rating when investors question how much of the future demand is already priced in. The contagion to Sandisk, which dropped sharply in New York, suggests traders are treating the group as a single crowded trade rather than a set of differentiated businesses.
The technical picture in Sandisk points to that same instability. The stock has been trading far above its 50-day and 200-day moving averages this summer, but recent swings have left momentum indicators weakening even after a violent run-up. That kind of price action often invites profit-taking from fast money and forces systematic funds to cut exposure when volatility jumps.
For Japan, the stakes go beyond chip stocks. Higher global yields are complicating valuations for cyclical and growth shares at the same time the yen remains under pressure and the South Korean won strengthens, reflecting a widening policy divergence in Asia. Traders are therefore having to price in not just earnings risk, but also currency, funding and rate risk in a market that had been attracting overseas money on the back of corporate reforms and AI enthusiasm.
The bull case is that this is still a correction inside a longer structural shift: Japanese tech and manufacturing names remain leveraged to global AI capex, and any pullback could create entry points for investors willing to look through short-term turbulence. The bear case is that the market is discovering how much of the AI story has been financed by momentum rather than fundamentals, leaving storage and chip names vulnerable if bond yields keep climbing or if geopolitical shocks trigger another de-risking wave.
Adalytica’s Japanese yen trade signals were neutral, but the broader safe-haven and dollar gauges point to persistent caution rather than outright panic. That suggests investors are not abandoning risk assets wholesale; they are rotating out of the most crowded expressions of the AI trade and demanding a higher risk premium for equities that had been priced for perfection.
| Entity | Gains | Losses |
|---|---|---|
| Cash-rich value stocks | ▲Lower entry valuations | ▼Momentum names |
| AI chip/storage bulls | ▲Long-term AI demand exposure | ▼Short-term crowded trades |
| Sandisk/Kioxia rivals | ▲Relative share gains | ▼Kioxia, Sandisk holders |
| Yen bears | ▲Policy divergence trade | ▼Japanese importers and equities |