Korea Zinc’s third-quarter operating profit is expected to fall sharply from the prior quarter as weaker gold and silver prices, a softer won and lower smelting fees squeeze one of Asia’s most diversified metals refiners.
Korea Zinc Q3 profit seen falling on weaker bullion
The market is looking for operating profit of 388.8 billion won, down 33.8% from the second quarter and below the 446.8 billion won consensus, according to Meritz Securities. That would still be up 42.2% from a year earlier, but the more important signal for investors is that Korea Zinc’s earnings remain highly exposed to swings in precious metals and foreign exchange, not just zinc.
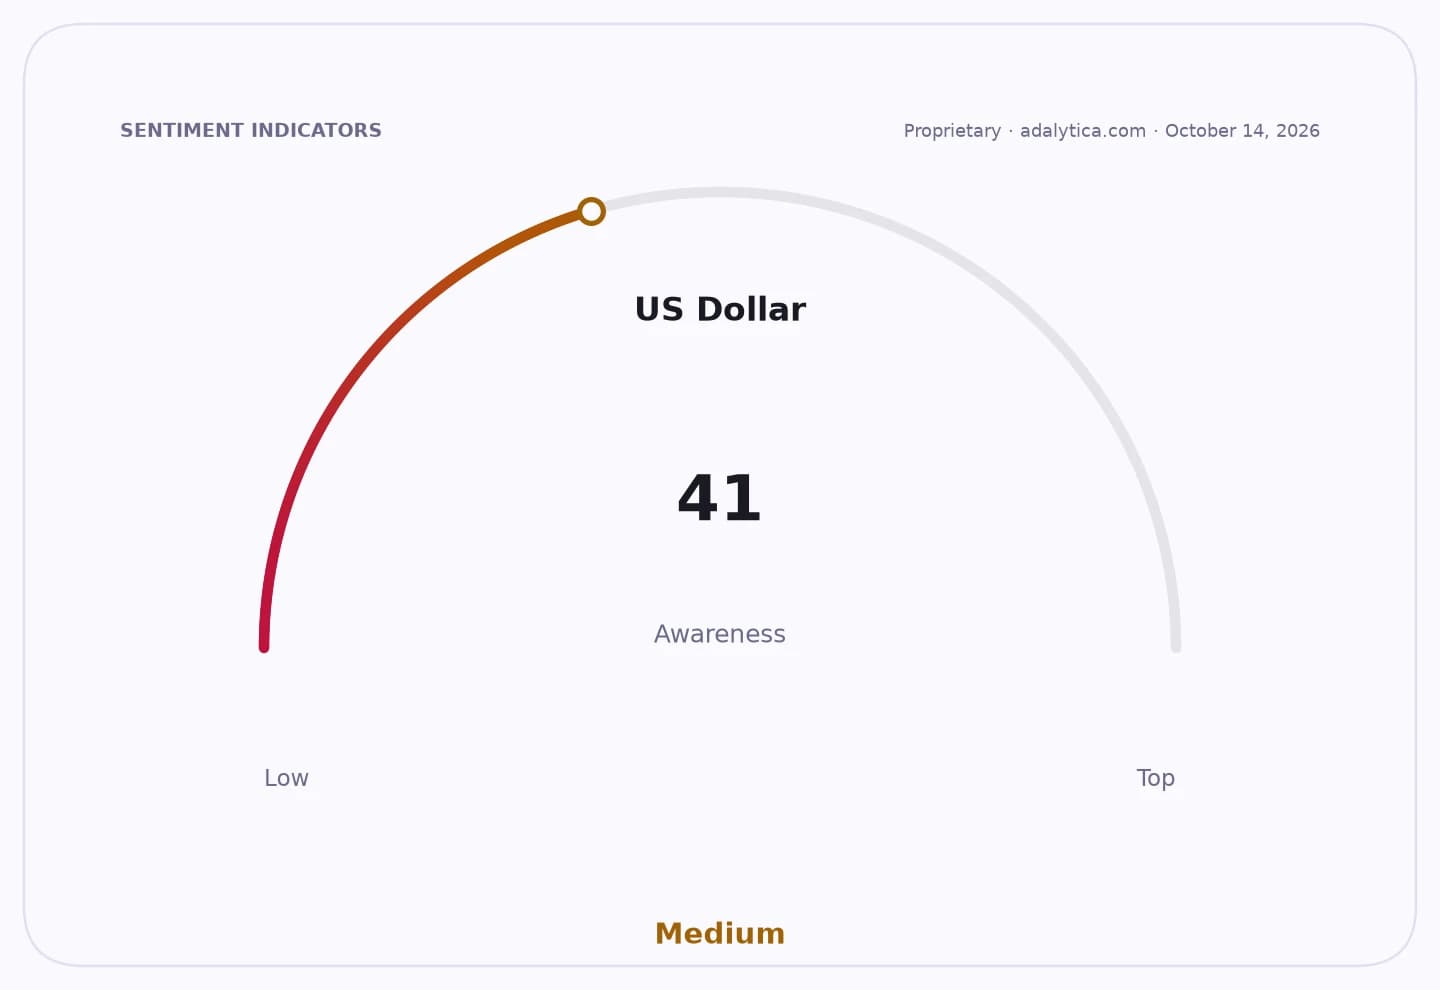
Sentiment IndicatorsⓘProprietary · adalytica.com · October 12, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
That matters because Korea Zinc is not a simple zinc processor. Its business model depends on recovering gold, silver, copper, sulfuric acid and rare metals as byproducts while treating zinc and lead concentrates. When those byproducts weaken, the company’s earnings cushion thins fast. This quarter, gold in won terms fell to about 6.06 million won per troy ounce from 6.77 million won in the second quarter and 7.13 million won in the first, while silver dropped to 94,000 won from 115,000 won a quarter earlier.
The won’s decline against the dollar also works through the income statement. Korea Zinc books much of its metal sales and byproduct recovery in dollar terms, so a softer dollar/ won rate lowers translated revenue for gold, silver, zinc, lead, rare metals and sulfuric acid. At the same time, zinc treatment charges fell, squeezing smelting margins just as a delay in ramping up its dry copper facility added another drag.
For investors, the key takeaway is that Korea Zinc’s earnings are entering a cyclical inflection point where metal mix matters more than volume. A company that can look exposed on headline zinc spreads can still outperform when precious metals and copper byproducts are strong — and underperform quickly when they are not. That makes the stock a leveraged way to express a view on bullion, industrial metals and the won, all at once.
Meritz expects the third quarter to be the low point, with profit improving in the fourth quarter as the pace of metal price declines eases. That sets up the next catalyst: if gold and silver stabilize and the currency stops moving against exporters, Korea Zinc’s earnings rebound could arrive faster than the market is pricing in. For now, the pullback in bullion prices is the story — and the market should treat Korea Zinc as a byproduct-driven metal play, not just a zinc refiner.
| Entity | Gains | Losses |
|---|---|---|
| Korea Zinc | ▲byproduct recovery upside | ▼lower 3Q profit |
| Gold and silver buyers | ▲cheaper input costs | ▼weaker metal prices |
| Smelter rivals with less byproduct exposure | ▲steadier margins | ▼less earnings leverage |
| Investors in bullion-sensitive miners | ▲fourth-quarter rebound setup | ▼near-term earnings disappointment |