Copper may still be trading near record-high levels, but for LS MnM the real story is the collapse in smelting economics: treatment charges have gone negative in China’s spot market, sulfuric acid prices are falling, and a key copper miner in Chile is moving closer to labor disruption. That combination puts the South Korean smelter’s second-half profitability at risk even after a blockbuster first half.
LS MnM Faces Smelting Margin Pressure on Low TCs
The market is underestimating how quickly a copper rally can stop helping smelters once ore becomes scarce. LS MnM does not simply buy and sell copper; it turns concentrate into refined metal and depends on treatment charges, by-product credits and contract timing to make money. When concentrate supply tightens, miners gain bargaining power, smelters absorb the pressure and spot TC can slide below zero — exactly the environment now developing in China.
Sentiment IndicatorsⓘProprietary · adalytica.com · October 4, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
Shanghai Metals Market’s China import concentrate index fell to minus $231.68 a dry metric ton on Sept. 30, widening the negative gap by $171.29 from mid-March. The September average also weakened versus August. That does not automatically determine LS MnM’s actual contract terms, but it is a clear warning that the negotiating backdrop has deteriorated just as 2026 benchmark TC was set at zero, down from $21.25 for 2025. In other words, the industry has moved from weak pricing to no pricing cushion at all.
That matters because the old playbook — higher copper prices equal better smelter profits — is breaking down. LME copper has climbed to around $14,465.5 a ton, but smelters still have to secure feedstock before they can benefit from stronger metal prices. If they pay up for concentrate, the upside in refined copper is partly or fully offset. For investors, that makes earnings quality far more important than headline copper prices.
The second pressure point is by-products. Sulfuric acid, which is produced in the smelting process, has retreated from a April peak of 1,660.5 yuan a ton in China to 1,218.5 yuan by Sept. 30, a drop of about 26.6%. Gold, silver and acid sales helped LS MnM deliver first-half operating profit of 365.3 billion won, up 427% from a year earlier, but those supports are now less reliable. If TC keeps falling while acid softens, the company’s margin structure gets squeezed from both sides.
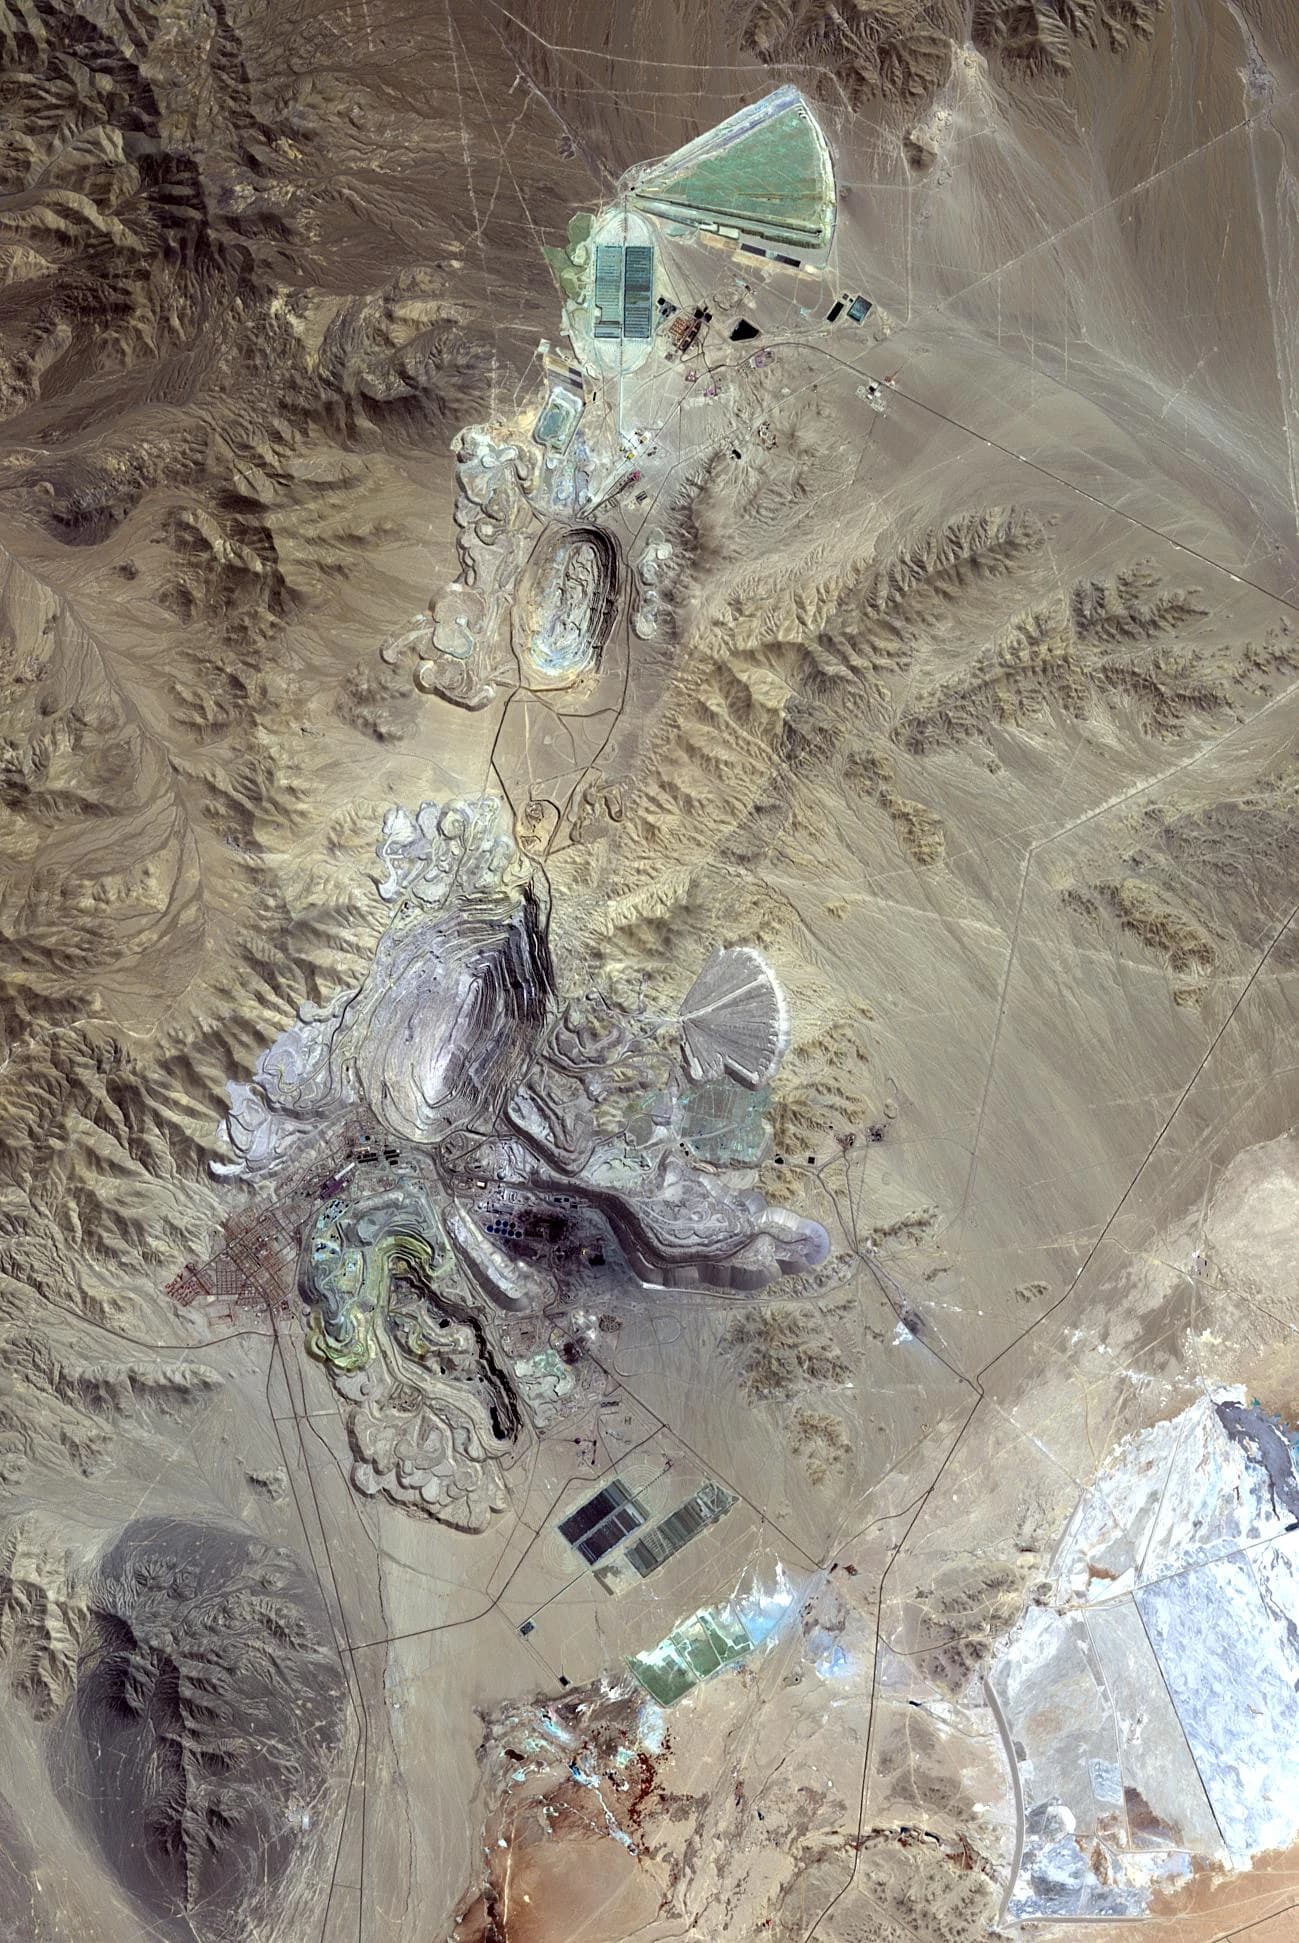
Supply risk is also rising. LS MnM buys concentrate from BHP’s Escondida mine in Chile, where supervisor unions have already rejected BHP’s final contract offer and 95% of voters backed a strike. A strike is not yet certain, but the mandatory government mediation period has begun, and any prolonged disruption would tighten concentrate supply further. That would strengthen miners’ leverage and likely keep TC under pressure across the market.
For investors, the key takeaway is that this is no longer just a copper-price story. It is a concentrate shortage story, a contract-renegotiation story and a by-product reset story. That is why the best exposure is not simply to copper itself, but to the parts of the value chain with pricing power and resource control. Miners with low-cost production and reserve depth can still capture the upside, while smelters without secure long-term feedstock face margin compression.
I believe the market is still pricing LS MnM as if high copper prices alone will carry earnings into the second half. The opposite is more likely: the next catalyst is not a further copper rally, but whether concentrate tightness and Escondida labor tensions force another round of weaker smelter economics. If you want copper exposure, favor the asset owners and integrated producers. If you own smelters, be selective and demand proof that contract terms, not spot conditions, will protect margins.
| Entity | Gains | Losses |
|---|---|---|
| Copper miners | ▲Higher bargaining power | ▼None |
| Smelters like LS MnM | ▲Limited upside from copper prices | ▼Negative TC and margin squeeze |
| BHP / Escondida | ▲Tighter supply leverage | ▼Strike risk and labor disruption |
| Copper bulls | ▲Scarcity-driven price support | ▼Smelter profit dilution |