Microsoft’s latest results reinforce a simple investing lesson: in AI, scale is not enough unless it can still produce cash. The company remains one of the clearest beneficiaries of enterprise AI spending, but it is also the rare hyperscaler that is generating positive free cash flow while funding the enormous infrastructure buildout needed to stay competitive.
Microsoft free cash flow stays positive amid AI spend
That distinction matters because the AI boom is no longer just about excitement or revenue growth. Investors are starting to ask a harder question: which companies can turn all that capital spending into durable returns? Microsoft’s ability to keep free cash flow positive while rivals continue pouring billions into data centers, chips and power gives it a sturdier financial profile than many of its mega-cap peers.
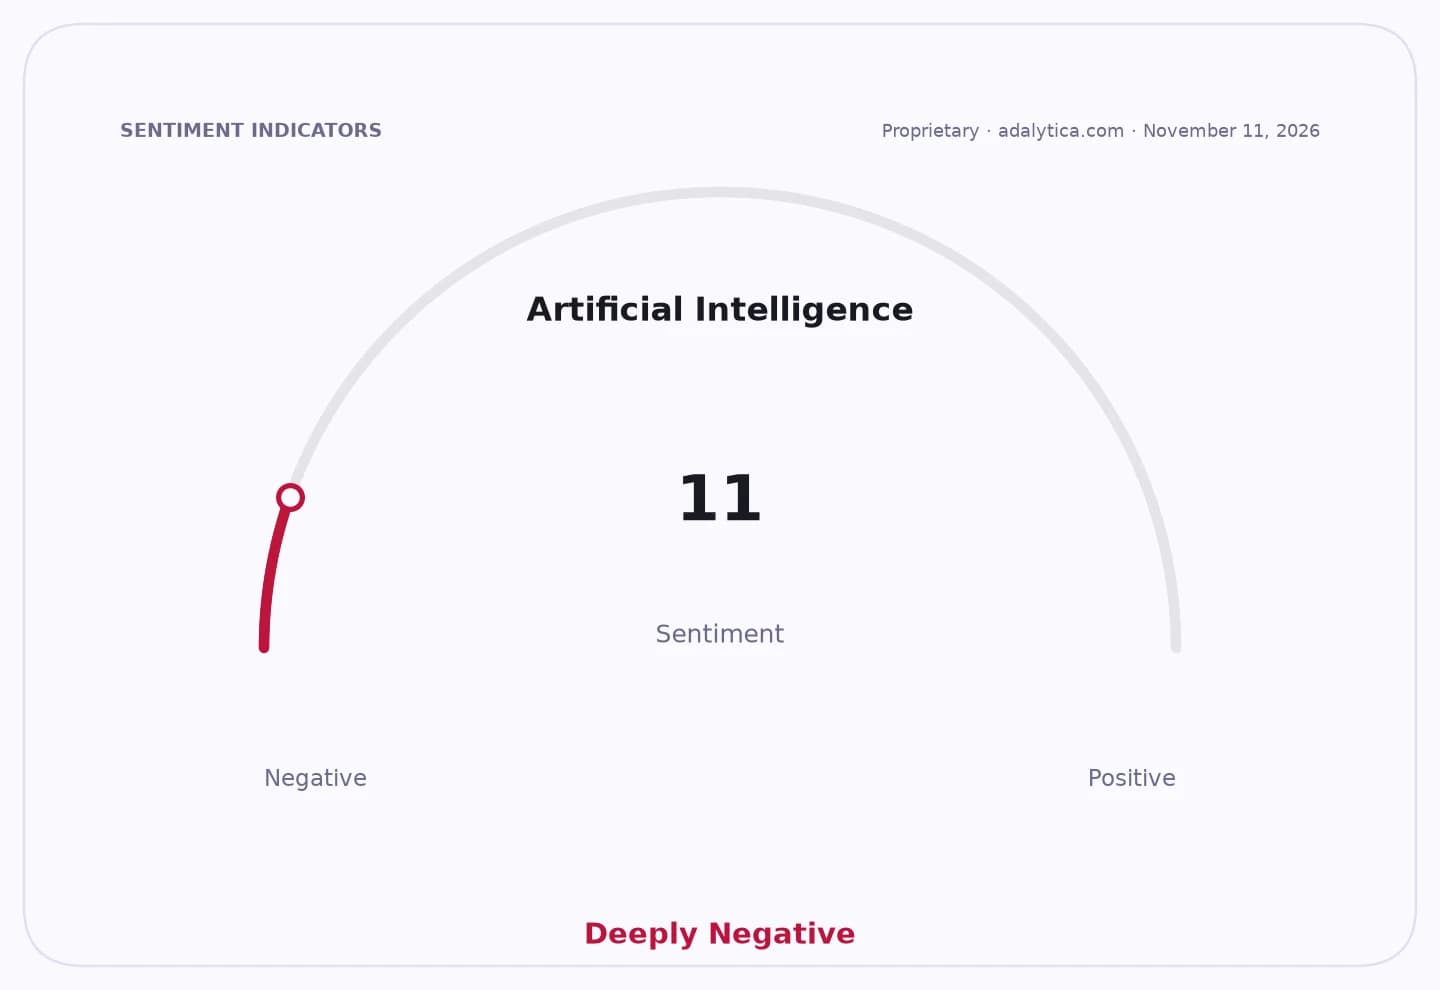
Sentiment Indicators
The contrast is especially important against the backdrop of the broader AI arms race. Nvidia has been crushed in recent sessions, with the stock sliding toward its 200-day moving average and its relative strength fading, even as demand for accelerators remains strong. Amazon has also been spending heavily to support AWS, with capital expenditures surging as it races to build out cloud and AI capacity. Microsoft, by comparison, is better able to fund its ambitions without leaning as hard on outside capital or stretching its balance sheet.
That is why the stock can stay resilient even when the market’s mood turns quickly. Microsoft shares have traded around their 50-day moving average in recent sessions, but the long-term trend remains intact, with the stock still well above its 200-day moving average. Technicals matter less than fundamentals over a five-year horizon, but they often reflect the same story: businesses that keep compounding cash tend to recover faster when sentiment swings.
Microsoft Corp
The market’s mixed reaction around AI also makes Microsoft’s position more valuable. Adalytica’s Microsoft Earnings Sentiment gauge has been elevated, though it has pulled back from recent highs, while its AI sentiment snapshot remains stuck in extreme fear. That tells you the crowd is still nervous about whether the AI trade can justify the spending. Microsoft’s answer, at least for now, is that it can keep investing and still throw off cash.
Investors should not ignore the risks. If AI monetization slows, or if capital spending rises faster than returns, even the strongest hyperscalers could see margin pressure. A downgrade on the stock may reflect that reality. But for long-term investors, the key takeaway is more constructive: Microsoft is one of the few AI giants showing that infrastructure intensity does not automatically mean weak financial quality.
In other words, the company is not just building the AI economy — it is helping prove which business models can survive in it. For patient investors who want exposure to AI without betting on speculative cash burn, Microsoft remains one of the most compelling names to watch, and a stock worth holding for years rather than months.
| Entity | Gains | Losses |
|---|---|---|
| Microsoft | ▲AI scale with positive free cash flow | ▼Higher capex scrutiny |
| Nvidia | ▲AI demand narrative | ▼Recent share-price momentum |
| Amazon AWS | ▲Cloud and AI buildout | ▼Near-term capital intensity |
| Long-term investors | ▲Durable compounding candidate | ▼Faster upside elsewhere |