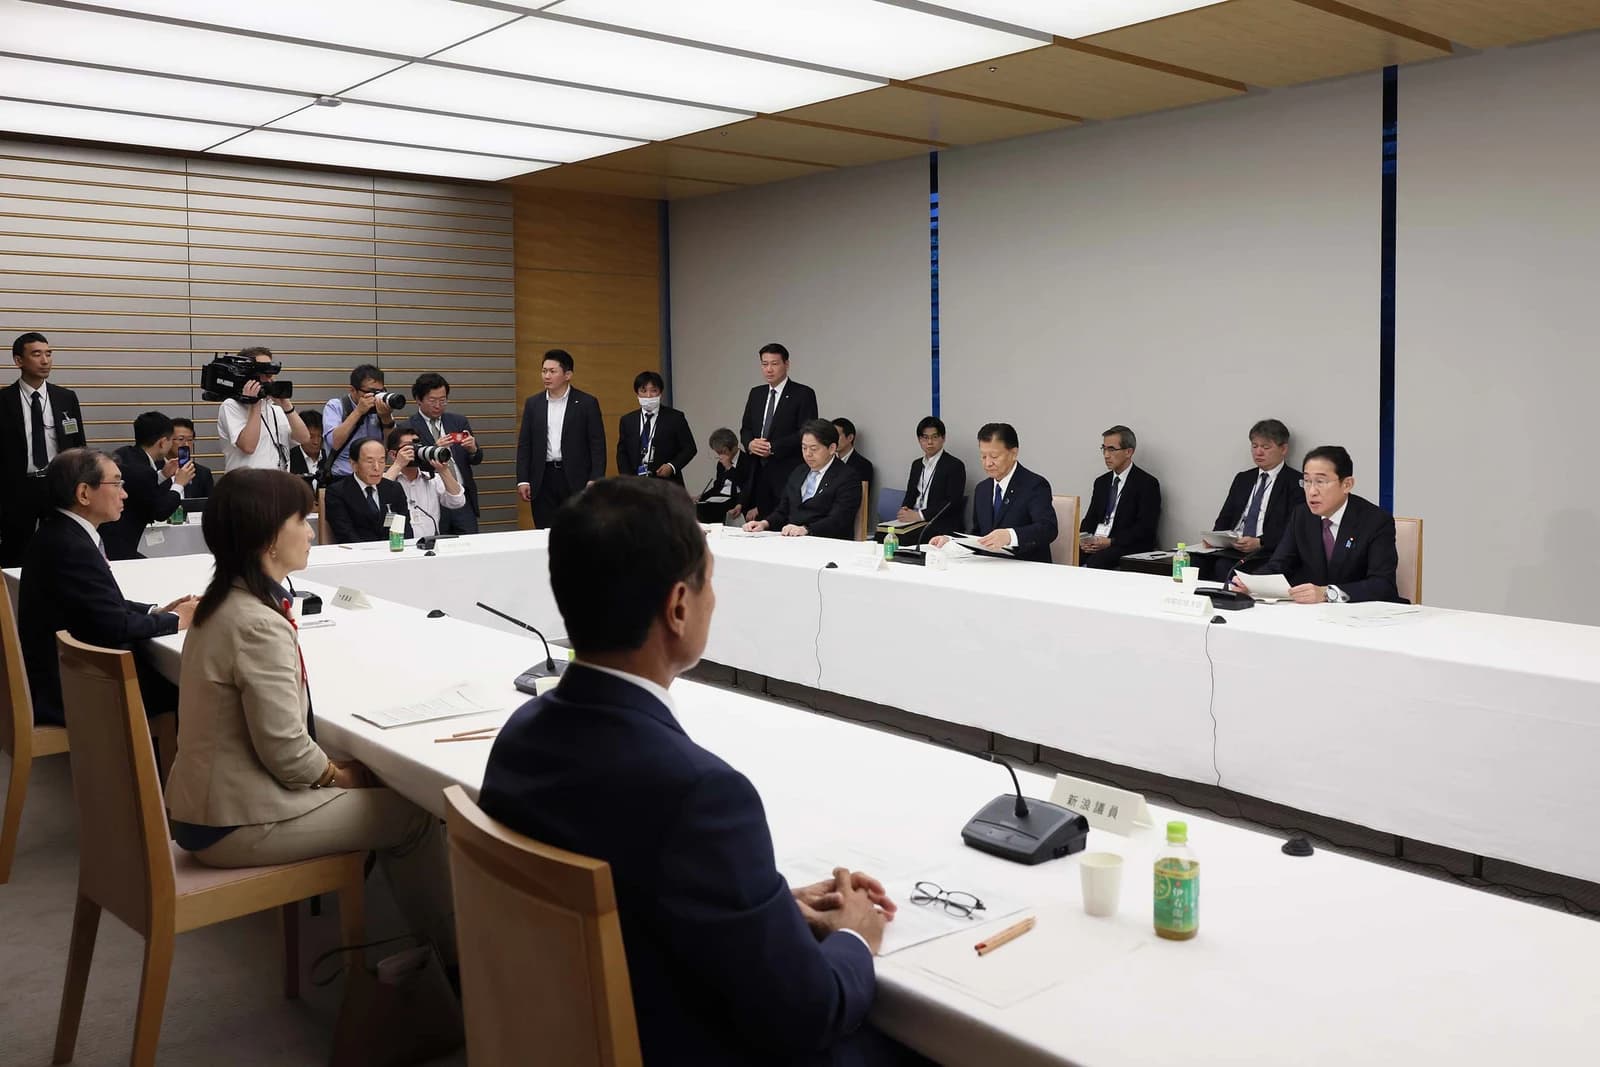
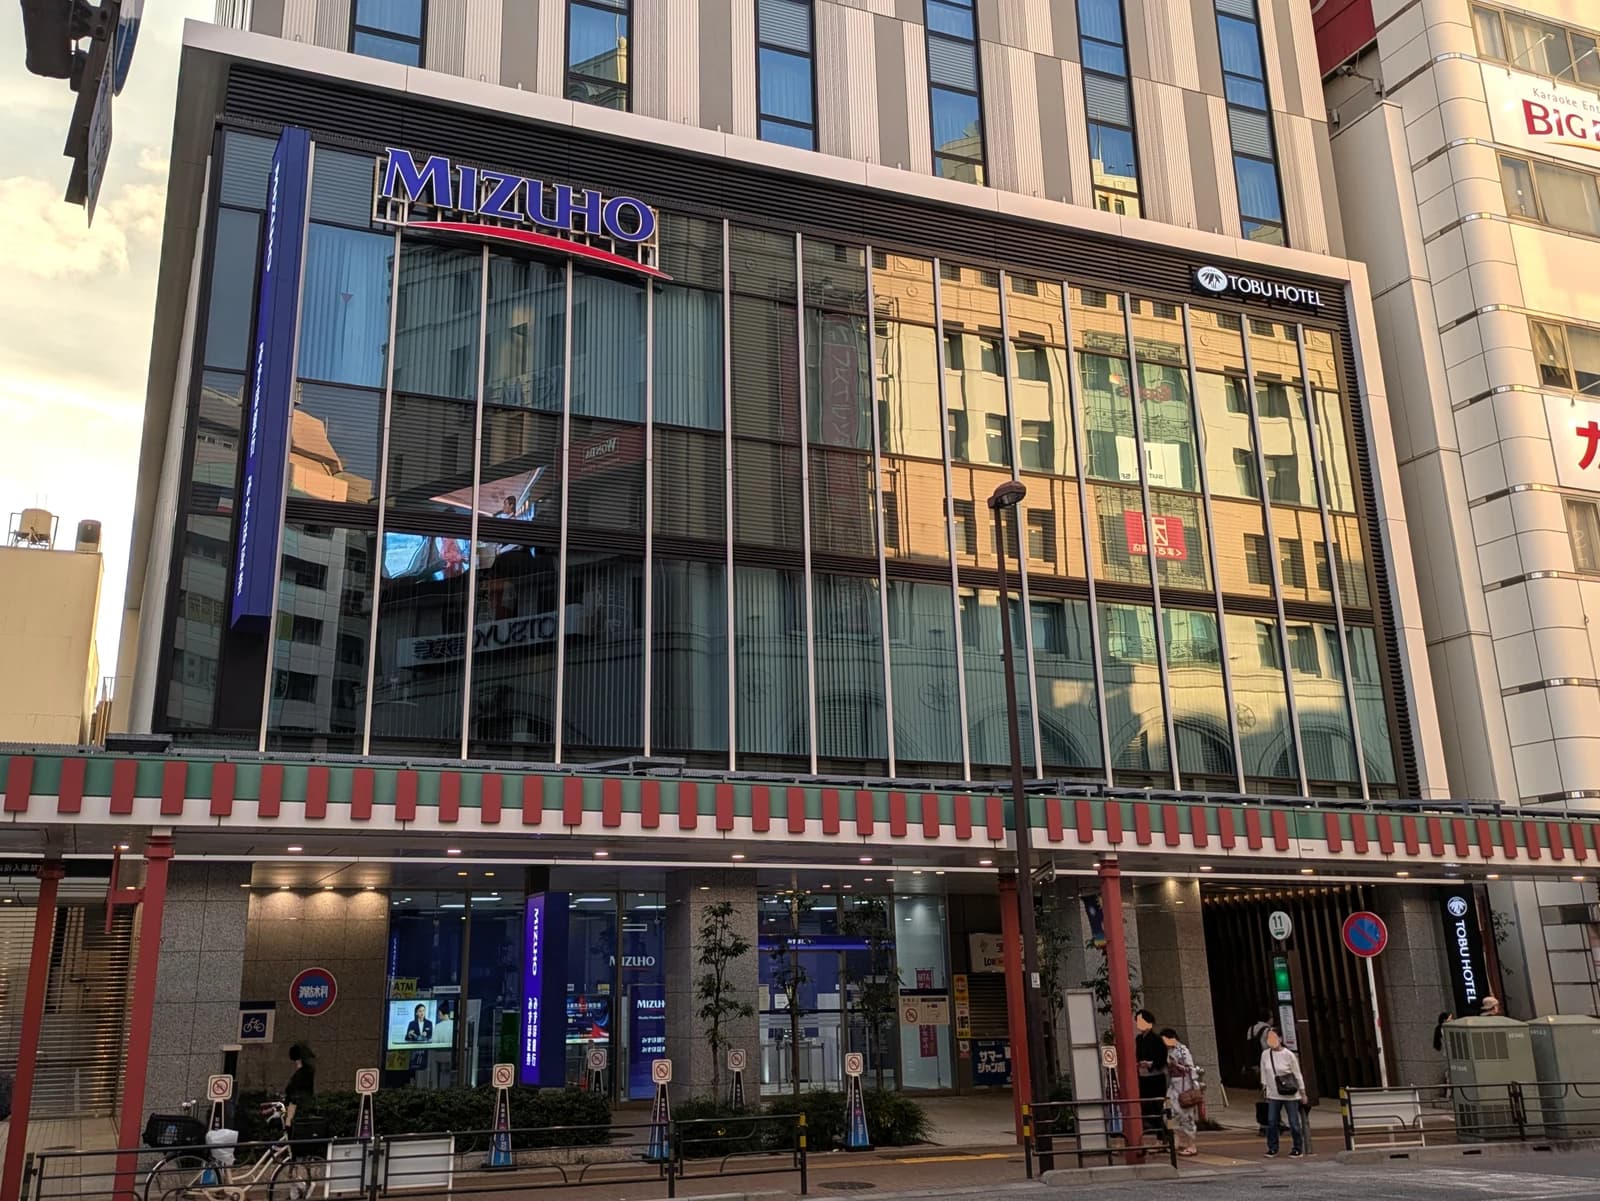
Mizuho Bank has become the first of Japan’s three megabanks to revive so-called savings deposits, a sign that the country’s long era of near-zero rates is finally changing how banks compete for household money.
Mizuho Bank Revives Savings Deposits in Japan
That matters because once deposits start paying meaningful interest again, the battle for funding shifts from inertia to incentives. For savers, especially wealthier households with large cash balances, the move makes idle money more productive. For banks, it raises the cost of attracting and keeping deposits just as the Bank of Japan edges toward another rate hike and the broader funding environment tightens.
Sentiment IndicatorsⓘProprietary · adalytica.com · September 7, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
Mizuho’s new structure, which adds interest based on the size of a customer’s deposit, reflects a wider industry response to a higher-rate Japan. Banks have been under pressure to secure stable funding while credit demand remains firm, and deposit pricing is becoming a more important lever than it has been for decades. Once one megabank moves, the others are forced to consider whether they can afford to stand still.
For investors, the key question is not whether this is a small product tweak — it is — but whether it marks the beginning of a structural repricing of Japanese bank liabilities. If deposit rates rise across the system, net interest margins may not expand as quickly as some have hoped, even if policy rates move higher. That would matter for earnings quality, especially for lenders that rely heavily on sticky retail deposits and low funding costs to protect profitability.
The timing is also telling. Japanese banks are operating in an environment of rising attention to inflation, a more hawkish Bank of Japan, and stronger competition for cash. At the same time, savers have far more options than they did during the ultra-low-rate years, including government bonds and other yield-bearing products. The result is a banking sector that must work harder for every yen of funding.
That makes Mizuho’s move worth watching well beyond the immediate product announcement. If deposit competition intensifies, it could reshape how Japanese banks manage balance sheets, return capital, and grow earnings over the next several years. For long-term investors, the best takeaway is simple: Japan’s banks are entering a new interest-rate cycle, and the winners will be the lenders that can reprice funding without losing deposits.
| Entity | Gains | Losses |
|---|---|---|
| Mizuho depositors | ▲Higher cash returns | ▼Lower-yielding idle balances |
| Mizuho Bank | ▲More deposit inflows | ▼Higher funding costs |
| Rival megabanks | ▲Pressure to match rates | ▼Pricing flexibility |
| Bank shareholders | ▲Potential volume growth | ▼Margin compression |