Indian equities recovered sharply from a gap-down open as buying in banks, real estate and select IT names pushed the Nifty to the day’s high and left the benchmark poised for a weekly gain. The move matters because it shows domestic risk appetite remains strong even as global markets wobble, with the Nifty Bank scaling a fresh record above 64,000 and setting the tone for the broader market.
Nifty Rebounds as Banks Hit Record Highs
The session’s most important feature was the speed and breadth of the rebound. After opening lower, the Nifty climbed almost 250 points from the day’s lows to trade near 25,700, while the Sensex rose more than 600 points to reclaim 83,600. That kind of intraday reversal suggests dip-buying remains aggressive on Dalal Street, particularly in financials, where the banking index is now up more than 17% this month and on track for its best monthly rise since November 2020.
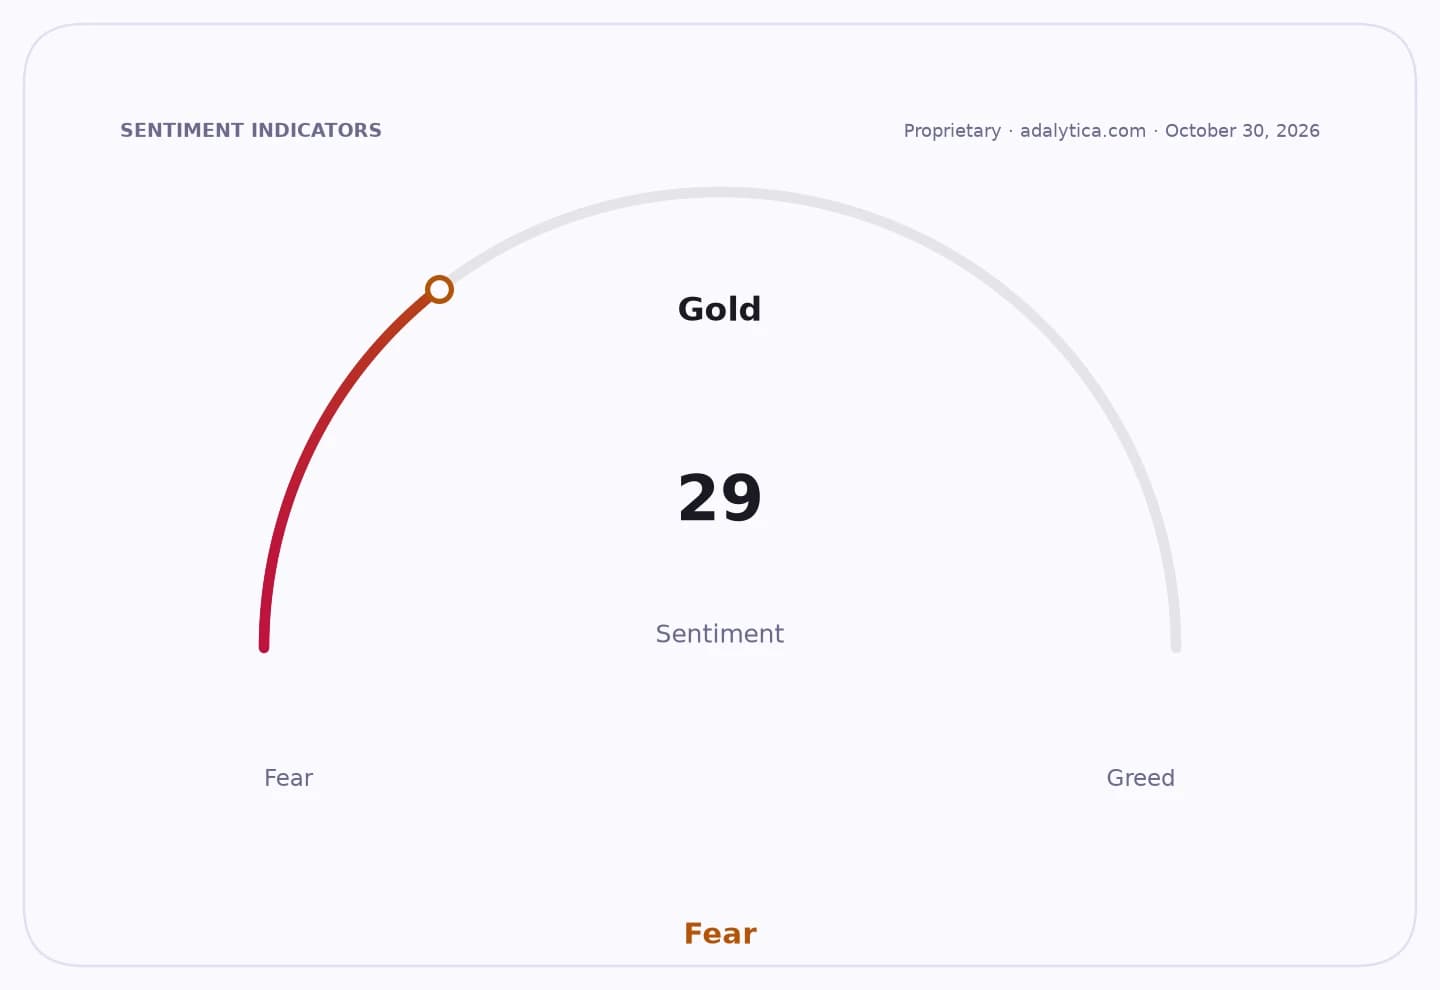
Sentiment Indicators
For investors, the significance is twofold. First, the rally is being led by the market’s heaviest and most systemically important sector: banks. Axis Bank, ICICI Bank, HDFC Bank and Kotak Mahindra Bank were all near or at record territory, lifting index levels and improving breadth. Second, the move is happening despite a stronger dollar and renewed concern that the Federal Reserve could keep rates elevated for longer, a combination that has pressured precious metals and weighed on Asian peers.
That divergence highlights the current market narrative: India remains a relative safe haven for equity allocators. Global risk assets weakened, with South Korea’s Kospi and Japan’s Nikkei falling sharply, yet Indian stocks held firm. Adalytica’s U.S. dollar trade signal also points to extreme fear in the greenback, even as awareness remains elevated, underscoring the macro backdrop of tighter external liquidity and volatile cross-asset pricing. Against that, India’s market has continued to attract capital on the back of domestic growth visibility and bank-led earnings resilience.
F&O positioning reinforces the constructive tone. The put-call ratio rose through the session to 1.40 from 1.33 in the previous session, while 25,500 remained the most active put strike. Traders were also watching 25,750 to 25,880 as the next resistance band, with support seen around 25,250 to 25,250. The options setup suggests the market is building a higher base, though it is not yet fully free of overhead supply.
Sector performance also points to a broader domestic rotation. Realty stocks hit record highs, with Phoenix Mills, Oberoi Realty, DLF and Godrej Properties all advancing, while healthcare and IT were among the other contributors. That mix matters because it shows the rally is not limited to a single defensives trade; investors are extending risk into cyclicals and domestic growth proxies. In parallel, mutual fund data showing rising weightage to technology and healthcare suggests institutional money is still leaning into sectors with earnings durability.
There are still risks to the near-term advance. A firmer dollar and higher-for-longer U.S. rates could tighten foreign liquidity, while the sharp fall in gold and silver is already pressuring bullion-linked names such as Muthoot Finance. But for now, the market is treating those headwinds as secondary to the stronger domestic story: stable inflows, bank strength and a liquidity-backed bid under large-cap Indian equities.
If the Nifty can hold above the 25,500 to 25,250 zone, the market looks positioned to extend its weekly advance. A failure there would argue for consolidation, but the current action suggests investors are still willing to buy India on weakness.
| Entity | Gains | Losses |
|---|---|---|
| Nifty / Sensex bulls | ▲Strong intraday recovery | ▼Gap-down sellers |
| Banks | ▲Record highs, index leadership | ▼Short positions in financials |
| Realty stocks | ▲Momentum and new highs | ▼Valuation skeptics |
| Gold/bullion-linked names | ▲None | ▼Muthoot Finance and metal holders |