Indian equities finished little changed after the closing auction session, but the real story was the market’s resilience: the Nifty held above 23,250 as broader stocks, real estate and pharma extended gains even as banks lagged.
Nifty Holds 23,250 as Realty and Pharma Rise
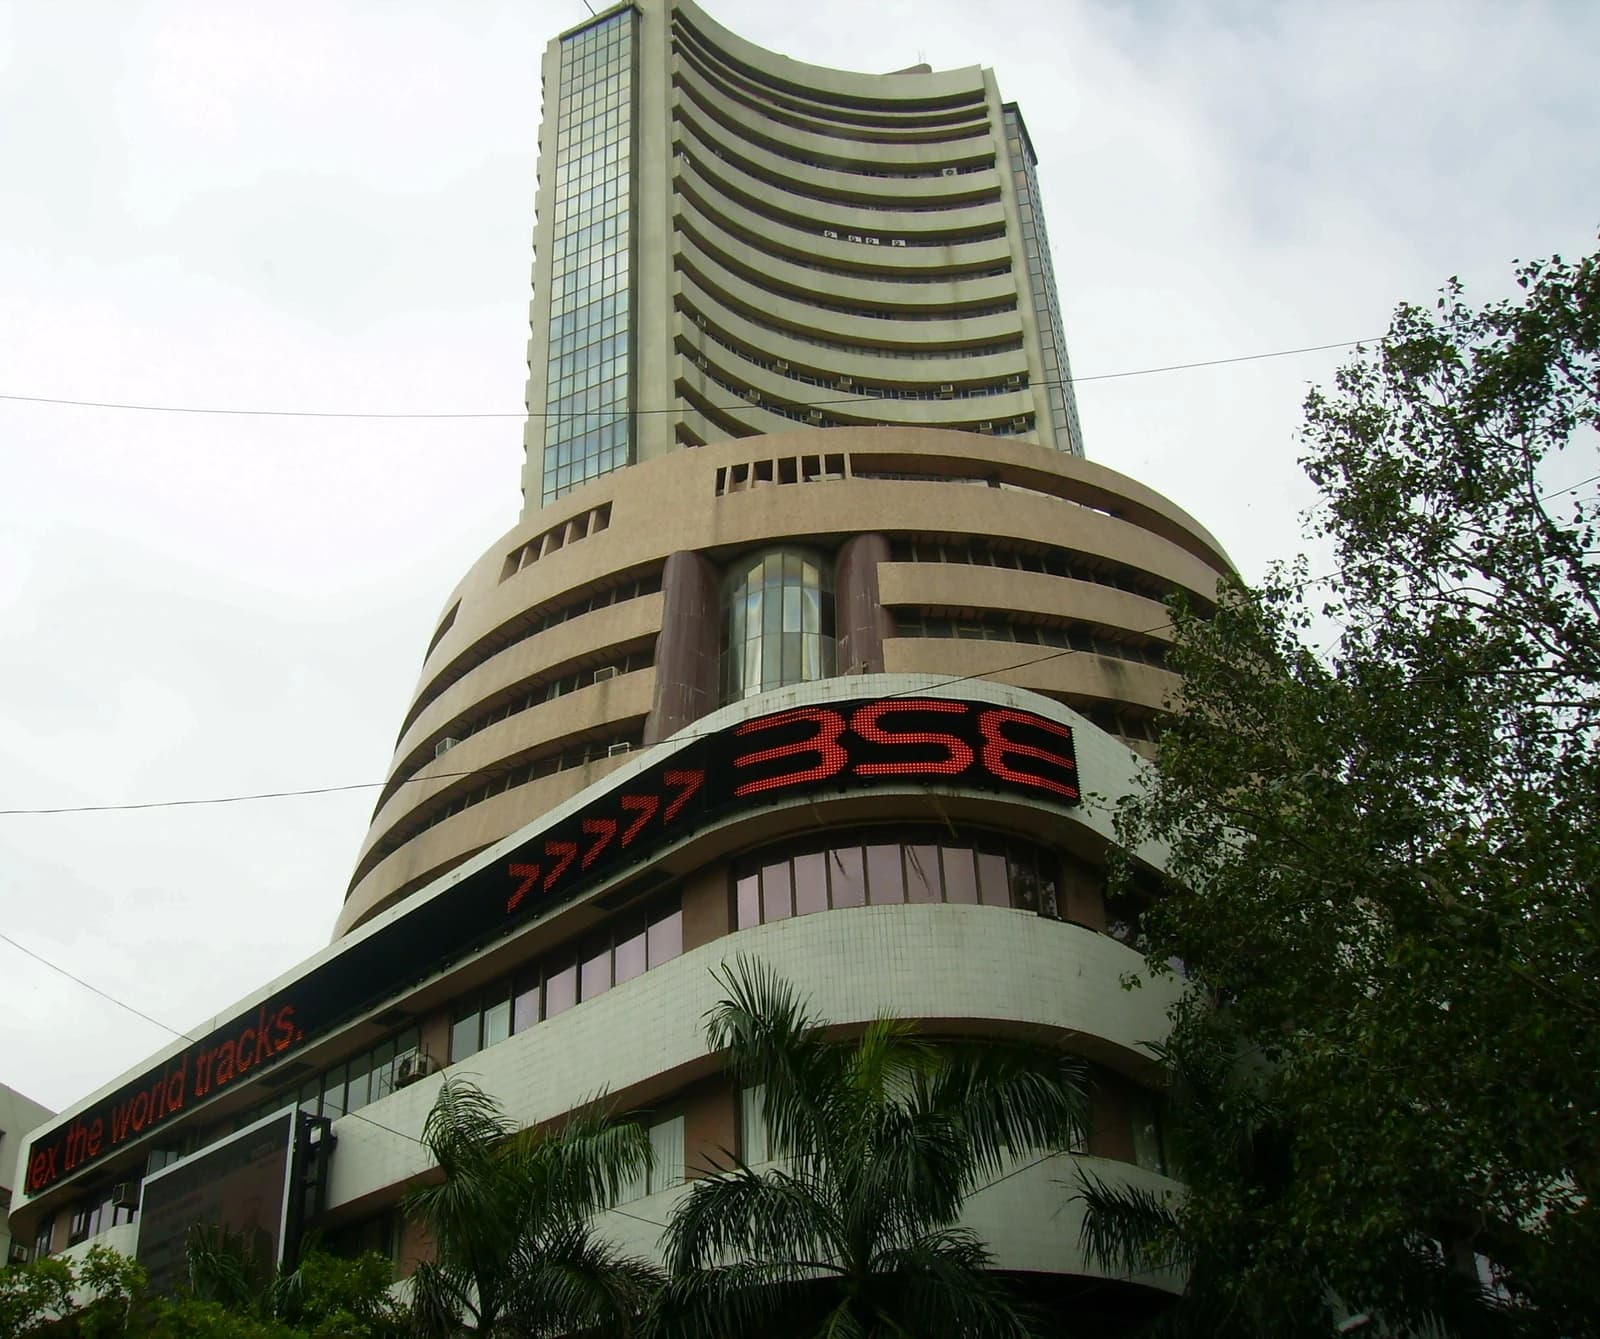
That matters because this was not a risk-off tape. The Sensex slipped just 21.86 points, or 0.03%, to 74,314.59, while the Nifty added 53 points, or 0.23%, to 23,270.60. Midcaps rose 0.92% and smallcaps gained 0.71%, with advancing shares outnumbering decliners 2,480 to 1,487 and the India VIX tumbling nearly 7% to 12.28. In other words, investors were buying breadth and volatility was coming out of the market, even as the benchmark index ended nearly unchanged.
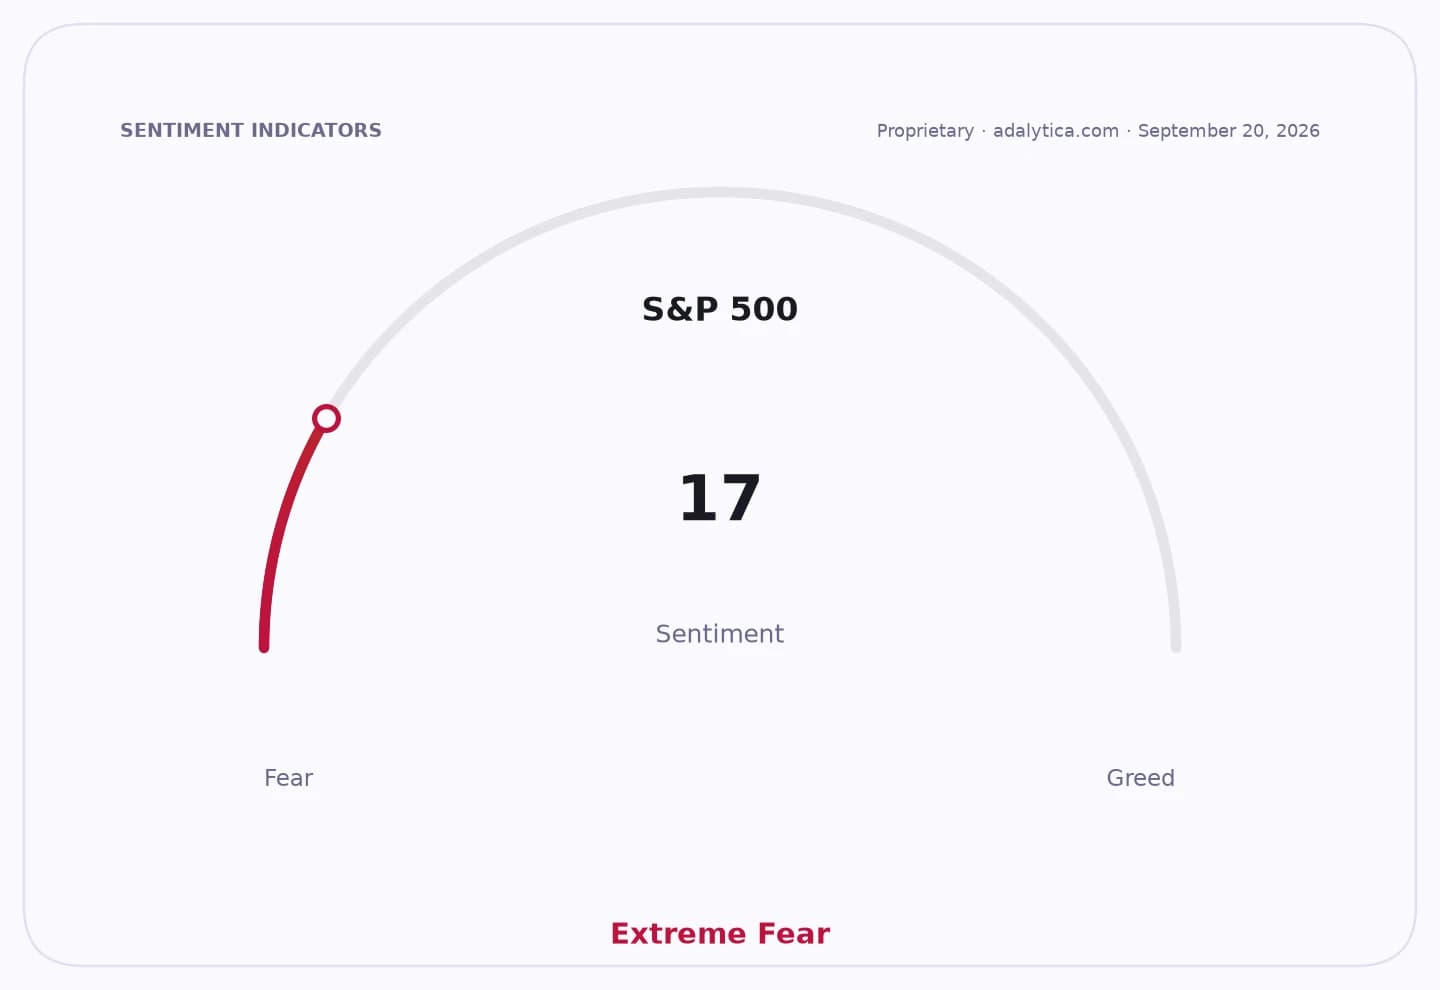
Sentiment IndicatorsⓘProprietary · adalytica.com · September 18, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The sector mix tells you where the next leadership is forming. Realty climbed 1.66% and pharma 1.62%, while media, autos and metals also advanced. That is a healthier pattern than a narrow rally led by financials, especially with Bank Nifty down about 0.3% and private lenders under pressure. HDFC Life, SBI Life and other insurance names surged after reports the regulator may cut commissions for agents and banks, a development that could expand margins for insurers over time. Lupin’s reiteration of a 25% EBITDA margin target for FY27 also kept the pharma trade hot, reinforcing the view that investors are rewarding businesses with visible earnings power and operating leverage.
The market’s tone suggests money is rotating toward domestic growth and policy-sensitive beneficiaries rather than simply chasing the benchmark. The outperformance in midcaps and smallcaps, alongside a sharp drop in volatility, points to improving risk appetite beneath the headline indices. Even pockets like capital goods, healthcare, services and autos joined the advance, which is exactly what you want to see if a market is trying to build a broader base after a period of heavy pressure.
For investors, the message is straightforward: this is still a stock pickers’ market, but the best opportunities are in sectors where earnings visibility and structural tailwinds are intersecting. Life insurers could be early winners if distribution economics improve. Pharma remains attractive as a defensive growth compounder with margin discipline. Realty continues to benefit from operating leverage and domestic demand, while capital goods and select industrial names are drawing support from volume and momentum.
The near-term test is whether the Nifty can keep defending the 23,250 area while breadth stays constructive. If that holds, today’s quiet close may prove more important than it looks: not as a breakout in the index, but as an early sign that leadership is broadening beyond banks and into the parts of the market with the best asymmetry.
| Entity | Gains | Losses |
|---|---|---|
| Realty stocks | ▲Sector leadership | ▼Bank-heavy portfolios |
| Pharma stocks | ▲Margin visibility | ▼Cyclical laggards |
| Life insurers | ▲Better commission outlook | ▼Agents and bank distributors |
| Banks | ▲None | ▼Broader market momentum |