Nigeria’s failure to turn economic stability into broad-based living standards is becoming the country’s biggest policy and investor risk, after it was ranked the weakest performer in West Africa in the fight against inequality during the pandemic.
Nigeria inequality and poverty remain key investor risk
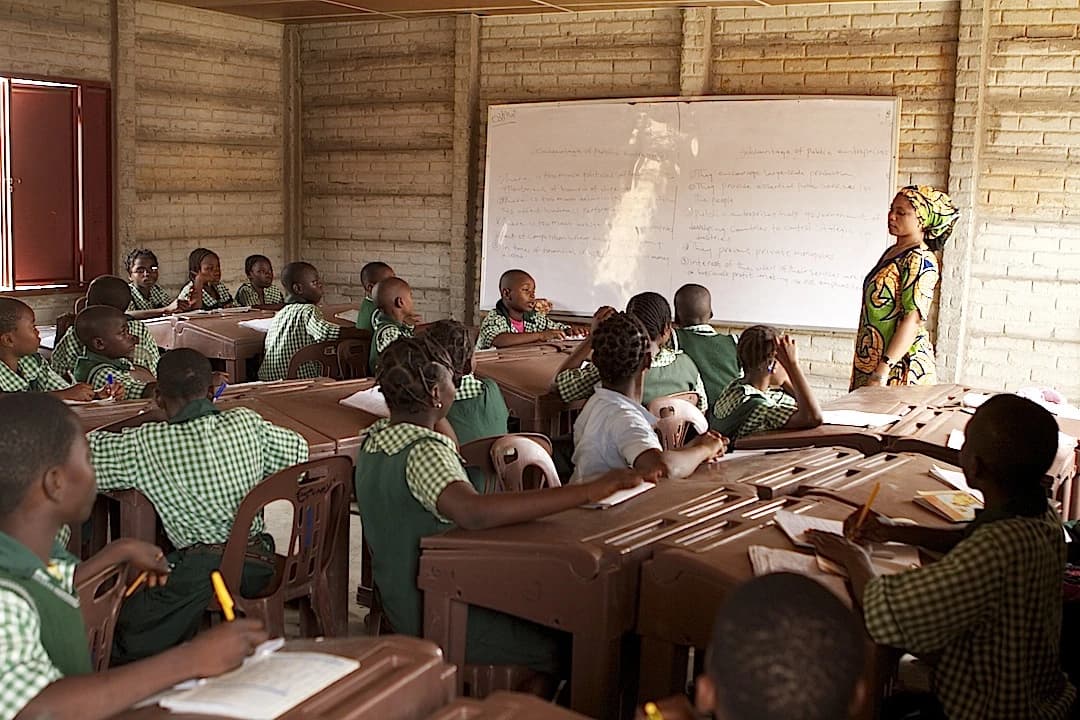
The warning matters because the problem is no longer just social. A country with 38.7% multidimensional poverty, nearly 18 million people facing basic-needs deprivation and a labor market still struggling to absorb workers is at higher risk of slower consumption growth, weaker domestic demand and recurring pressure on public finances.
The IMF has said Nigeria remains exposed to poverty despite recent macroeconomic stabilization, with high living costs and insecurity continuing to erode purchasing power. That makes the government’s policy mix — especially fuel subsidy restraint, fiscal discipline and spending priorities — central to whether growth feeds into households or stays concentrated in aggregate figures.
The Vanguard report’s call for heavier investment in public education, health care and social protection points to the real constraint: Nigeria cannot close its inequality gap without widening access to services that raise productivity and reduce vulnerability. For investors, that means the sustainability of any recovery depends not only on oil earnings, inflation trends or currency stability, but on whether Abuja can convert growth into jobs and consumption.
That linkage is crucial for portfolio flows, sovereign risk perception and the outlook for companies tied to the domestic consumer. If household incomes keep lagging, demand for everything from staples to telecom services weakens, while social strain can also complicate reform implementation and deter capital spending.
The next test is whether the government follows through with targeted welfare spending, security improvements and reforms that can support employment rather than simply preserve macro stability. Without that shift, Nigeria’s growth story is likely to remain narrow — and inequality will continue to undercut the investment case.
| Entity | Gains | Losses |
|---|---|---|
| Nigerian households | ▲Better services, income support | ▼Persistent poverty and high living costs |
| Federal government | ▲Reform credibility if spending rises | ▼Political pressure over inequality |
| Domestic consumer companies | ▲Broader demand if incomes improve | ▼Weak purchasing power and spending |
| Investors in Nigeria | ▲Clearer policy path if reforms stick | ▼Higher social and fiscal risk |