Oil markets are still too volatile for JPMorgan to call a clean end to the supply shock, with U.S. crude trading around $92.66 a barrel on Sept. 23 after a sharp pullback from earlier September highs but still far above levels that prevailed before the latest surge.
Oil Prices Stay Elevated After September Pullback
That keeps the inflation and earnings stakes high for investors. Even after crude slipped from $105.83 on Sept. 15, the benchmark remains more than 10% above its early-month level and well above the 50-day moving average of $87.48, suggesting the market is still pricing in a meaningful geopolitical risk premium rather than a quick return to normal.
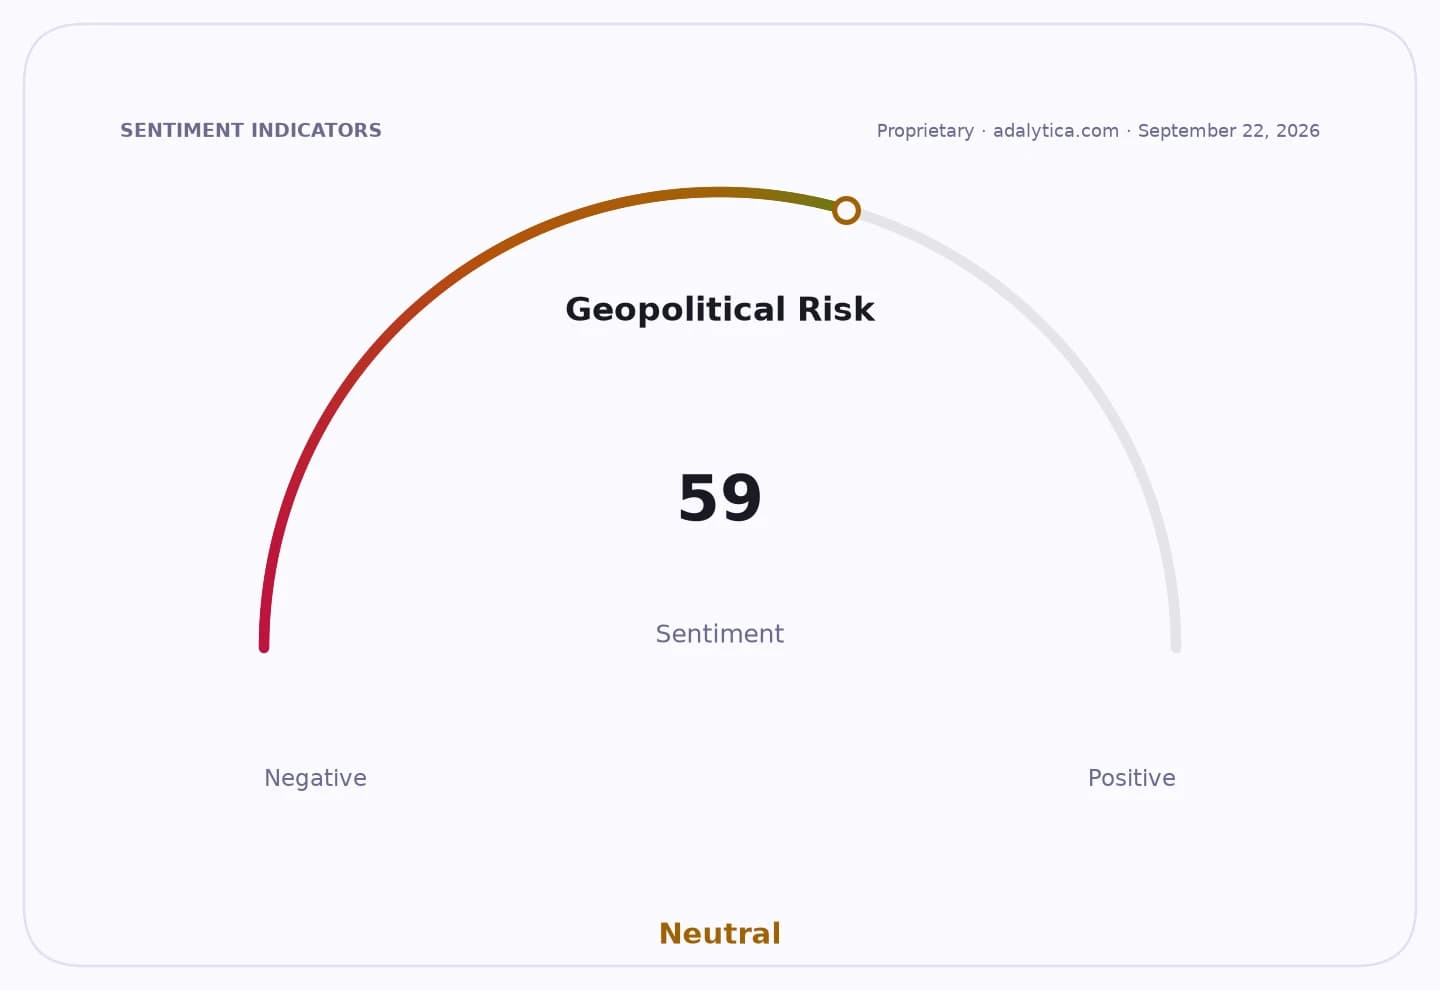
Sentiment IndicatorsⓘProprietary · adalytica.com · September 23, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The move matters far beyond oil itself. Higher crude feeds directly into transport, petrochemical and consumer costs, complicating the outlook for central banks already facing stubborn inflation and keeping bond markets on alert. The 10-year Treasury yield was steady at 4.96%, while Adalytica’s U.S. dollar trade signals showed extreme greed in the dollar, a sign traders are still positioning for macro stress and tighter financial conditions.
Energy stocks are reflecting that backdrop. Exxon Mobil closed at $161.23, near recent highs and above its 200-day moving average of $145.79, while Chevron ended at $205.51, also comfortably above its 200-day average of $181.77. The shares have benefited from the run-up in crude and from expectations that the latest price floor will support upstream cash flow, buybacks and dividend coverage.
JPMorgan’s hesitation to declare the oil war over also underscores how quickly sentiment can shift. WTI touched $105.83 on Sept. 15 and then slid to $94.59 on Sept. 22, a reminder that headlines around the conflict and supply disruptions are still capable of moving prices by several dollars a barrel in a single session.
For investors, the key question is whether the pullback is a reprieve or the start of a trend. If crude stabilizes above $90, integrated producers and service names should keep trading with a premium, while airlines, refiners and consumer discretionary stocks remain exposed to renewed cost pressure; the next catalyst is likely to be fresh geopolitical developments or any sign of a broader supply response.
| Entity | Gains | Losses |
|---|---|---|
| Exxon Mobil | ▲Higher cash flow | ▼Fuel-cost volatility |
| Chevron | ▲Buyback/dividend support | ▼Margin uncertainty |
| Oil bulls | ▲Persistent risk premium | ▼Quick normalization |
| Consumers/airlines | ▲Lower crude prices | ▼Renewed inflation shock |