Young car mechanics in Poland are becoming one of the hardest industrial workers to replace, and that labor squeeze is pushing pay well above 10,000 zloty a month even as the broader European auto industry heads into layoffs.
Poland Auto Mechanics Wages Rise Above 10,000 Zloty
That is the key investment story hidden inside the headlines: the weakest part of the automotive chain is the factory floor, but the resilient, high-friction part is the repair bay. For investors, that matters because it shows where demand is durable, where skills shortages are forcing wage inflation, and where capital is likely to keep flowing even if vehicle makers cut jobs.
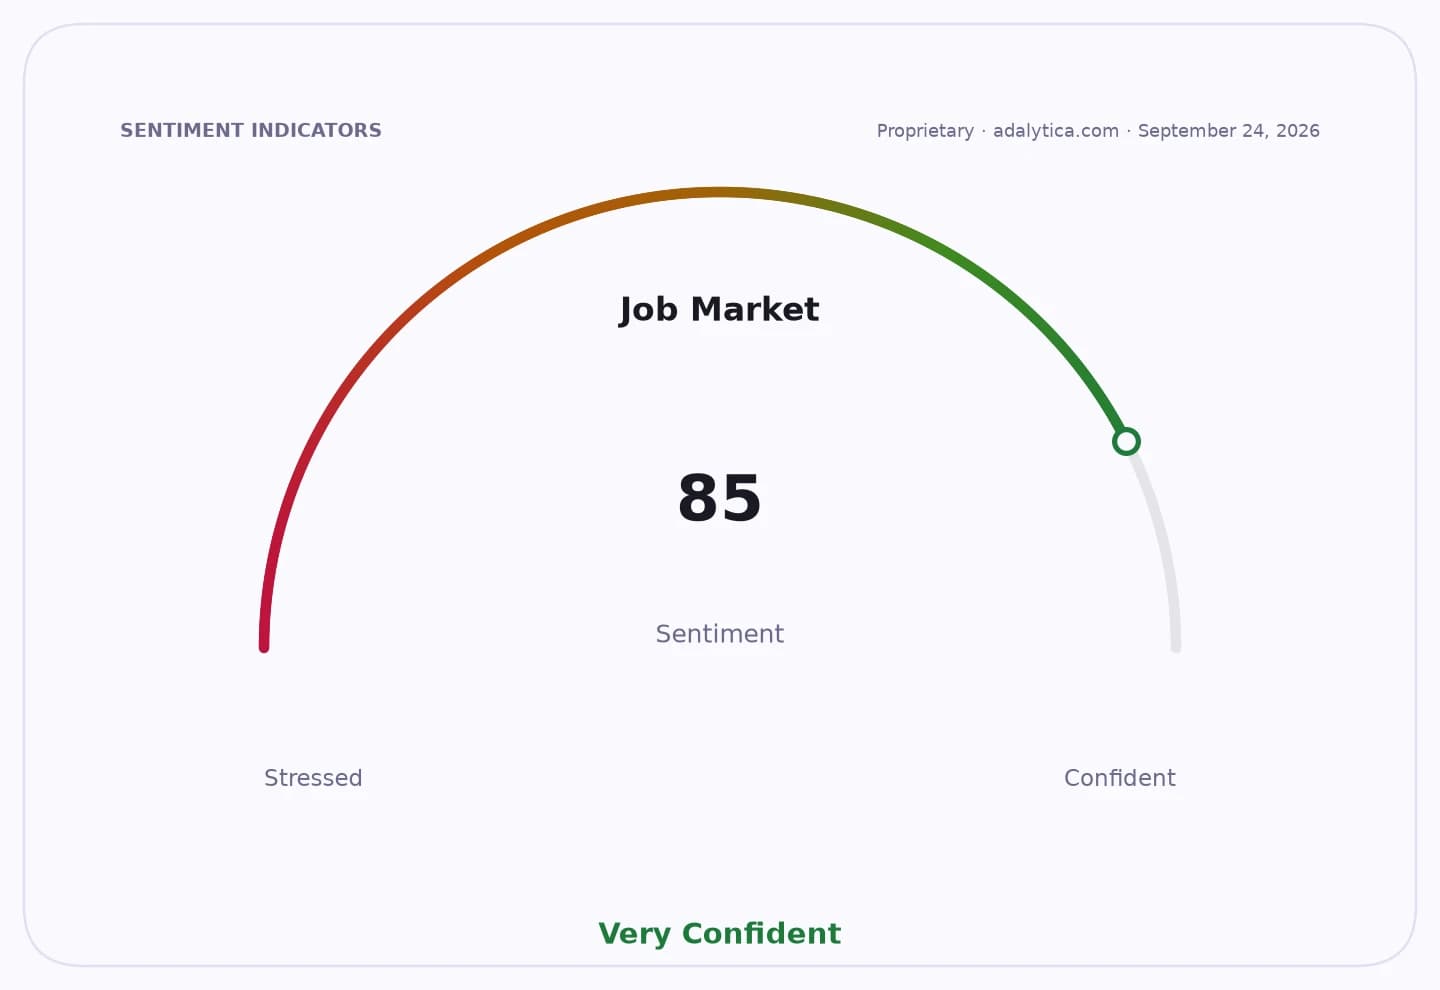
Sentiment IndicatorsⓘProprietary · adalytica.com · September 8, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
Poland now has about 24,000 auto workshops, and nearly 18,000 of them cannot find qualified staff, according to the Association of Automotive Parts Distributors and Producers. In a labor market where basic manufacturing roles are increasingly vulnerable to automation and restructuring, mechanics, auto electricians and heavy-truck technicians are being paid like scarce technicians, not blue-collar afterthoughts. Job ads cited in the report show wages of 11,000 to 13,000 zloty for mechanics, up to 15,000 zloty for truck mechanics, and 10,000 zloty or more for experienced staff in some regions.
The economics are straightforward. Cars are getting more electronic, more complex and more dependent on diagnostic skill, while electric and hybrid vehicles add another layer of specialization. That makes repair work harder to outsource, harder to automate and more valuable per worker. The result is a classic supply-demand imbalance: demand for repairs persists because households often own multiple vehicles, but the supply of technicians is constrained by weak vocational training and a shortage of graduates prepared to work on modern drivetrains and software-heavy systems.
The irony is that this shortage is emerging just as the European auto industry is under severe strain. Volkswagen has warned of possible plant closures and as many as 50,000 jobs at risk over coming years, while Stellantis has also flagged cuts in Poland. Industry groups warn the region could lose 300,000 to 350,000 auto jobs in the next few years. Yet the repair segment is still hiring. That divergence is what investors should watch: as production shrinks, service, maintenance and aftermarket spending can become a relative safe harbor.
For markets, the implication is not just labor inflation. It is a road map for where the value chain remains profitable. Parts distributors, independent workshops, diagnostic-tool makers, training providers and suppliers to the aftermarket are better positioned than assembly-line exposed names. The repair ecosystem benefits from an aging vehicle fleet, higher vehicle complexity and recurring maintenance needs, all of which support pricing power.
The market is underestimating how long this can last. If the auto industry’s crisis deepens, more workers may eventually migrate into repair and service, but that will not be enough to erase the skills gap quickly. Until vocational pipelines improve, workshops will keep bidding up wages, and the sector’s resilience will remain intact.
For investors, the takeaway is clear: the next opportunity in European autos is not in the factory headlines everyone is selling — it is in the toll roads of the aftermarket, where scarce technicians and recurring repair demand are turning labor shortages into pricing power.
| Entity | Gains | Losses |
|---|---|---|
| Auto workshops | ▲Higher pricing power | ▼Higher labor costs |
| Skilled mechanics | ▲Wage growth above 10,000 zloty | ▼Short staffing pressure |
| Auto parts distributors | ▲Steady aftermarket demand | ▼Factory slowdown spillover |
| Vehicle manufacturers | ▲None | ▼Job cuts and restructuring costs |