Romania’s stock market is getting deeper, but the real story is that demand is still outrunning supply — a setup that can keep valuations hot, lift the BET index and force investors to focus more on earnings than on easy liquidity gains.
Romania BET Rally on Demand Outrunning Supply
That is the message from investor Marius Alexe, who said turnover at the Bucharest Stock Exchange has doubled from a year ago, yet the number of shares available for trading has barely kept pace. In plain English: more money is chasing roughly the same pool of stocks. For long-term investors, that is not just a trading quirk. It is a sign that Romania’s capital market is maturing, but also that prices can become increasingly sensitive to any change in company fundamentals, sovereign risk or foreign appetite.
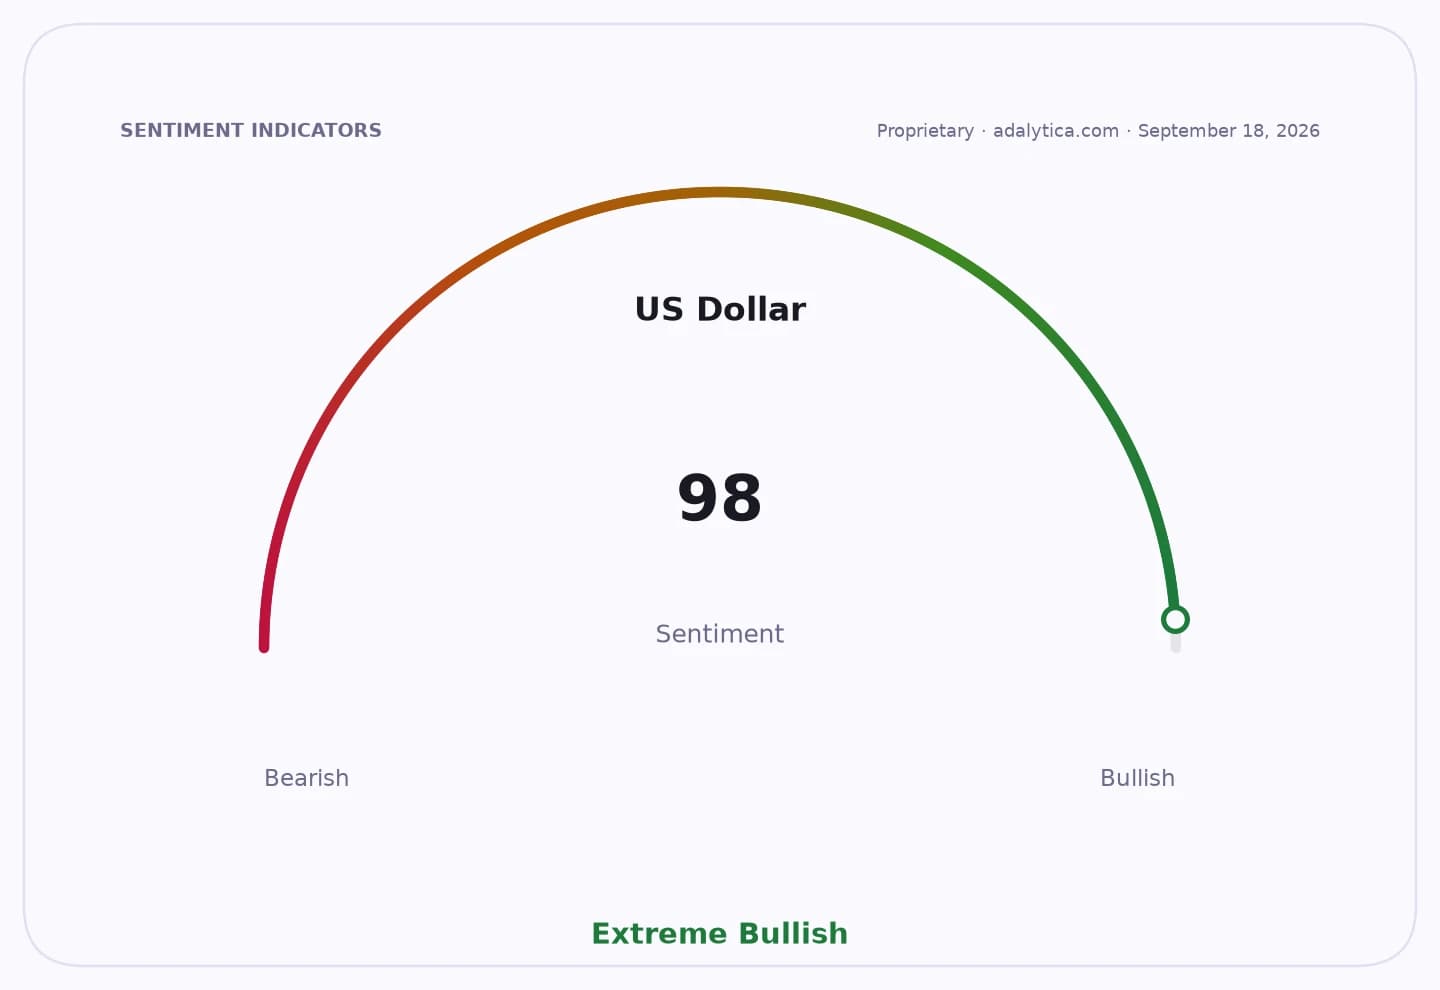
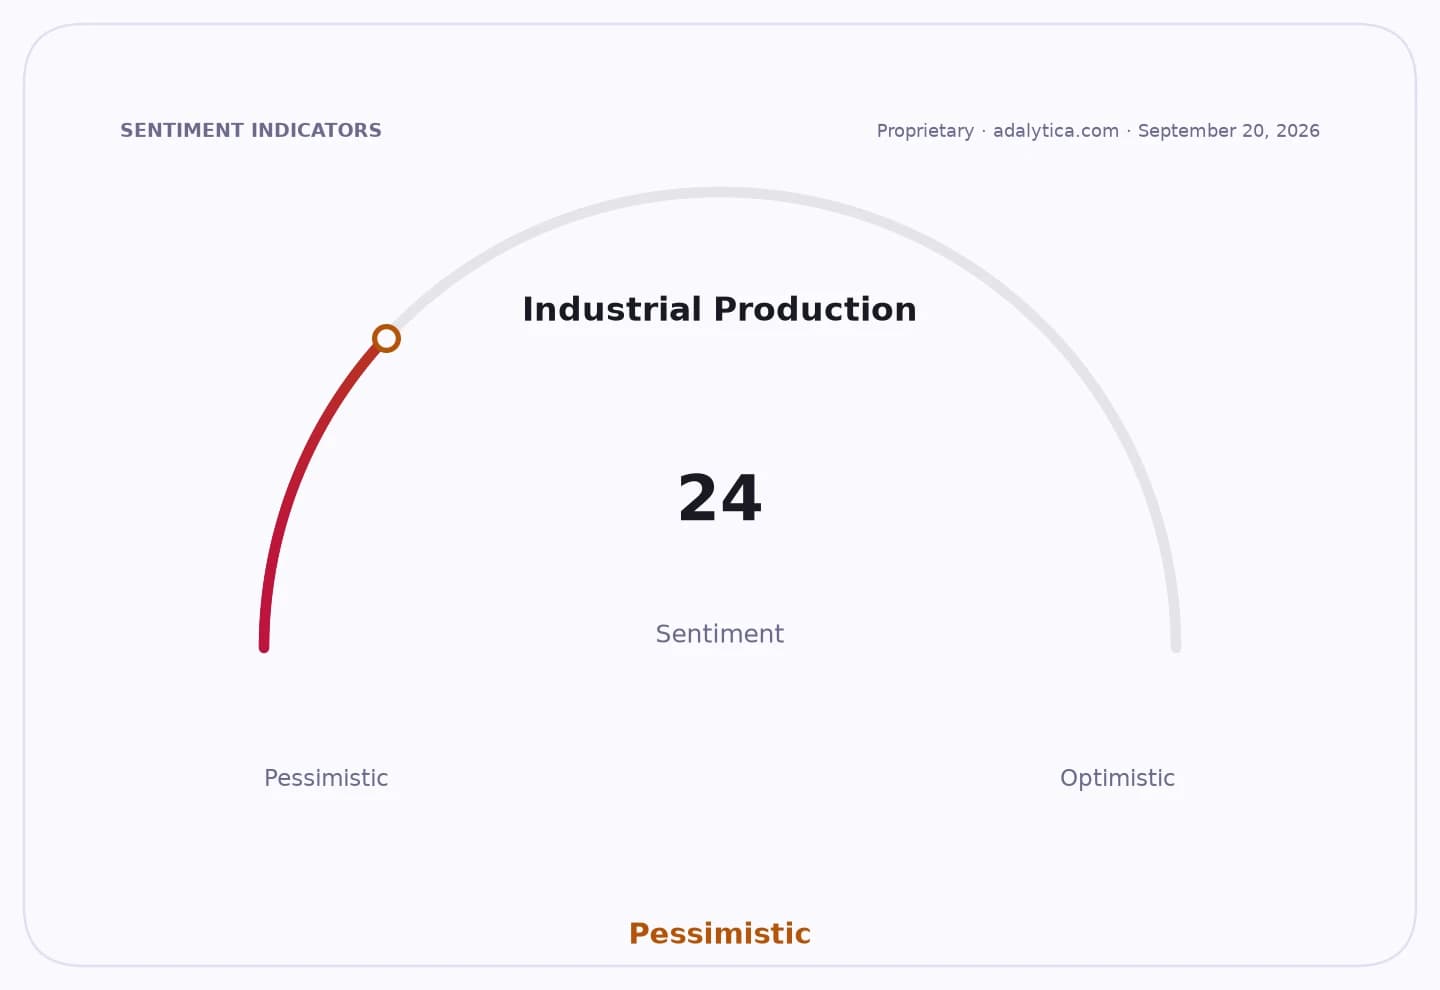
Sentiment IndicatorsⓘProprietary · adalytica.com · September 23, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The imbalance matters economically because a market with stronger liquidity can help companies raise capital more efficiently, support fresh listings and broaden ownership. But if issuers do not bring more stock to market, the benefit mainly accrues to sellers and existing holders rather than to the broader economy. Alexe said the local exchange has had only a few major initial public offerings in the past year, including Cris-Tim, Electro-Alfa and Christian Tour, which is far too little to absorb the surge in demand.
That shortage helps explain why the BET index has climbed more than 30% this year even as Romania wrestles with slowing consumption, high inflation and pressure on public finances. Investors have clearly been willing to look through the macro noise, but that can change quickly. The next important test arrives on Oct. 2, when S&P Global Ratings is due to review Romania’s sovereign rating. Alexe does not expect an immediate downgrade from investment grade, but he warned that rating agencies will become less patient if Bucharest fails to rein in its budget deficit.
For investors, that combination is both opportunity and risk. On one hand, stronger liquidity and rising retail participation — the number of retail investors at the Bucharest exchange surpassed 325,000 at the end of the first half, up about 24% from a year earlier — suggest a healthier market structure than Romania has had in the past. On the other hand, when liquidity rises faster than the supply of shares, gains can become crowded, and any disappointment in earnings or fiscal policy can hit harder.
Alexe also argued that Romania remains tightly linked to foreign markets, and that local equities will likely move in step with U.S. stocks unless there is a domestic crisis. That is important for investors because it means Bucharest is no longer an isolated frontier market story. Global risk appetite, algorithmic trading and arbitrage flows can now shape local pricing as much as domestic fundamentals do.
The long-term takeaway is straightforward: Romania’s market is expanding, but not yet fast enough to fully match investor demand. If more quality companies list, and if policymakers reduce fiscal risk, the exchange could become a much better compounding machine for patient investors. Until then, the market is worth watching — especially for those who want exposure to a growing economy, but only if they are prepared for a market where valuation discipline matters more each month.
| Entity | Gains | Losses |
|---|---|---|
| Retail investors | ▲More trading access | ▼Higher valuation risk |
| Existing shareholders | ▲Richer prices | ▼Fewer bargain entries |
| Romanian issuers | ▲Easier capital raising | ▼Pressure to list more |
| Romanian fiscal hawks | ▲Rating stability | ▼Deficit complacency |