Senegal’s flour makers are warning that a fifth straight year of rising wheat imports, together with volatile freight and insurance costs, is squeezing the economics of a sector that sits at the center of food security and consumer prices.
Senegal wheat imports hit 982,106 tonnes in 2025
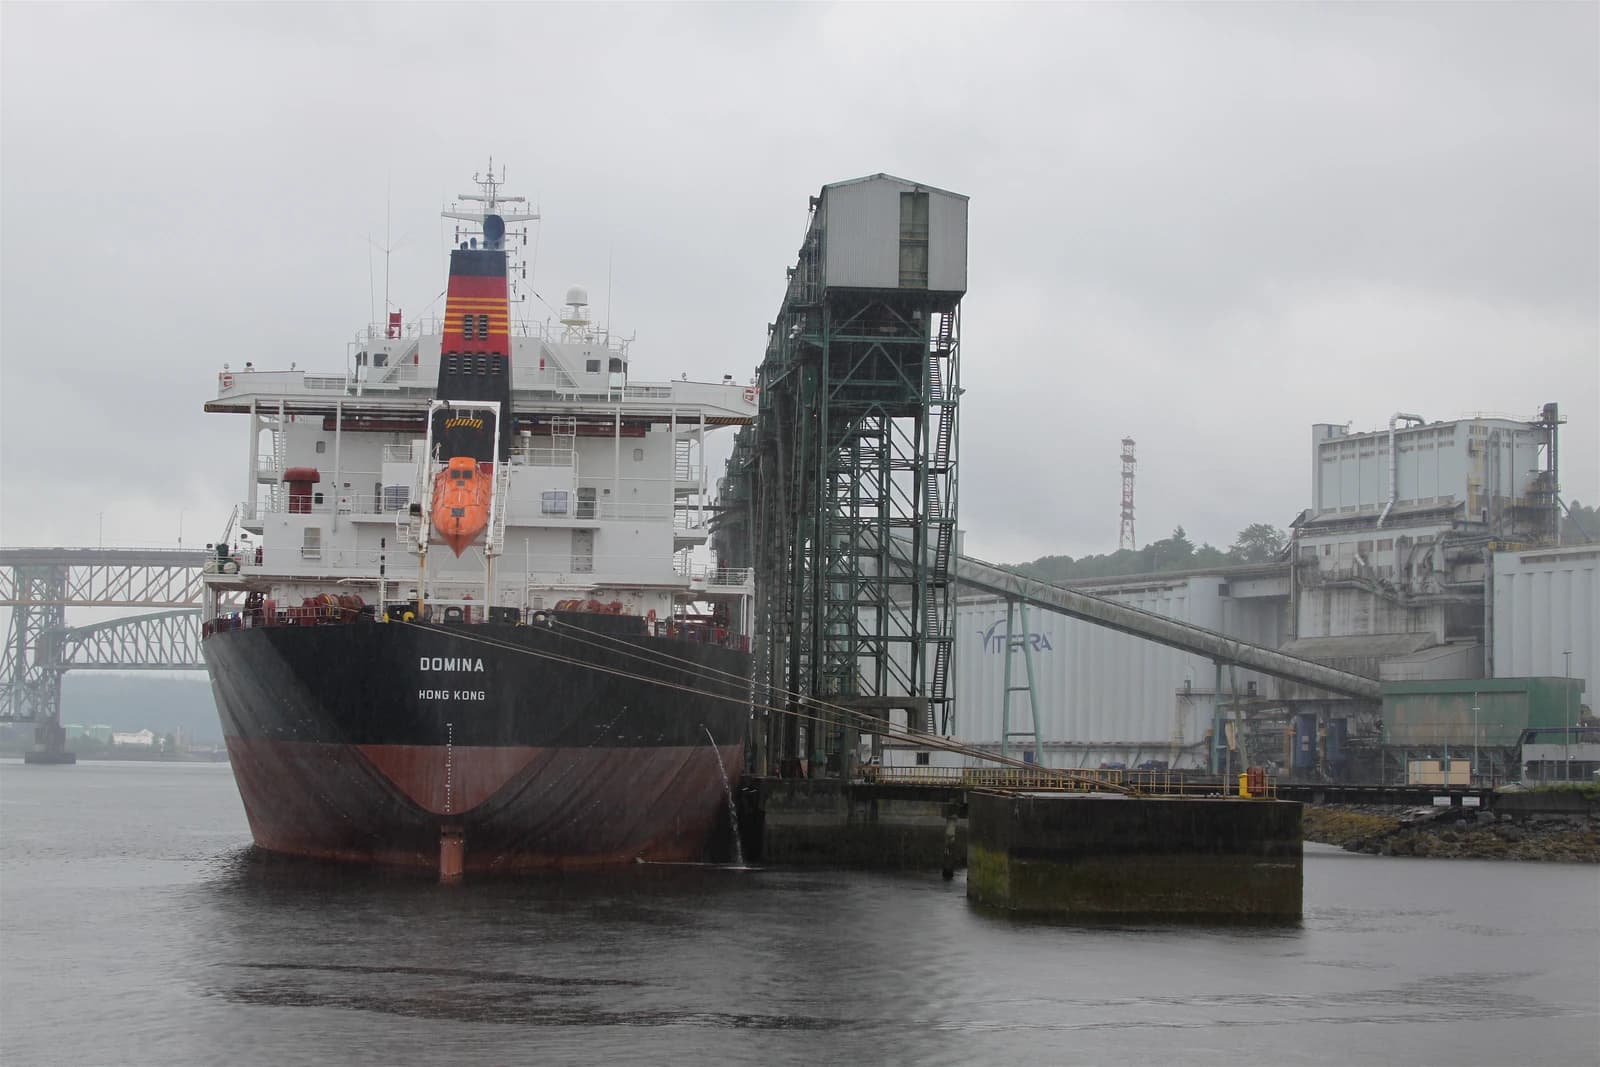
That matters because wheat is the main input for flour, and flour is a staple for Senegalese households. When the landed cost of grain rises, millers do not just face higher raw-material bills; they also absorb shipping, insurance, financing and logistics costs that can quickly ripple through the rest of the food chain. For investors, the message is simple: in import-dependent food markets, margins can be thin and highly exposed to global commodity and transport shocks.
Sentiment IndicatorsⓘProprietary · adalytica.com · October 3, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The Association of Industrial Millers of Senegal, which includes Les Grands Moulins de Dakar, FKS, OLAM, NMA, SEDIMA and MDS, said the country imported 982,106 tonnes of wheat in 2025, up 8.5% from 904,947 tonnes in 2024. The association said wheat imports have climbed for five consecutive years, rising from about 753,807 tonnes in 2021 to more than 982,000 tonnes this year. It also said 2024 imports were worth 184.9 billion CFA francs, underscoring how large the foreign-exchange bill has become for a basic food input.
The broader economic point is that Senegal’s milling industry is carrying more of the burden of feeding a growing market without any real insulation from global supply swings. The association said the cost of wheat arriving in Senegal is shaped not only by grain prices but also by maritime freight and insurance, both of which have become more volatile. It pointed to Algerian wheat prices, where cost-and-freight values rose by roughly $30 a tonne in six weeks, as an example of how quickly import costs can move.
That backdrop has real consequences for companies and consumers. Higher freight rates have already been filtering through global commodity supply chains, and the Black Sea remains a sensitive route for grain shipments. Those pressures tend to favor exporters and shipowners when prices rise, while importers, millers and ultimately households are left to absorb the bill. If the cost surge persists, flour prices could eventually come under pressure even if millers are not announcing increases yet.
For long-term investors, the story is less about one country than about a recurring investment theme: staple-food businesses in import-dependent economies are defensive only on the surface. Their revenue may be steady, but their input costs can swing sharply with geopolitics, shipping and currencies. That makes scale, procurement discipline and balance-sheet strength valuable competitive advantages.
For now, the millers are not signaling shortages or a price hike. But the warning is clear: Senegal’s flour sector is operating with little room for error, and the next move in global wheat, freight or insurance could decide whether margins hold or get squeezed further. Investors watching the food chain should keep this one on the radar.
| Entity | Gains | Losses |
|---|---|---|
| Wheat exporters | ▲Higher sales volumes | ▼— |
| Freight and insurance providers | ▲Stronger pricing power | ▼Importers’ margins |
| Senegalese millers | ▲Continued market demand | ▼Rising landed costs |
| Senegalese households | ▲Supply continuity for now | ▼Potential future price pressure |