Seplat Energy has added a potentially material new growth option in Nigeria, with an unexpected oil and gas discovery at Aku-01 that could bolster output, extend reserve life and support future dividends if the volumes prove commercially recoverable.
Seplat Energy Aku-01 Discovery Adds Oil and Gas Upside
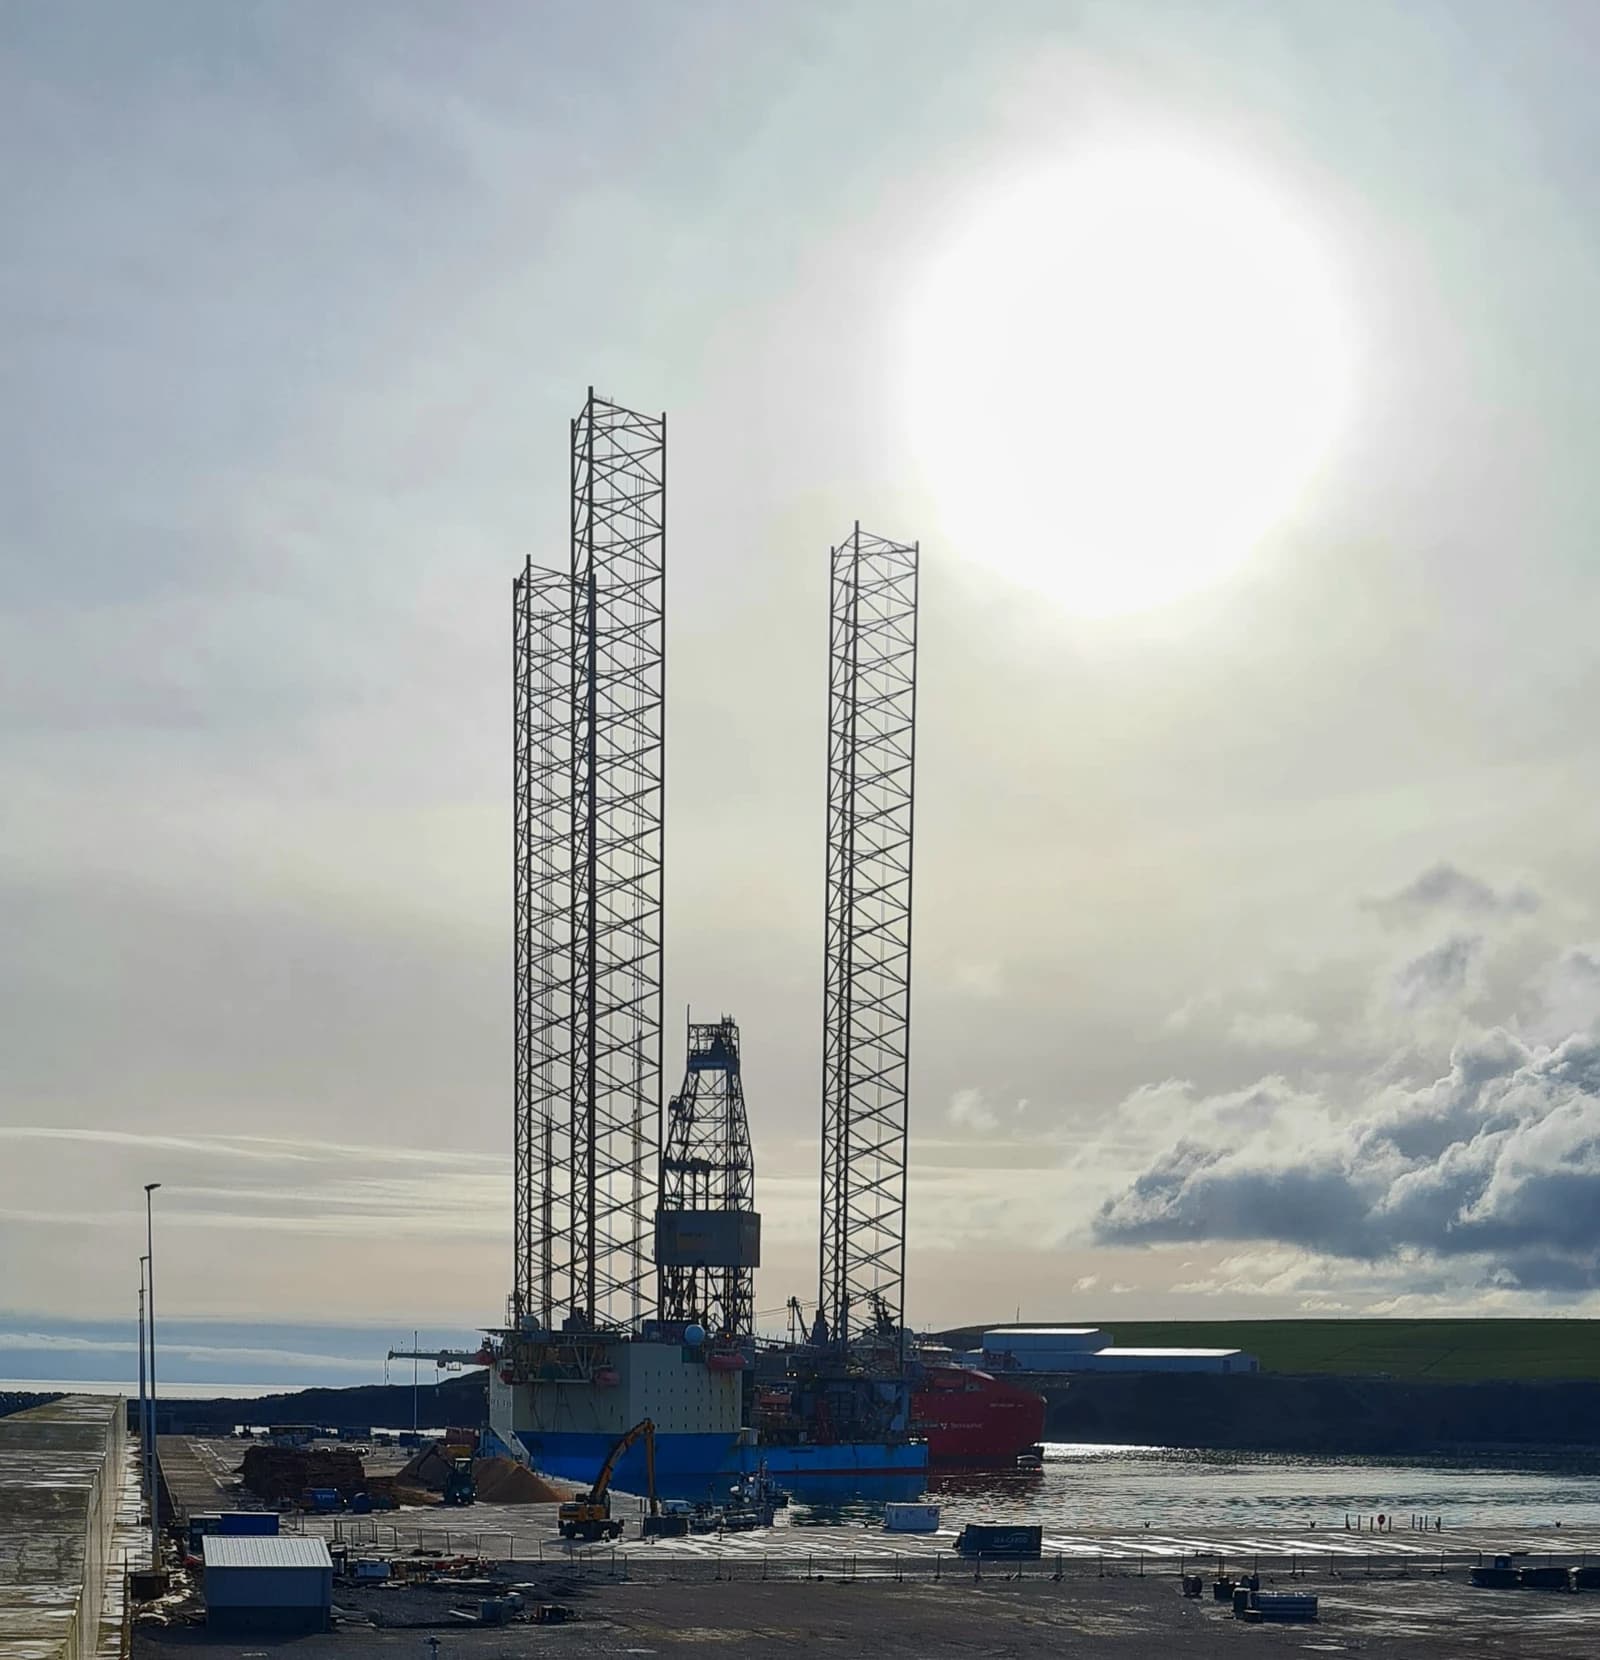
The indigenous producer said preliminary estimates point to 157 billion cubic feet of gas and 19 million barrels of oil in place at the exploration well, drilled in Petroleum Prospecting Licence 2A25 where Seplat holds a 40% operated interest. The oil find matters most: Seplat had not originally planned the well as an oil target, so the discovery broadens the resource base in a licence area already tied to existing infrastructure, improving the odds of faster monetisation.
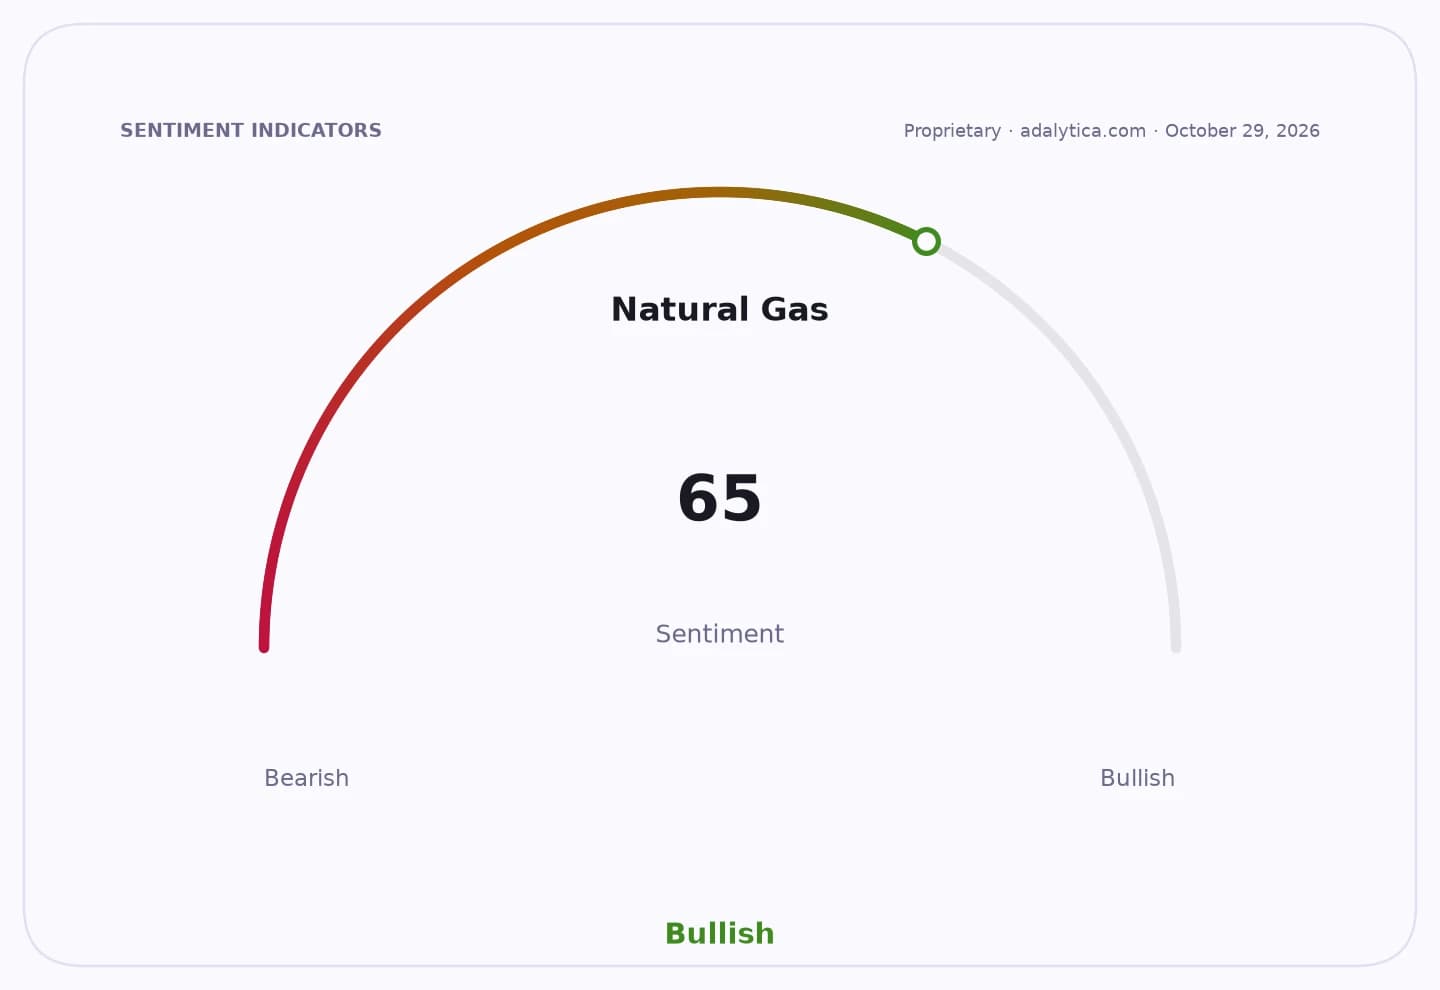
Sentiment Indicators
That is economically important because Nigeria needs projects that can move from discovery to cash flow without years of fresh buildout. Seplat said it is working to complete the well for potential future production and connect it to existing facilities, a route that can sharply cut development costs and shorten the path to revenue. It also said the find reduces uncertainty across four neighbouring prospects and sets up another Aku-area exploration well in 2027, raising the chance of a wider inventory build.
For investors, the discovery strengthens a thesis that Seplat is more than a high-yield Nigerian producer — it is becoming a self-funded growth story with a rising reserve optionality premium. The company is already generating stronger cash flow, with nine-month pre-tax profit rising 52.75% to N1.34 trillion, revenue up to N3.78 trillion and combined production averaging 144,999 boepd, helped by higher gas and condensate volumes. Seplat also kept its full-year underlying dividend guidance at $270 million and expects total 2026 distributions could reach about $410 million if its planned sale of a 10% interest in the NNPCL-SEPNU joint venture closes.
The stock has already rerated sharply, closing at an all-time high of N16,000.10 after a year-to-date gain of about 175%, so the market is no longer pricing Seplat as a sleepy domestic producer. But the Aku-01 discovery gives bulls another reason to stay with the name: more gas for a tightening regional market, more oil upside than the original plan implied, and more leverage to a favorable backdrop of elevated crude prices and strong sector sentiment. If follow-up appraisal confirms commercial volumes, the next catalyst is clearer reserve recognition, more infrastructure-linked production and another leg higher in shareholder returns.
| Entity | Gains | Losses |
|---|---|---|
| Seplat Energy | ▲Reserve upside, future cash flow | ▼Exploration uncertainty |
| Shareholders | ▲Stronger dividend support | ▼Near-term valuation risk |
| Nigeria gas market | ▲More supply optionality | ▼Scarcity premium eases |
| Competitors without new finds | ▲— | ▼Relative growth edge |