Studenac has asked to open pre-bankruptcy proceedings, a move that puts one of Croatia’s largest grocery chains on a formal path to restructuring after rapid expansion was followed by a steep deterioration in profits and a debt pile near €450 million.
Studenac asks for pre-bankruptcy restructuring
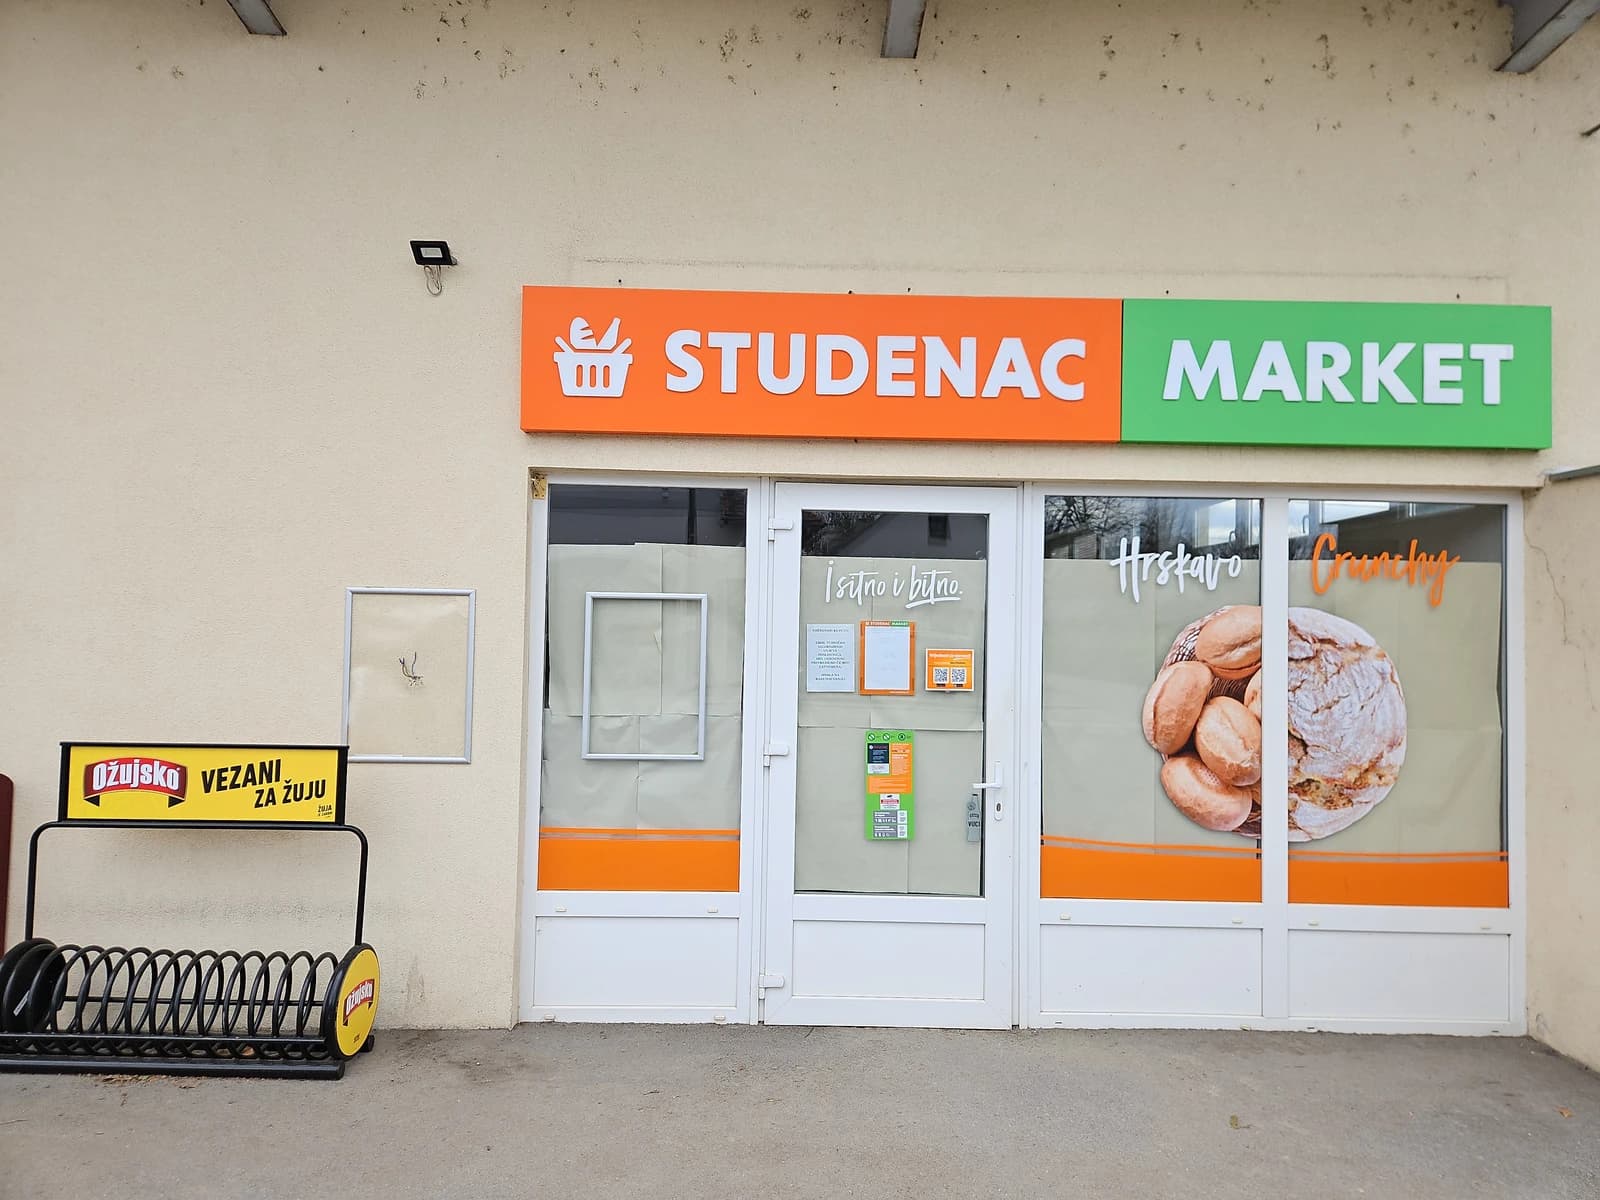
For investors, the significance is clear: this is not just a legal filing, it is a balance-sheet reckoning. Studenac says its stores remain open and daily operations continue, but the company’s blocked bank account and failure to secure extensions on existing credit lines show how quickly aggressive growth can turn into a liquidity problem when earnings do not keep up with borrowing costs and acquisition spending.
Sentiment IndicatorsⓘProprietary · adalytica.com · October 1, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
That matters well beyond one retailer. Studenac employs more than 7,000 people and operates more than 1,400 stores across Croatia, including in smaller towns and communities where it is often a key local supplier. If creditors force a deep restructuring, the outcome could influence jobs, supplier payments, store count and the pace of investment in the country’s retail sector.
The numbers explain why the pressure built so fast. Revenue rose 12.7% to €854.4 million in 2025, but the company still posted a net loss of €30.6 million. EBITDA fell to €51.8 million from €65.8 million a year earlier, while EBIT swung from a €22.5 million profit to a €5.4 million loss. That is the kind of earnings decline that leaves even a growing chain vulnerable when debt service starts to bite.
Studenac’s ownership also matters. The company has been controlled since 2018 by Poland’s Enterprise Investors, and its earlier plan for a stock-market listing in 2024 never happened. Without fresh equity from an IPO, the retailer kept expanding through acquisitions and new store openings while leaning more heavily on borrowed money. That is often a workable strategy in a low-rate, high-growth phase, but it becomes far less forgiving when profitability weakens.
Pre-bankruptcy proceedings are designed to give a business breathing room while it negotiates with banks, suppliers and other creditors. In practical terms, that can mean debt write-downs, extended maturities, new capital from the current owner or the arrival of a strategic investor. It can also mean painful operational changes, including store closures, automation and job cuts if the restructuring goes deep enough.
For long-term investors, the key lesson is broader than Studenac itself. Growth is valuable only when it compounds into durable cash flow. When expansion outruns margins, the market eventually demands a reset. The next few months will determine whether Studenac can stabilize as a leaner retailer or whether this becomes a cautionary tale for companies that grow fast but borrow faster.
| Entity | Gains | Losses |
|---|---|---|
| Studenac creditors | ▲Chance to negotiate repayment | ▼Risk of losses and delays |
| Studenac management | ▲Breathing room to restructure | ▼Loss of flexibility |
| Enterprise Investors | ▲Opportunity to recapitalize and retain control | ▼More capital at risk |
| Employees and suppliers | ▲Business may keep operating | ▼Possible cuts and payment stress |