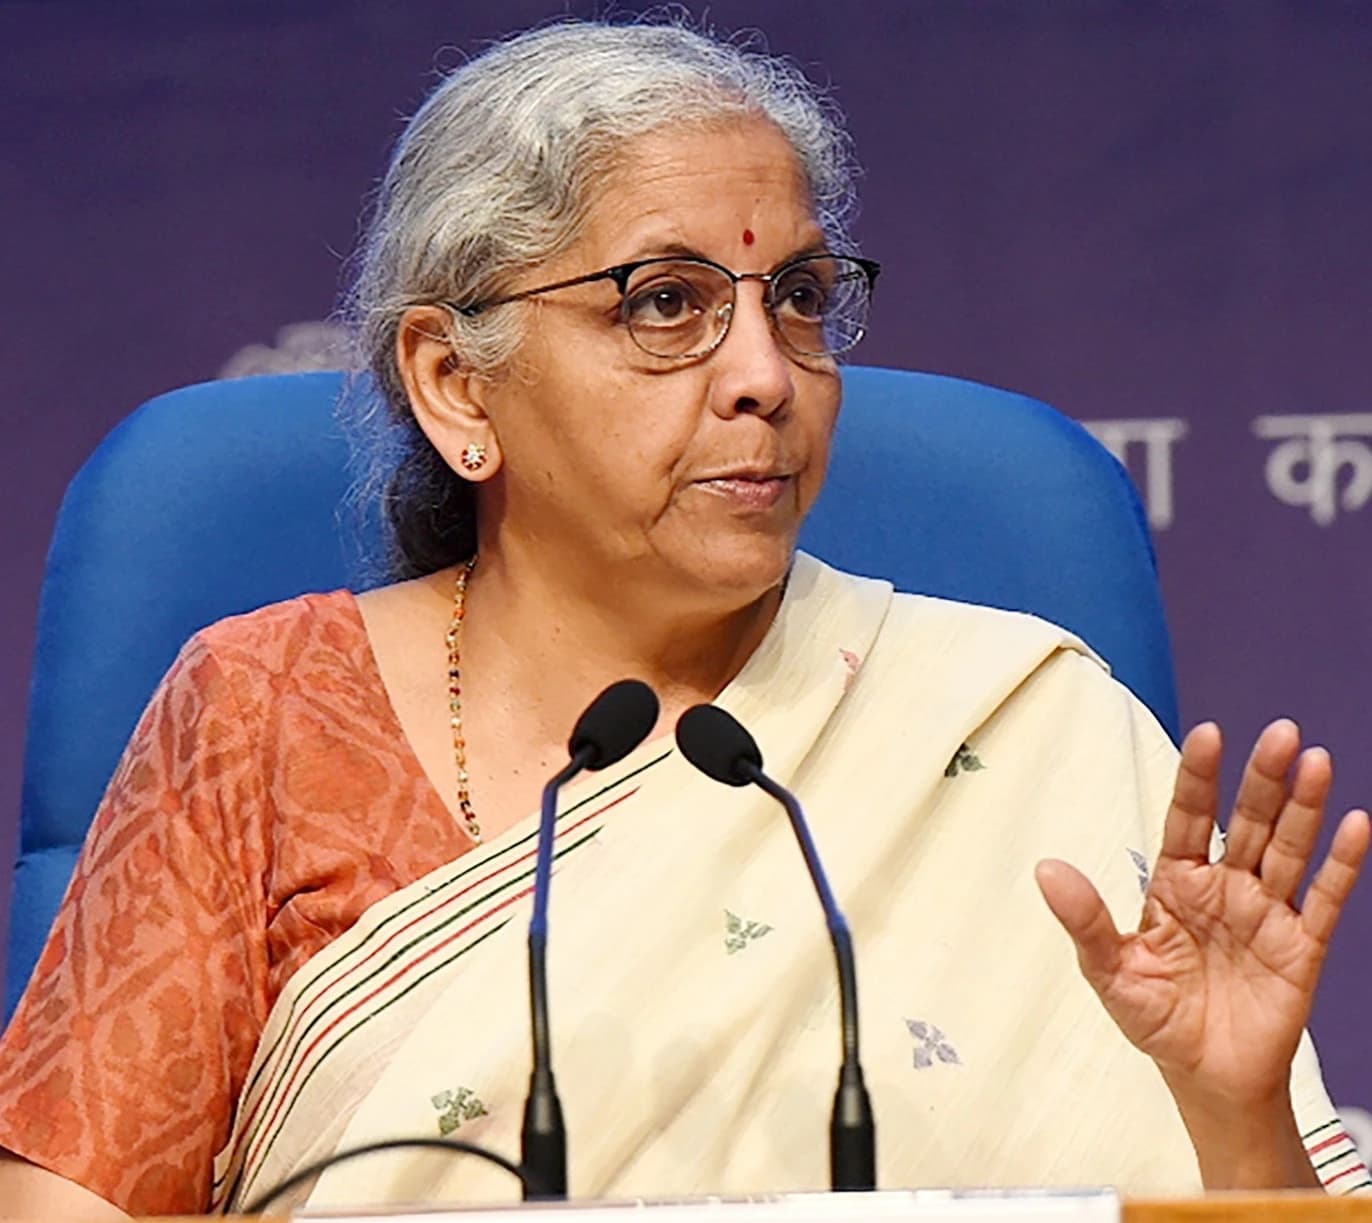
Tata Group’s board has forced through another five-year term for chairman N. Chandrasekaran after weeks of turmoil with the conglomerate’s controlling Tata Trusts, underscoring how succession disputes at India’s biggest family-controlled companies can spill into corporate governance and investor confidence.
Tata Group extends Chandrasekaran’s chairman term
The decision came after Chandrasekaran had already gone from seeking reappointment to announcing his exit and then returning to the role, a reversal that highlighted the lack of a clear transition plan at one of India’s most important business groups. Tata’s annual revenue is roughly equal to about 5% of India’s GDP, and its businesses stretch from Jaguar Land Rover to Apple iPhone assembly and strategic bets in semiconductors, batteries and electronics manufacturing.
Sentiment IndicatorsⓘProprietary · adalytica.com · September 27, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
For investors, the issue is not just who leads Tata Sons, but whether boardrooms across India can manage succession without public power struggles. Analysts and governance advisers say the Tata episode has become a warning sign for global capital that decision-making in India’s corporate elite still depends too heavily on personalities and family control, rather than process and institutional discipline.
The conflict intensified after the death of former patriarch Ratan Tata in 2024, leaving unresolved questions over the balance of power between the board and the Tata Trusts, chaired by Noel Tata. Concerns over losses at some group companies, heavy investment spending and the possibility of listing Tata Sons added to the strain, while independent advisers said the board’s pushback against the controlling shareholder set an uncomfortable precedent.
The broader backdrop is a wave of succession problems across India Inc., from HDFC Bank’s abrupt leadership changes to the sudden resignation at Godrej Consumer Products. With family-controlled businesses dominating the economy and UBS estimating a $382 billion intergenerational wealth transfer ahead, succession planning is becoming one of the key governance tests for Indian companies and for foreign investors assessing the durability of their earnings.
The next risk is whether the Tata resolution ends the dispute or merely delays another round of tensions over capital allocation and ownership structure. For markets, any prolonged leadership friction at a group of Tata’s scale could weigh on sentiment around Indian conglomerates, especially as the country tries to attract long-term foreign capital into manufacturing and strategic sectors.
| Entity | Gains | Losses |
|---|---|---|
| Chandrasekaran / Tata board | ▲Leadership continuity | ▼Boardroom uncertainty |
| Tata Trusts / Noel Tata | ▲Influence over succession debate | ▼Public governance setback |
| Foreign investors | ▲Clearer near-term leadership | ▼Confidence in India governance |
| India Inc. family firms | ▲Pressure to improve succession planning | ▼Scrutiny over control-heavy structures |