Tokyo’s office market is drawing fresh capital despite Japan’s borrowing costs at a 31-year high, with rising rents helping push commercial-property investment to its strongest third quarter since 2007 and giving Blackstone a favorable backdrop to sell.
Tokyo Office Rents Lift Japan Property Deals
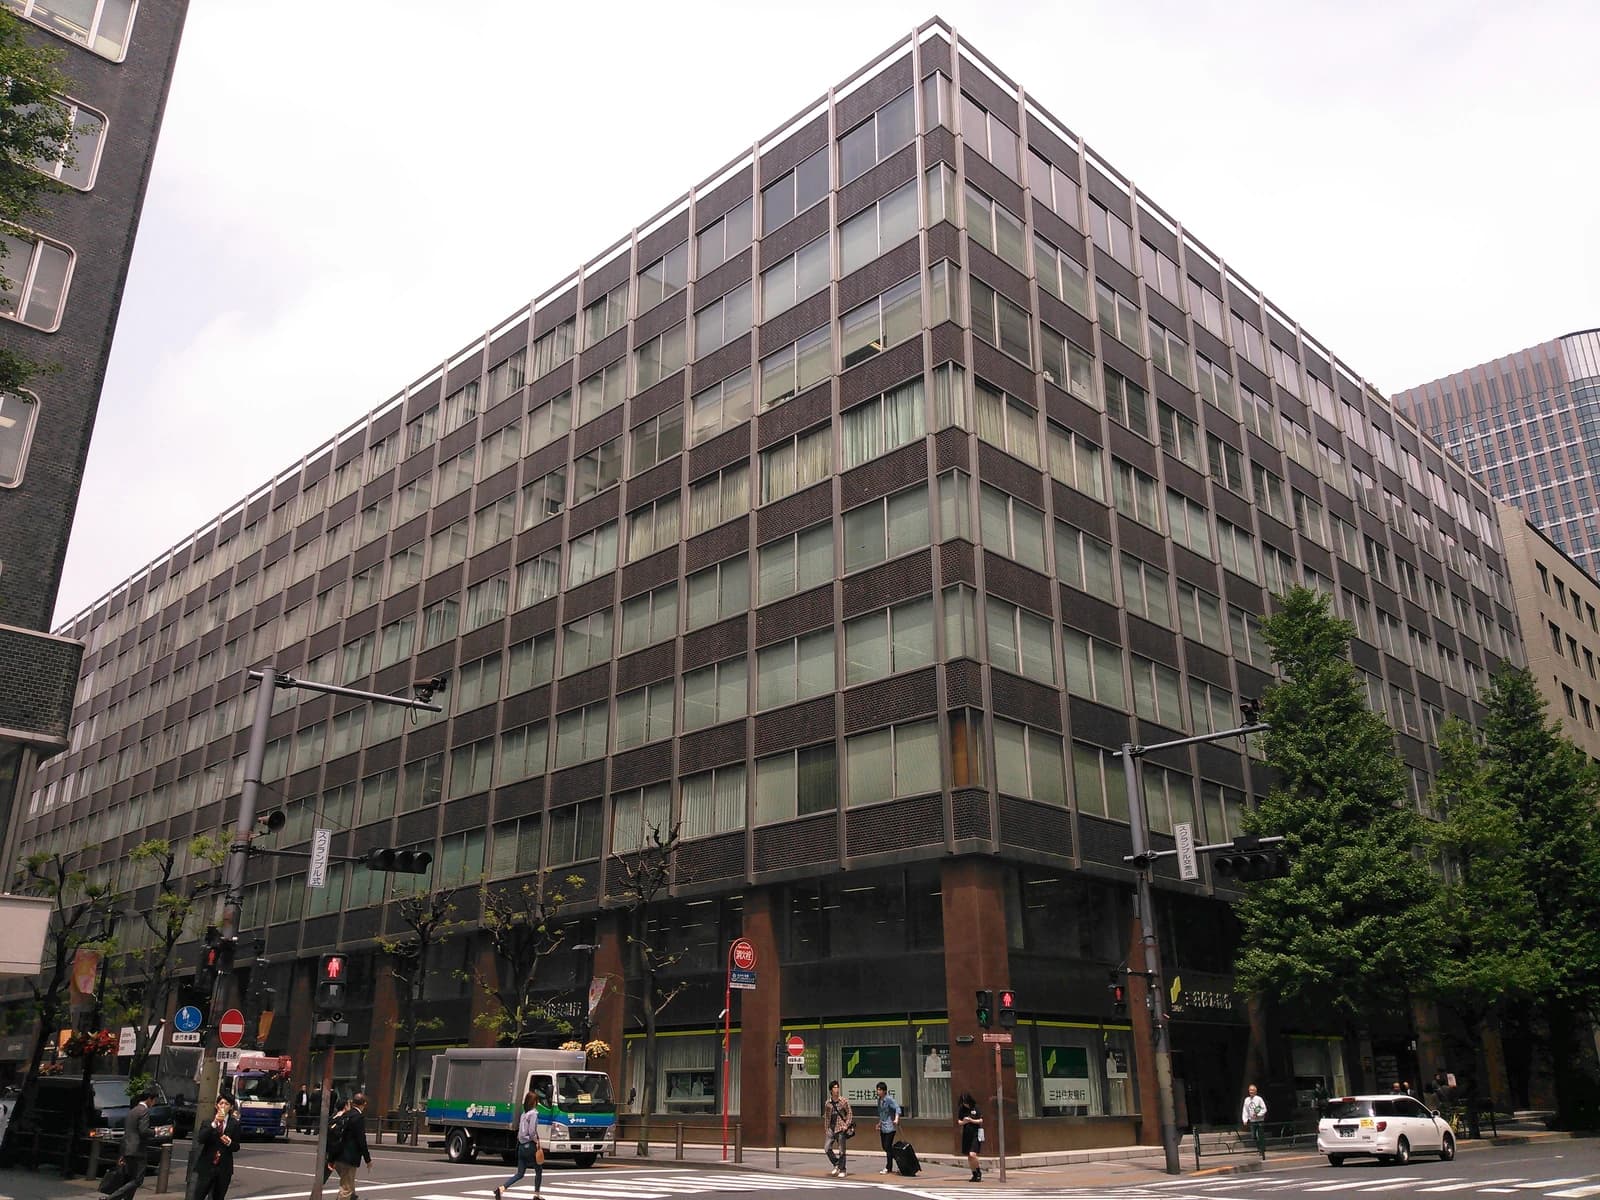
The key driver is not cheaper financing but stronger income prospects. JLL said commercial-property investment across Japan reached ¥2 trillion, or about $13 billion, in the third quarter, with office assets accounting for 36% of deal volume and nearly 70% of the money flowing into the Tokyo region.
Investors are paying up because rents are still moving higher, creating visible upside in assets that were leased below current market levels. “Rent is increasing so investors are still able to see huge amounts of rental upside,” Koji Naito, JLL Japan’s research director of capital markets, said, adding that the gap between existing contracts and market rates is supporting transactions even with rates elevated.
That backdrop matters for landlords and private equity firms alike. For owners such as Blackstone, which is planning a sale, a tighter Tokyo office market can expand exit values and improve timing, while buyers can underwrite rent growth against a backdrop of limited supply and a deep institutional market.
The deal activity also underscores how Japan’s property market is being driven more by fundamentals than by financing conditions. Higher rents can offset the drag from a high-rate environment by lifting net operating income, a crucial measure for real estate valuations and one that often matters more to investors than headline borrowing costs.
For investors, the story is a mix of support and risk: office landlords and sellers may benefit from rising valuations, while buyers face a less forgiving entry point if rent growth slows. The next test will be whether Tokyo office demand and pricing momentum can hold through year-end, when more asset sales and financing decisions are likely to hit the market.
| Entity | Gains | Losses |
|---|---|---|
| Tokyo office landlords | ▲Higher rents, stronger valuations | ▼ |
| Blackstone | ▲Better sale pricing, easier exit | ▼ |
| Buyers of office assets | ▲Future rent upside | ▼Higher entry prices |
| Lenders and brokers | ▲More deal flow | ▼More selective underwriting |