Asian stocks are slipping ahead of TSMC’s latest earnings report because investors know one company’s results can now speak for the whole AI supply chain. If Taiwan Semiconductor Manufacturing Co. confirms another quarter of record profit and raises the market’s confidence in AI chip demand, it could steady a region that has become increasingly dependent on the durability of the semiconductor boom.
TSMC Earnings Could Reset AI Chip Sentiment
That is why this matters far beyond Taiwan. TSMC sits at the center of the world’s most important technology buildout, producing the advanced chips that power artificial intelligence systems for Nvidia and other big designers. When TSMC shows that demand is still outrunning supply, it reinforces the idea that AI spending remains a multi-year capital cycle, not a short-lived trade. For investors, that means the earnings call could help determine whether the recent pullback in Asian chip shares is a buying opportunity or the start of a more cautious phase.
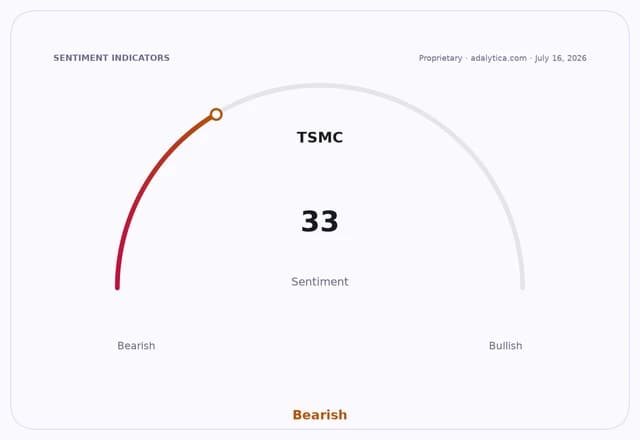
Sentiment IndicatorsⓘProprietary · adalytica.com · July 16, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The setup is strong. TSMC said June revenue jumped 67.9% from a year earlier, signaling that its second quarter likely delivered another record. The company is expected to post its fifth straight quarter of record profit, and management has already warned that AI chip demand should stay ahead of supply for years. That is a powerful combination for long-term investors: pricing power, scarce capacity and a customer base willing to keep spending on next-generation computing.
The market is also reading the stock itself as stretched but still resilient. TSMC’s shares have climbed sharply this year and remain well above the 50-day moving average and the 200-day moving average, a sign of a powerful longer-term uptrend even after recent volatility. The 14-day RSI has eased from overbought levels, suggesting the stock has cooled from its earlier sprint rather than broken its broader pattern. For investors, that matters because great businesses rarely move in a straight line; periods of consolidation can be healthy when the underlying earnings engine is still accelerating.
TSMC — 30-day sentimentadalytica.com
Explore this data interactively — full history, time series and cross-market comparisons.Open AlphaPulse
The bigger story is the one underneath the earnings print. If TSMC continues to say that AI demand exceeds supply, it strengthens the case for the entire ecosystem: chip designers, equipment makers, foundries and cloud companies all benefit from a prolonged buildout. It also explains why Asian markets are so sensitive to this report. The region has become a proxy for the global AI trade, and TSMC is one of its clearest bellwethers.
There are risks, of course. Semiconductor demand can be lumpy, geopolitics around Taiwan never disappears, and investors are already pricing in a lot of good news. But for patient investors, the long-term case remains intact. TSMC is still the indispensable manufacturer in the AI era, and that kind of moat is exactly what tends to compound over years, not quarters. If the earnings report confirms the revenue momentum already on display, TSMC should stay on every long-term investor’s watchlist.
| Entity | Gains | Losses |
|---|---|---|
| TSMC | ▲Record earnings momentum | ▼Higher expectations |
| AI chip customers | ▲Access to leading-edge capacity | ▼Tighter supply |
| Asian semiconductor bulls | ▲Confirmation of the AI cycle | ▼None if results disappoint |
| Short-term skeptics | ▲Chance to buy dips | ▼Missed upside if guidance stays strong |