Turkey’s short-term external debt stock climbed 3.8% in July to $177.1 billion, underscoring a heavier near-term refinancing burden just as global funding costs remain elevated and investor appetite for emerging-market credit looks fragile.
Turkey Short-Term External Debt Rises 3.8% in July
The increase matters because short-term debt is the most immediately vulnerable part of a country’s external balance sheet: it must be rolled over quickly, often at whatever terms lenders are willing to offer. For Turkey, where foreign-currency funding is a persistent pressure point, a larger short-term debt stock raises the stakes for reserve management, access to offshore liquidity and the stability of the banking system.
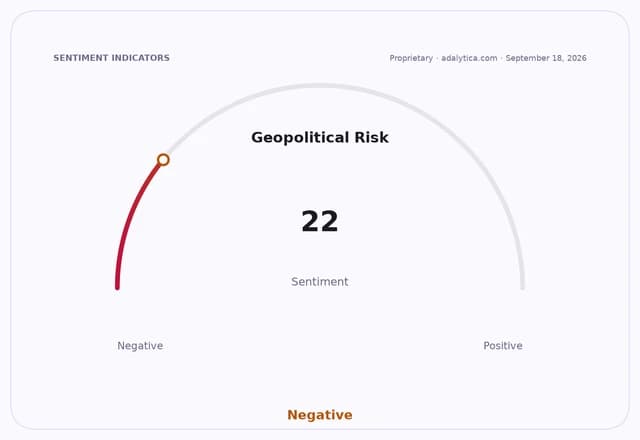
Sentiment IndicatorsⓘProprietary · adalytica.com · September 18, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The central bank said the stock measured by remaining maturity — which captures debt due within one year regardless of original tenor — stood at $248.1 billion. That broader figure shows the refinancing task is larger than the headline short-term balance alone suggests.
Banks drove much of the increase. Short-term external debt tied to banks rose 4.3% to $77.8 billion, while domestic banks’ short-term loans and securities liabilities to non-residents jumped 23.5% to $9.8 billion. Deposits held by foreign banks in Turkey climbed 7% to $19.8 billion, and non-bank deposits rose 1.1% to $21.6 billion. On the corporate side, short-term debt from other sectors increased 3.6% to $74.7 billion, with trade-credit liabilities up 2.4% to $65.1 billion and cash-loan liabilities up 13.1% to $9.7 billion.
The currency mix helps explain why investors watch the data closely. Dollars made up 34.3% of the stock, euros 26.5% and lira 26%, leaving Turkey exposed to shifts in external funding conditions and foreign-exchange liquidity. That exposure is especially relevant in an environment where the dollar remains firm and euro-area trade sentiment has weakened sharply, according to Adalytica’s trade signals.
For investors, the read-through is twofold. In the bullish case, higher short-term external debt can reflect stronger trade activity and a banking system that is still able to access funding. In the bearish case, it signals rising rollover needs that can amplify pressure if global risk appetite deteriorates or if domestic policy credibility slips.
The issue is not just a balance-sheet statistic. It feeds directly into Turkey’s broader macro trade-off between growth, currency stability and external financing. A larger stock of debt coming due within a year means more frequent testing of lender confidence, more sensitivity to the cost of dollar funding and a greater chance that any market wobble turns quickly into a liquidity story.
The next focal points will be reserve trends, bank rollover ratios and whether short-term liabilities keep rising faster than foreign-exchange buffers. If they do, the debt profile becomes harder to manage and more expensive to refinance, which is exactly the kind of setup that markets tend to reprice fast.
| Entity | Gains | Losses |
|---|---|---|
| Turkish banks | ▲Funding access if rollovers hold | ▼Refinancing pressure if markets tighten |
| Turkish corporates | ▲Trade credit support | ▼FX mismatch risk |
| Foreign lenders | ▲Higher lending volumes | ▼Greater rollover exposure |
| Turkish authorities | ▲Potentially stronger external financing flow | ▼More pressure on reserves and policy credibility |