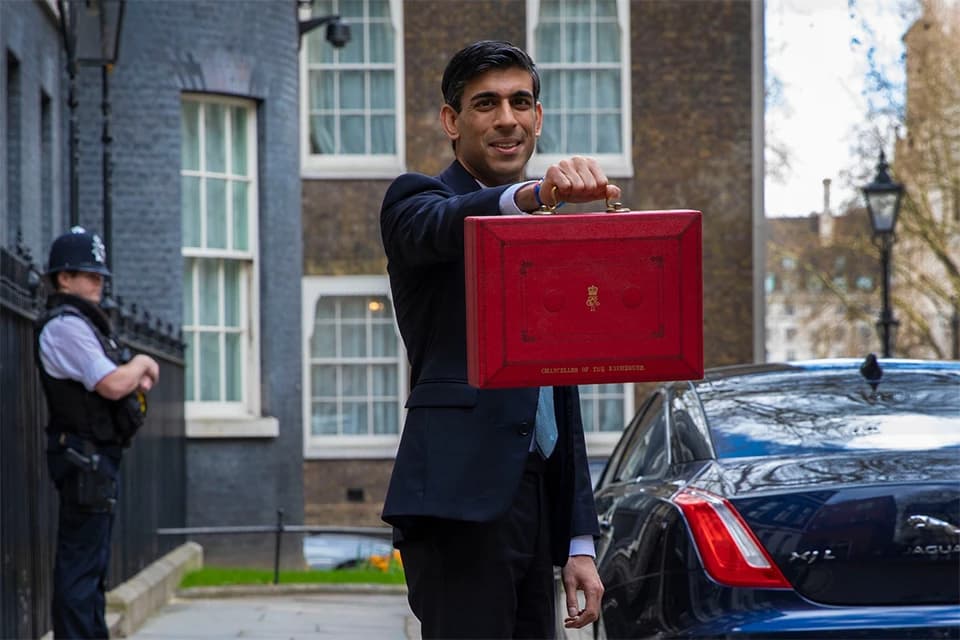
Consumer confidence in Britain has slumped at the fastest pace since the pandemic’s early days, a warning that households are bracing for a weaker economy just as finance minister John Healy prepares a budget aimed at giving families and businesses “breathing room.”
UK Consumer Confidence Falls Before Budget
The GfK index dropped 11 points to minus 24 in October, its lowest since April and well below economist forecasts. That is the sharpest monthly fall since April 2020, when the first Covid lockdown hit, and outside the pandemic it is the biggest drop since the Brexit vote in 2016. For investors, the message is clear: Britain’s consumer-led recovery is losing momentum at exactly the moment when policymakers need confidence to stabilize.
Sentiment Indicators
The deterioration matters because it hits the part of the economy that drives a large share of UK growth. GfK said the slide was not caused by one event but by a build-up of pressure from sticky inflation, the Middle East conflict and rising household budget strains. Consumers also turned more cautious on major purchases, with the big-ticket buying gauge falling to a more than two-year low. That points to softer retail spending, weaker discretionary demand and a tougher backdrop for domestic businesses heading into year-end trading.
The timing is awkward for Healy, who has tried to sound upbeat about the economy and point to growth in the first half of the year. Instead, the latest survey adds political and fiscal pressure ahead of next week’s budget, where any help for households must be balanced against the risk of stoking inflation or complicating the Bank of England’s next move. Markets are already looking for another rate increase next month, and rising inflation expectations in the survey will not make the central bank’s job any easier.
This is where investors should pay attention. A confidence shock of this size usually does not stay confined to sentiment data; it tends to flow through to retail sales, leisure spending, banks’ consumer lending books and small-cap UK cyclicals. Domestic-facing shares are vulnerable if households pull back further, while retailers and discretionary names may need stronger discounting to defend volumes. At the same time, the data strengthens the case for selective exposure to defensive sectors and companies with overseas revenue, pricing power or essential demand.
The broader narrative is that Britain is entering the budget with consumers on the back foot, inflation still biting and policy makers trying to reassure markets that growth can hold up. If next week’s fiscal package fails to restore confidence, the risk is not just softer shopping — it is a deeper slowdown that forces investors to reprice UK domestic demand and the pound-sensitive parts of the market.
| Entity | Gains | Losses |
|---|---|---|
| Defensive stocks | ▲Relative demand resilience | ▼Less policy uncertainty |
| UK retailers | ▲Short-term fiscal support | ▼Consumer pullback |
| Bank of England | ▲Lower demand pressure | ▼Inflation expectations |
| UK discretionary shares | ▲None | ▼Weaker spending and margins |