US stocks ended the week higher as investors shifted their focus to third-quarter earnings and the next inflation reading, with lower geopolitical anxiety and still-solid profit expectations helping keep Wall Street near record levels.
US Stocks Rise as Earnings and Inflation Data Near
The Dow Jones Industrial Average rose 423.31 points, or 0.83%, to 51,654.95 on the Oct. 9-10 session, while the S&P 500 gained 0.59% to 7,811.51 and the Nasdaq Composite advanced 0.64% to 27,366.17. All three major gauges finished the week in the green, though small-cap stocks as measured by the Russell 2000 still ended below their Oct. 2 close, underscoring uneven risk appetite beneath the headline gains.
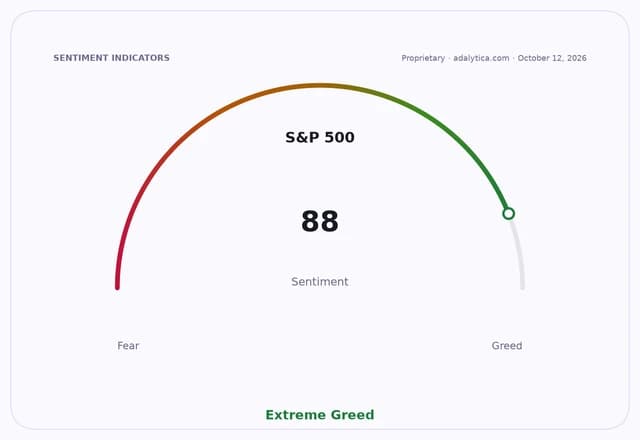
The move matters because it comes with investors balancing two forces that usually pull stocks in opposite directions: the prospect of strong corporate earnings and the risk that inflation stays sticky enough to keep interest rates elevated. The market is also entering a critical stretch for banks and other bellwethers, with JPMorgan Chase, Bank of America, Goldman Sachs and Wells Fargo due to report next week.
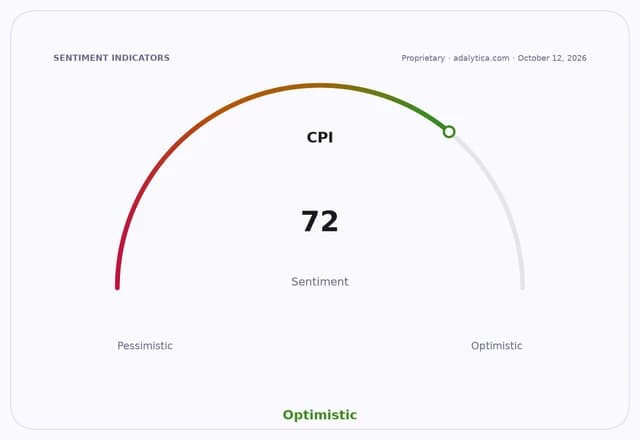
Rate and macro expectations remain central. The market is waiting for inflation data that will help shape the outlook for the Federal Reserve, even as the 10-year Treasury yield held around 5.23%, a level that keeps pressure on valuations for growth stocks and adds to financing costs across the economy. Despite that backdrop, the S&P 500 is trading well above its 50-day moving average and 200-day moving average, while the Nasdaq has also stayed comfortably above those long-term technical levels.
CPIAUCSL vs CPILFESL — macro contextadalytica.com
Explore this data interactively — full history, time series and cross-market comparisons.Open AlphaPulse
Geopolitics also helped sentiment. Stocks improved after President Donald Trump said the U.S. would not launch attacks on Iran before the midterm election and said Washington and Tehran had made positive progress in talks aimed at ending the conflict rattling markets. Oil initially fell on the comments before both WTI and Brent settled 0.4% higher, a reminder that energy and inflation risks are still not fully off the table.
Earnings expectations remain a major support. LSEG data shows analysts expect S&P 500 profits to rise 30.6% in the third quarter from a year earlier, with energy earnings seen jumping 123% and technology profits up 66.5%. That backdrop is helping offset concern that higher rates and geopolitical uncertainty could slow the rally.
Stock moves were mixed at the company level. Humana jumped 11.6% after U.S. government data showed 95% of its Medicare Advantage members are in 4-star-or-better plans for 2027, while Apple fell 1.1% after reports it asked suppliers to cut output of some iPhone 18 Pro components as higher memory chip costs and elevated prices threaten demand.
Telecom stocks were hit harder after SpaceX agreed to buy a nationwide low-frequency wireless spectrum portfolio, intensifying competition for T-Mobile US, AT&T and Verizon. Shares of the three carriers fell between 8.8% and 13.3%, reflecting investor concern that SpaceX could become a more direct rival in parts of the wireless market.
With earnings season about to accelerate and inflation still the key macro risk, traders are likely to keep rotating quickly between rate-sensitive sectors, defensives and companies with clear margin power. The next U.S. price report and the first wave of bank results will help determine whether the week’s gains can extend or whether stocks are simply buying time near record highs.
| Entity | Gains | Losses |
|---|---|---|
| Large-cap US equities | ▲Near-record levels, weekly gains | ▼Sticky inflation risk |
| S&P 500 banks | ▲Earnings upside setup | ▼Higher rates, scrutiny |
| Humana | ▲Medicare Advantage rating boost | ▼Competitive pressure in healthcare |
| Apple and telecom rivals | ▲None from this news | ▼Demand and spectrum competition risks |