Higher VND deposit rates are pulling money back into Vietnamese banks and away from gold, equities and property, as savings now offer returns that can rival — and in some cases outshine — the cash flow from riskier assets.
Vietnam Bank Deposits Draw Money From Stocks and Property
That shift matters because it changes the relative value of holding cash in an economy where borrowing costs have also risen. When deposits can pay around 9% a year, a household with 1 billion dong can earn roughly 90 million dong annually without daily mark-to-market swings, while investors in stocks, land or gold must still absorb price volatility, fees and, in property, illiquidity and leverage risk.
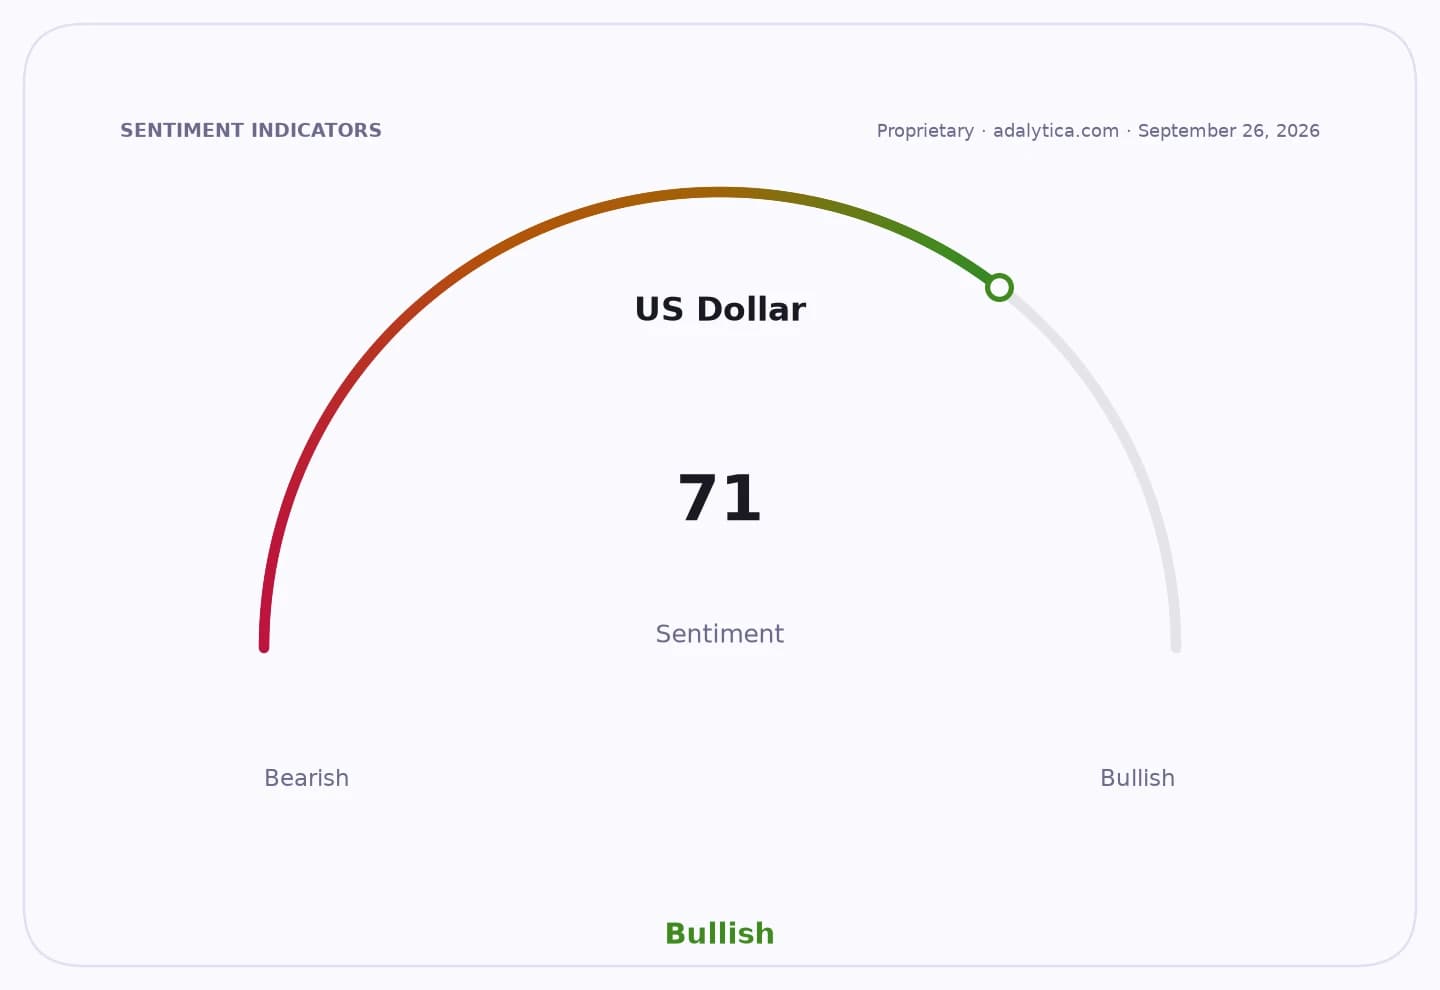
Sentiment IndicatorsⓘProprietary · adalytica.com · October 3, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The clearest sign is in retail deposit flows. State Bank of Vietnam data showed household deposits rose 8.6% in the first seven months of the year, far faster than deposits from economic organizations, which increased just 1%. Vietcap’s Quân Vũ said bank discussions suggest the migration into savings has continued in the third quarter, while trading liquidity on Vietnam’s three stock exchanges has weakened through the year, with average daily value sliding from about 35,000 billion dong in the first quarter to 24,000 billion dong in the second and nearly 19,000 billion dong in the third.
The appeal of cash is being reinforced by a tougher backdrop for other assets. In real estate, rising rates are hitting both sides of the trade: borrowers face bigger debt-service burdens, while cash buyers now have a stronger alternative in bank deposits. SGI Capital said many mortgages taken out during the low-rate period have reset to 13% to 16% a year, a level that can quickly squeeze household cash flow and force some owners to sell assets to cut debt. That dynamic helps explain the growing number of “cut loss” listings across apartments, land plots and resort homes.
Gold and stocks are also losing some of their defensive allure in the eyes of local savers. Investors who bought equities or bullion and watched values swing sharply are increasingly comparing them with the certainty of deposit income. One forum anecdote — a homeowner selling a 5 billion dong apartment, placing the proceeds in a bank and renting the unit back — captures the arithmetic behind the shift, even if it is not representative of the whole market.
Still, analysts say the rotation into deposits is not a one-way trade. Higher bank rates can win cash in the short term, but they can also act as a drag on broader risk appetite and on the valuations of assets that depend on cheap leverage. For stocks, that means earnings growth and market reform will be needed to lure money back. For property, it means prices must justify not just mortgage costs, but the opportunity cost of giving up a near-9% risk-free return.
Vietcap said that if corporate profits continue to improve, geopolitical tensions ease and market infrastructure reforms advance, investors could return to equities even before deposit rates fall meaningfully. For now, though, the message from Vietnamese savers is clear: when VND pays more, cash becomes a competitor, not just a parking place.
| Entity | Gains | Losses |
|---|---|---|
| Bank depositors | ▲Higher VND returns | ▼Lower liquidity elsewhere |
| Banks | ▲More retail funding | ▼Higher funding costs |
| Stocks and funds | ▲Potential future inflows | ▼Near-term cash outflows |
| Property sellers | ▲Faster deleveraging | ▼Lower prices and demand |