Vietnam’s banks are pushing deposit rates back to as high as 9% as lenders compete to lock in funding, a sign that pressure to mobilize capital is rising again even as policymakers try to keep credit growth, lending costs and the dong under control.
Vietnam banks raise deposit rates to 9%
The move matters because higher deposit rates usually feed through to borrowing costs for households and companies, raising the risk that Vietnam’s loan market gets tighter just as the economy is trying to sustain growth. It also suggests banks are no longer comfortable relying on cheap deposits alone and are paying up to secure liquidity.
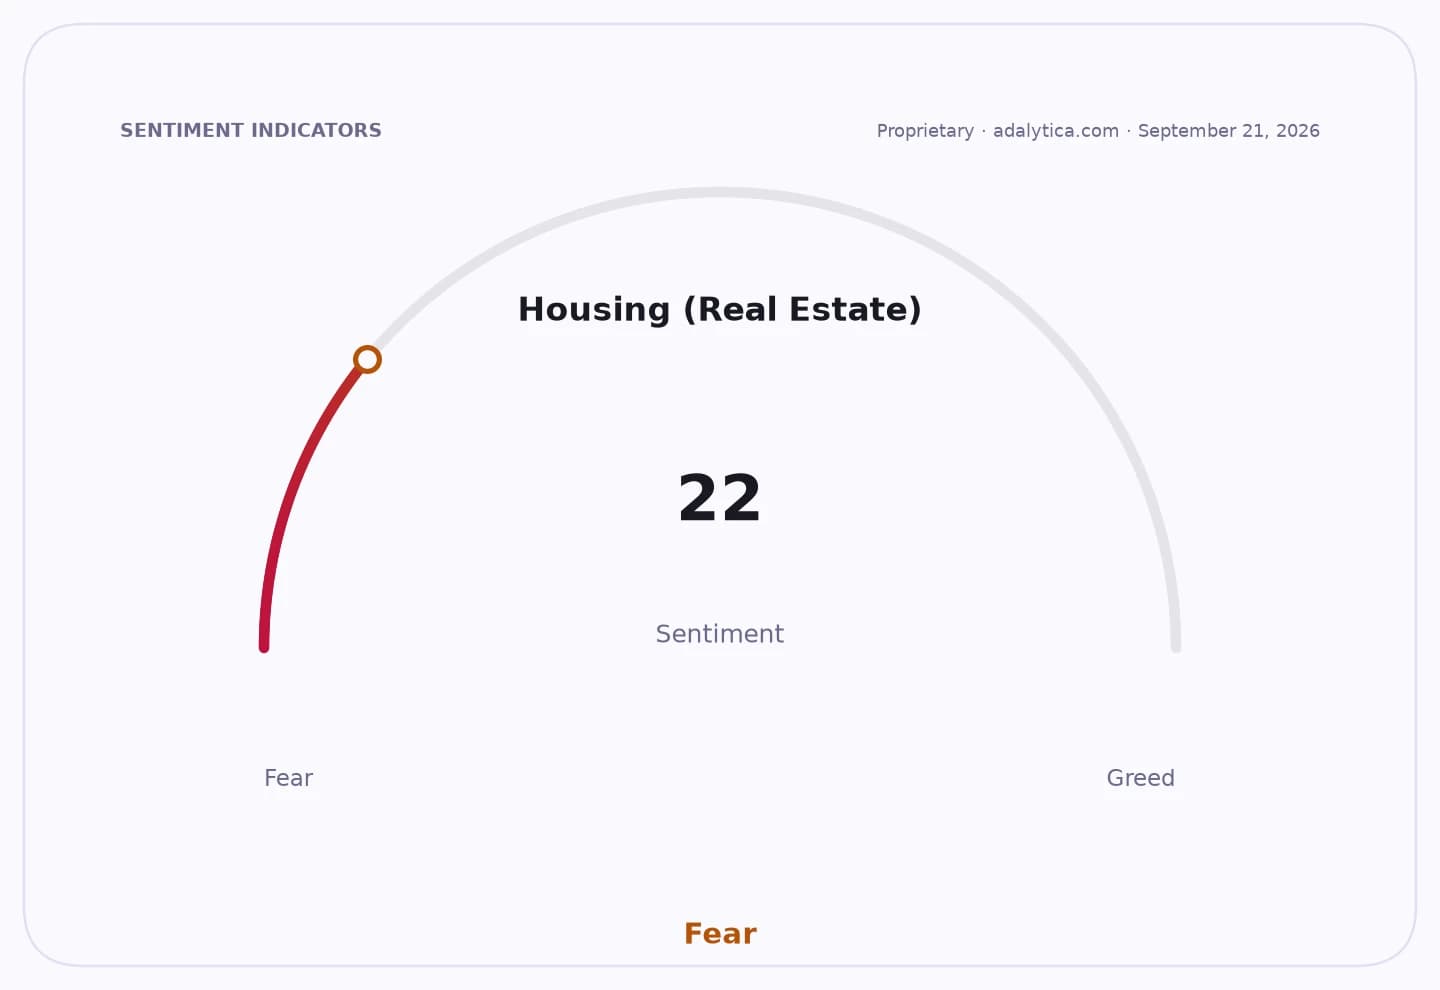
Sentiment IndicatorsⓘProprietary · adalytica.com · August 24, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
That dynamic has broad market consequences. For savers, 9% offers an attractive return in a still-uncertain currency and rate environment. For borrowers, it can mean more expensive working capital and mortgage costs, which can weigh on consumption, property demand and business expansion.
The State Bank of Vietnam has kept the central dong exchange rate at 25,600 per dollar after a period of mild adjustments earlier in the month, underscoring a policy preference for stability. At the same time, the banking system is showing signs of strain: loan rates are drawing scrutiny, while deposits have reached record levels, suggesting households are still sending cash into the formal financial system even as banks pay more to keep it there.
Market-wise, the deposit-rate increase points to a renewed funding contest across the sector rather than an isolated pricing move. That tends to favor banks with stronger franchise deposits and lower funding costs, while smaller lenders may need to offer higher rates to stay competitive, compressing margins.
Vietnamese equities have not yet shown a broad repricing in the data, but BID has been trading near 9.86-9.90, with a recent spike in volume and an RSI that briefly climbed into overbought territory before cooling. Technicals alone do not drive the story, but they suggest investors are watching the sector closely as funding conditions shift.
The key question now is whether the 9% offers are a short-lived lure to meet year-end funding needs or the start of a broader repricing in Vietnam’s deposit market. If rate competition spreads, banks may face tighter net interest margins and borrowers could feel the pinch sooner.
| Entity | Gains | Losses |
|---|---|---|
| Savers | ▲Higher deposit yields | ▼Lower-rate accounts |
| Banks with strong deposits | ▲Cheaper funding edge | ▼Less pressure |
| Smaller lenders | ▲Higher inflows if they raise rates | ▼Margin compression |
| Borrowers | ▲— | ▼Higher loan costs |