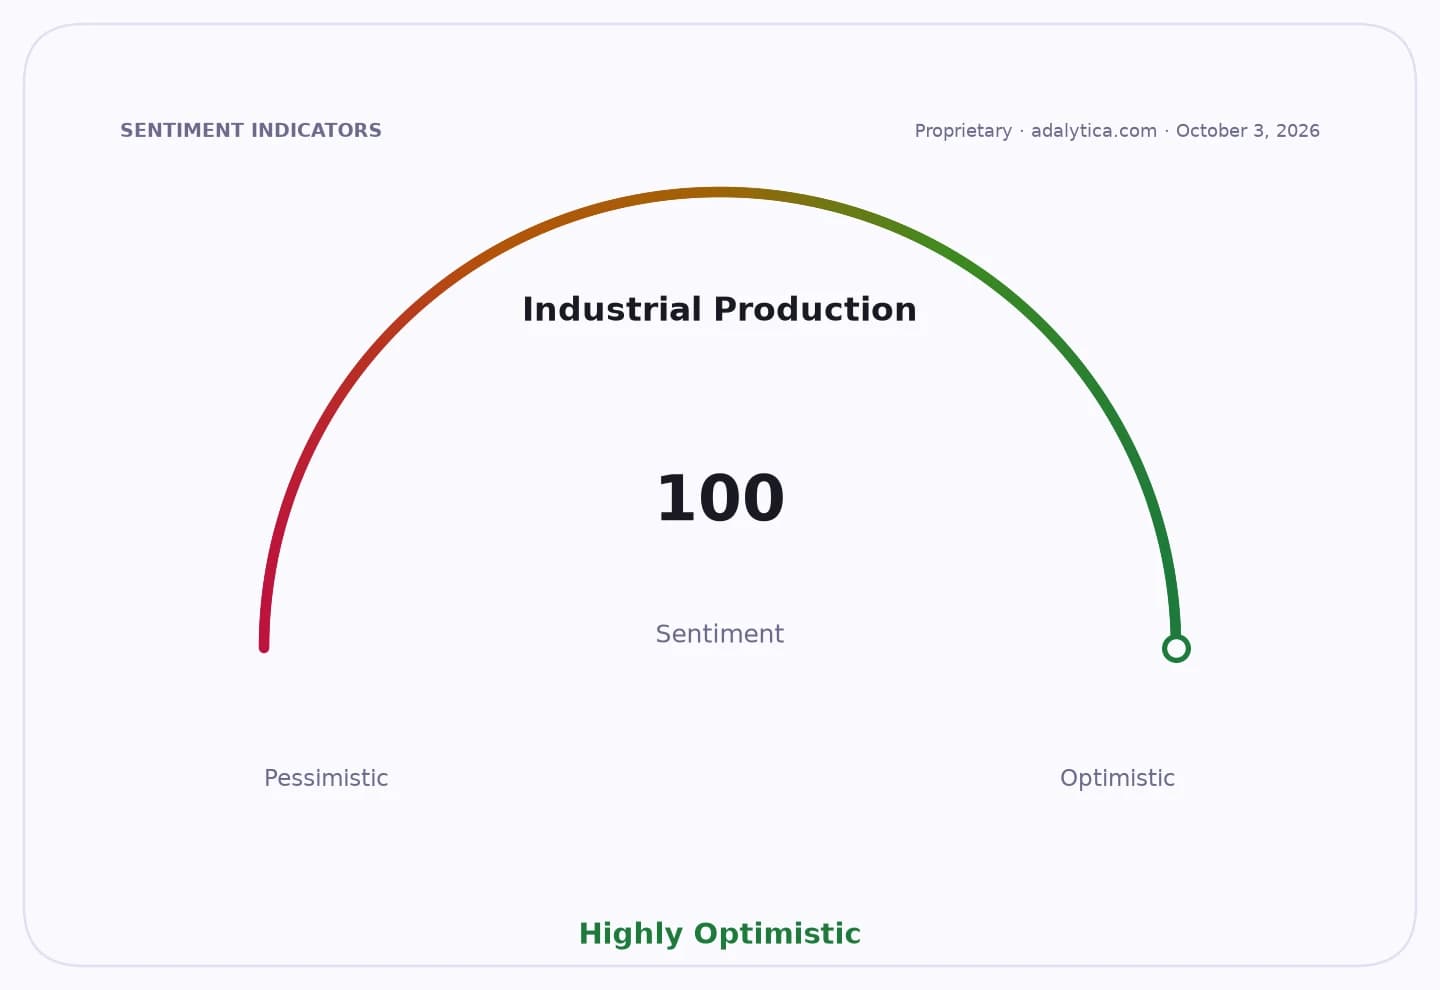
Vietnam’s industrial production accelerated in the first nine months of the year, with output rising 12.3% from a year earlier, the fastest pace for the period since 2019 and a sign that manufacturing is regaining momentum across the economy.
Vietnam industrial production rises 12.3% in 9 months
The gain matters because industry remains a key engine for Vietnam’s growth, exports and employment. A broad-based pickup also suggests the recovery is not limited to a handful of factories or regions: the industrial production index rose in all 34 provinces and cities, underscoring a synchronized rebound after a softer stretch for global trade.
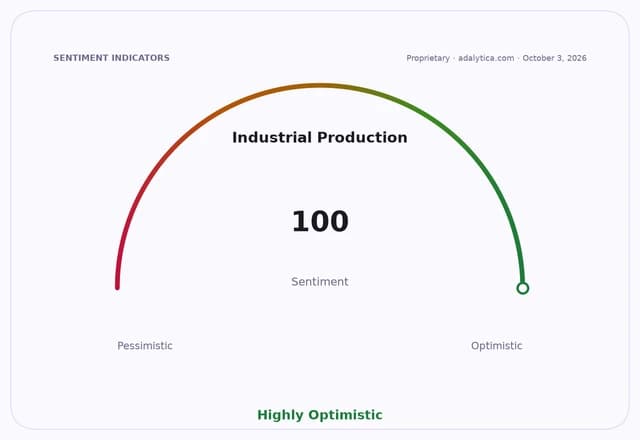
Sentiment IndicatorsⓘProprietary · adalytica.com · October 3, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The strongest support came from manufacturing, which climbed 12.9% and contributed 10 percentage points to overall industrial growth. Electricity production and distribution rose 10.6%, while mining advanced 8%, helping lift the third-quarter industrial production index by 14.8% from a year earlier.
Several major sectors posted double-digit gains, including basic metals, up 25.5%; beverages, up 17.4%; motor vehicles, up 15.3%; and electronics, computers and optical products, up 15.2%. Product output also strengthened, with tablet production jumping 36.5%, motorcycles 28.1%, laptops 26.2% and cars 24.8%.
The breadth of the rebound is important for investors because it points to healthier domestic industrial demand and improving export execution. The statistical office said the advance was helped by the startup of large projects, a recovery in export orders and faster public investment, all of which can feed through to construction, logistics, machinery and industrial suppliers.
There are still signs of caution beneath the headline strength. Inventory in manufacturing rose 11.9% as of Sept. 30 from a year earlier, suggesting some firms are still building stock faster than they are clearing it. Employment in industrial firms was up 3.4%, and 34.2% of manufacturers said third-quarter business conditions improved from the prior quarter, but 20.1% still reported difficulties.
For markets, the data reinforces the case for industrial-linked stocks and exporters that benefit from improving factory activity, while keeping focus on whether demand remains strong enough to absorb higher inventories. The next test is whether fourth-quarter orders and public investment can sustain the pace without a sharper build-up in stock or a slowdown in external demand.
| Entity | Gains | Losses |
|---|---|---|
| Vietnam manufacturers | ▲Higher output, stronger orders | ▼Higher inventory build |
| Exporters | ▲Recovery in export demand | ▼Global demand slowdown risk |
| Industrial suppliers | ▲More factory and project activity | ▼Input and stock pressure |
| Investors in industrial names | ▲Better growth visibility | ▼Risk of uneven Q4 follow-through |