Stablecoins are moving from crypto trading rails to everyday payments, and Visa’s tie-up with Reap shows the network wants to own that transition before rivals do.
Visa and Reap Expand Stablecoin Card Programs
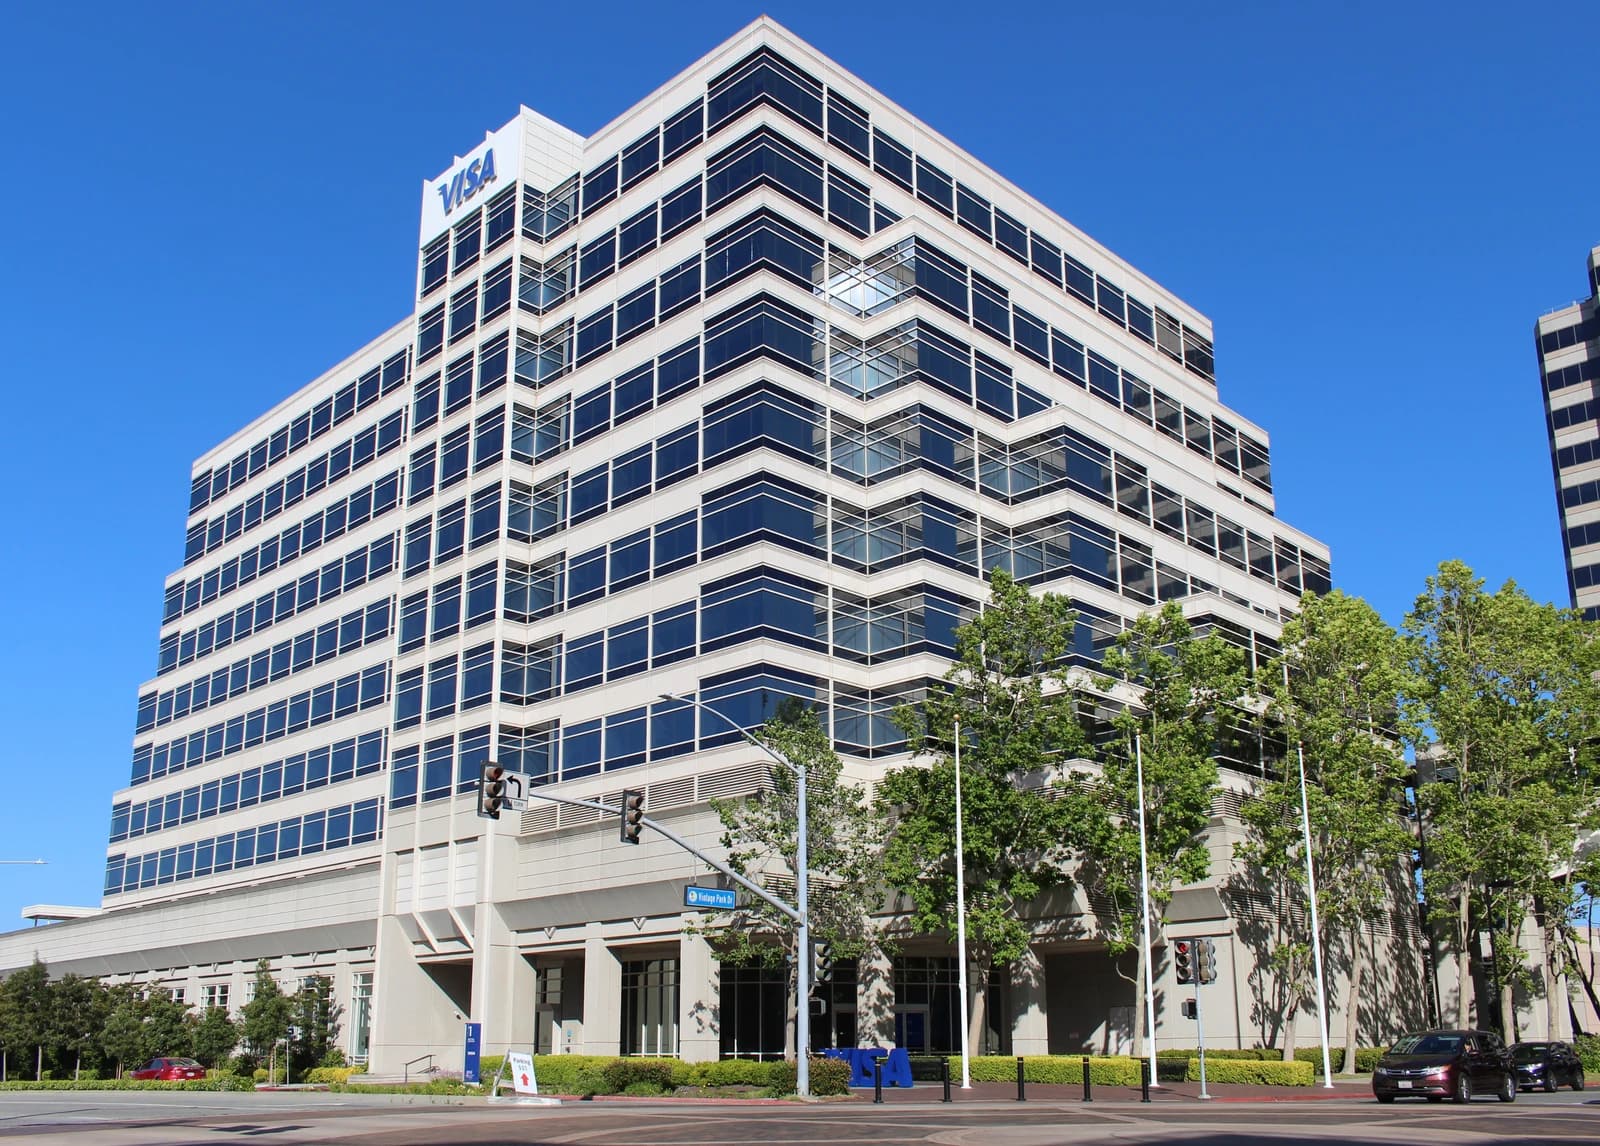
The collaboration gives fintechs, businesses and platforms a way to issue Visa credit card programs funded or repaid with stablecoins across more than 100 markets, including an expansion beyond Asia and Latin America into EMEA and Africa. That matters because the real prize in digital money is not just holding stablecoins, but turning them into usable spending power at scale. Visa already says stablecoin settlement is running at a $20 billion annualized pace, up 15 times from a year ago, and more than 160 stablecoin card programs are already live globally. Reap’s role is to provide the compliance, issuance and processing layer that lets partners launch faster without building the plumbing themselves.
Sentiment IndicatorsⓘProprietary · adalytica.com · September 28, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
For investors, this is a clear signal that stablecoins are becoming a payment infrastructure story, not just a crypto story. The economics are attractive: card programs can reduce reliance on pre-funded balances, improve cross-border liquidity management and cut the friction of weekend and off-hours settlement by moving obligations onchain. That creates a new toll road for Visa, which earns from network activity, and a potentially faster-growth distribution channel for fintech partners that can package treasury, payouts and spend management into one card experience.
The strategic implication is bigger than one partnership. Visa is effectively hardening its moat by embedding stablecoin settlement into the same global merchant acceptance network that already reaches 175 million locations. That makes it harder for alternative rails to displace card usage while still capturing the upside from blockchain-native money movement. Reap, meanwhile, gains a powerful global partner and first-mover status as the first Asia-based fintech to enable stablecoin credit card issuing at scale with Visa.
The market should also pay attention to the next phase: multicurrency stablecoin cards and agentic commerce, where AI-driven payment execution is handled within defined rules and compliance guardrails. If that sounds speculative, it is still the direction the payments stack is headed. The winners are the companies that own compliant infrastructure, settlement and distribution, not just the tokens themselves.
For now, the actionable takeaway is straightforward: stablecoin adoption is increasingly a fee-rich, enterprise-grade payments opportunity, and Visa remains one of the best-positioned picks-and-shovels beneficiaries. Reap’s expansion may be a template for the next wave of global card programs, but Visa is the one turning that wave into a network effect.
| Entity | Gains | Losses |
|---|---|---|
| Visa | ▲More stablecoin volume | ▼Legacy-only payment rivals |
| Reap | ▲Global card distribution | ▼Smaller regional fintechs |
| Businesses/fintechs | ▲Faster settlement, lower friction | ▼Pre-funded treasury models |
| Crypto-native stablecoin rails | ▲Mainstream usage | ▼Pure trading-only narratives |